Is a cash-out refinance or a home equity loan better?
The three structures work differently. A cash-out refinance replaces your whole first mortgage with a new, larger one: new terms on the full balance, and one payment. A home equity loan leaves your first mortgage alone and adds a second loan, paid out once: two payments. A HELOC is a second line you draw on over time, and its rate is usually variable. A cash-out refinance carries closing costs on the whole new loan; a second loan has its own, usually smaller, set of costs.
For a Michigan homeowner, none of the three uncaps your taxable value. Each is a loan secured by the home you already own, and Michigan's law treats a transfer for security as something other than a sale (MCL 211.27a), so the cap on your taxable value stays where it is.
Which structure do your answers point toward?
You do not start with the product, you start with the goal. Three things decide
the direction: what happens to your existing mortgage, how you need to receive the money, and how
long you expect to need it. This will not point anywhere until it has all three, because pointing
early is how people end up with the wrong structure.
This points at a structure to discuss. It is not a quote, an offer, a credit
decision or a recommendation, and it does not evaluate your eligibility for any loan program. Which
options are available to you depends on the property, the program and a full review.
Align Lending LLC, NMLS #2041154. Equal Housing Opportunity.
What you will walk away knowing
Which structure fits what you are trying to do, and why the others do not.
Your situation. That is honestly the answer to half of these questions.
Your existing mortgage. Your equity. What you need the money for. How you want to access it. How long you expect to use it. And what the whole thing looks like once you put it together rather than looking at any one piece on its own.
Notice that none of those is which product sounds better. That is the point.
What happens to the rate you have now?
A cash-out refinance replaces it on the whole balance. A home equity loan or a HELOC leaves it in place and adds a second rate on the new money only.
That is why the rate you hold today is the first number to find. The lower it is, the more a second loan tends to make sense.
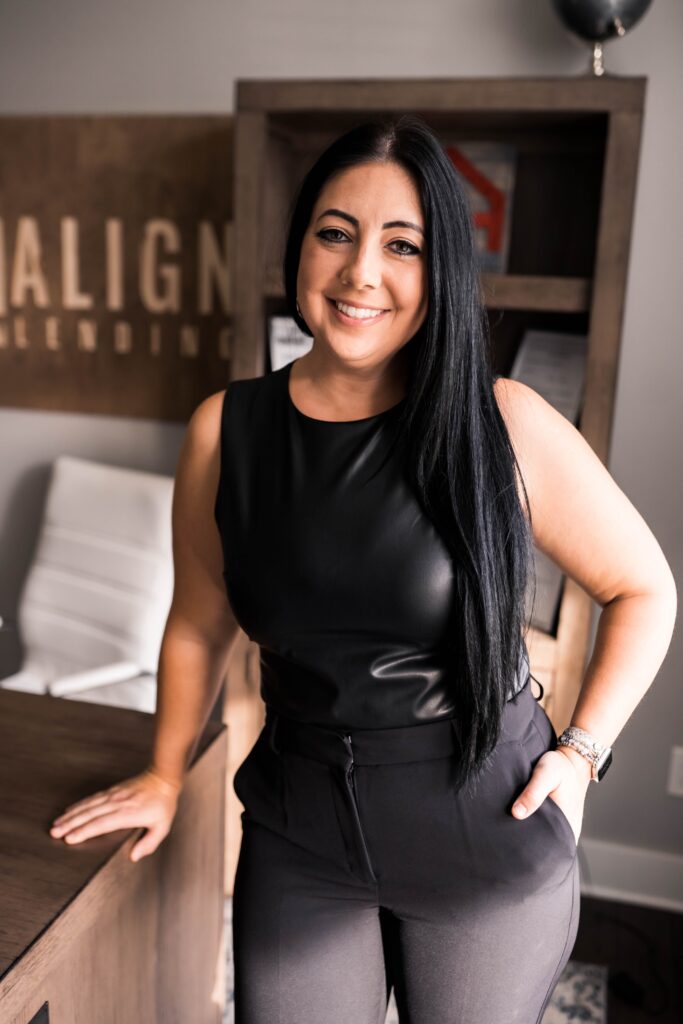
Samantha Shelton has been a licensed loan officer since May 2020 and founded Align Lending in August 2020. Before mortgages she was a stay-at-home mom raising three boys.
In her own words: "I own a mortgage brokerage in Michigan and I help people understand their options before they make one of the biggest financial decisions they are ever going to make."
Recognition includes Hall of AIME, NAMB Broker of the Year, and Woman with Vision, along with her leadership work with AIME.
Align Lending LLC, NMLS #2041154. Samantha Shelton, NMLS 1647301. Licensed in Michigan, Ohio, North Carolina, Florida, Louisiana and Texas.
I highly recommend Align Lending to anyone looking for a mortgage broker in Southeast Michigan. The team was knowledgeable, responsive, and easy to work with.
If yours is not here, ask it on the call. There are no dumb questions.
Do I need all of the money now, or access to money over time?
That single question settles more than any comparison table. A defined amount you need now points to money paid out once, by a home equity loan or by a cash-out refinance. Money you expect to need off and on points to a line you draw on, a HELOC.
What is the actual difference?
Mainly whether your first mortgage is replaced, and whether you end up with one payment or two. A home equity loan or a cash-out refinance pays the money out at once; a HELOC lets you draw it over time.
Do I have to touch my first mortgage?
Not necessarily. Whether that is a good idea depends on your existing mortgage and what you are trying to do.
Can I change my mind later?
Options exist either way, but unwinding a decision costs more than making the right one first.
What if I only need some of it now?
Then how you access the money matters as much as how much, and that changes which approach fits.
Does it matter how long I need the money?
It matters a lot. A line you draw on fits money you will use off and on over years; a loan paid out once fits a cost you can name today and pay down on a schedule.
What clients say
5.0 on Google across 128 reviews
★★★★★
Align Lending made refinancing my home in Rochester Hills simple and straightforward. I was kept updated throughout the process and felt confident in the option I chose.
Nathan Lobo
★★★★★
Samantha Shelton is absolutely amazing at helping families with their home loans! If you are in the metro Detroit area and need an expert to help you, whether you’re a first-time homebuyer or need a refinance, I highly recommend Align Lending
Darryl Taylor Jr.
★★★★★
Sam is an expert helping choose the right financing options for her clients!
Andrew Kuhn
★★★★★
Samantha is so smart and helpful. She answered all my questions and she followed up with me a week later to ensure I had my questions answered again. She is amazing.
Jason Sych
★★★★★
Working with Samantha and her team was such a breath of fresh air. They are extremely professional and always go above and beyond every expectation. A true pleasure to work with.
Align Lending LLC, NMLS #2041154. Samantha Shelton, NMLS 1647301. Equal Housing Opportunity. Licensed in Michigan, Ohio, North Carolina, Florida, Louisiana and Texas. This page is for educational purposes only. It is not a credit decision, a preapproval, a commitment to lend, or an offer of credit, and it does not evaluate your eligibility for any loan program.
Scroll to Top
All at once or over time? I'll compare a cash-out, an equity loan and a HELOC.