

Michigan Homebuyer Game Plan
You do not have to be ready to talk to us
Most people wait until they think they have it figured out. That is backwards. The earlier we talk, the more options you have and the less any of this costs you in stress.
- No application required
- No credit pull to talk
- 5.0 on Google, 128 reviews
What should I do before I buy a house?
Talk to somebody. That is genuinely the first step.
You do not have to apply for anything because you had a conversation. You do not have to buy a house. We are just figuring out where you are.
Most people do the opposite. They start looking at houses, because looking at houses is fun and talking about documents and taxes is not. But if you fall in love with a house before you understand your own numbers, you are doing the whole thing backwards.
Align Homebuyer Game Plan
How ready are you to buy a home?
Eight questions, about two minutes. You will get a clear picture of where you stand and what is worth working on before you start making offers.
This is an educational self assessment. It is not a credit decision, a preapproval, or an offer of credit, and it does not affect your credit.
Your readiness picture
What is worth working on first
Leave with a plan, not more questions
Talk it through with Samantha. No application, no credit pull, just a conversation about your situation and what comes next.
Align Lending LLC, NMLS #2041154. Equal Housing Opportunity. Licensed in Michigan, Ohio, North Carolina, Florida, Louisiana and Texas. This assessment is for educational purposes only. It is not a credit decision, a preapproval, a commitment to lend, or an offer of credit, and it does not evaluate your eligibility for any loan program. Any financing options available to you depend on a complete application, a review of your credit and income, the property, and program requirements.
Want to talk through what this means for you?
Samantha will look at where you landed and tell you what actually matters in your situation.
Where are you in your journey?
Just Starting
You are thinking about it and have not talked to anybody yet.
Mortgage Readiness ReviewBuying My First Home
You want to know what is normal and what happens next.
First-Time HomebuyerWorking Out My Budget
You want a number that fits your life, not the maximum.
Homebuying Budget ReviewI Own and Need to Move
You are buying and selling, and the order matters.
Buy Before You SellSelf-Employed
Your income is documented differently. Different, not harder.
Self-Employed HomebuyerVeteran
You may have an option a lot of buyers do not.
VA Homebuyer PlanWhat is the difference between what I qualify for and what I should spend?
This is the thing Samantha ends up explaining more than anything else.
A lender's maximum and a monthly payment that fits your life are different numbers, so we start from the payment you are comfortable with and work back from there. The Homebuying Budget Review walks through it with your own numbers.
Just because a number works on paper does not mean it is the right number for your life.
Michigan property taxes
Why you cannot use the seller's tax bill
Michigan property taxes confuse people because the taxes the seller is paying today do not automatically become the taxes you are going to pay.
Your taxes are figured from the home's taxable value. And when ownership changes, that taxable value can change.
The short version we use on a call: the current owner may have had their taxable value limited while they owned the home. When the property changes hands, that value can reset under Michigan's rules. So we estimate your taxes as the new owner rather than using somebody else's old bill.
We take this seriously when we build your numbers. Not every house will see a large change, but it can absolutely matter to your monthly housing expense. The year after a Michigan home sells, its taxable value resets to half of the assessor's market value, so the seller's tax bill is not your tax bill. For an address you are looking at, the Michigan property tax calculator works out the new owner's bill from that property's own published millage.
What this looks like in practice
Somebody looks at a house online, sees the seller's current property taxes and builds their whole budget around that number. They look at the payment. They look at the existing taxes. Everything feels comfortable. And to them the tax number looks official. It is right there on the property. Why would that not be their number?
The problem is the seller may have owned that house for a long time. Their taxable value may have been capped while they owned it. When ownership changes, Michigan can treat that taxable value differently in the following tax year.
So we stop the buyer and say, do not build your budget around somebody else's tax bill. That is the simplest way we know how to explain it. The seller's tax history tells us something about the property. It does not automatically tell us what your taxes are going to look like as the new owner.
That is why we would rather estimate the taxes based on what the new ownership could look like, and explain why we are doing it. We would much rather somebody ask why our taxes are higher than what they are seeing online than have them build a housing budget around the wrong assumption.
Buying in Michigan before you move here
Relocating buyers usually bring two questions to the first call: can I get approved before I live here, and what will this house really cost once I own it. Both have Michigan answers, and both are easier to settle before you tour.
If your new job starts after closing, many loan programs can work from a signed offer letter, within limits each program sets, so bring the letter to the first call. A primary-residence loan expects you to move in within 60 days of closing. If you cannot be here to sign, ask early about a mail-away or remote closing; the title company and the lender decide what they allow.
Then budget with Michigan numbers, not the ones from home. Use the new-owner tax estimate explained above, not the seller's bill. In Michigan the seller usually pays the state and county transfer tax, and we walk you through the rest of the costs before you make an offer.
Settle the financing questions before you move here.
Loan options
The loans to compare first
Conventional Loan
If your credit and income are steady, start here. Mortgage insurance applies with a smaller down payment, and borrower-paid mortgage insurance can come off as you build equity.
How it worksFHA Loan
Fits a thinner credit history or a recent setback. The tradeoff is FHA mortgage insurance, which can last the life of the loan.
How it worksVA Loan
For eligible veterans, service members and some surviving spouses. No monthly mortgage insurance; a funding fee applies unless you are exempt.
How it works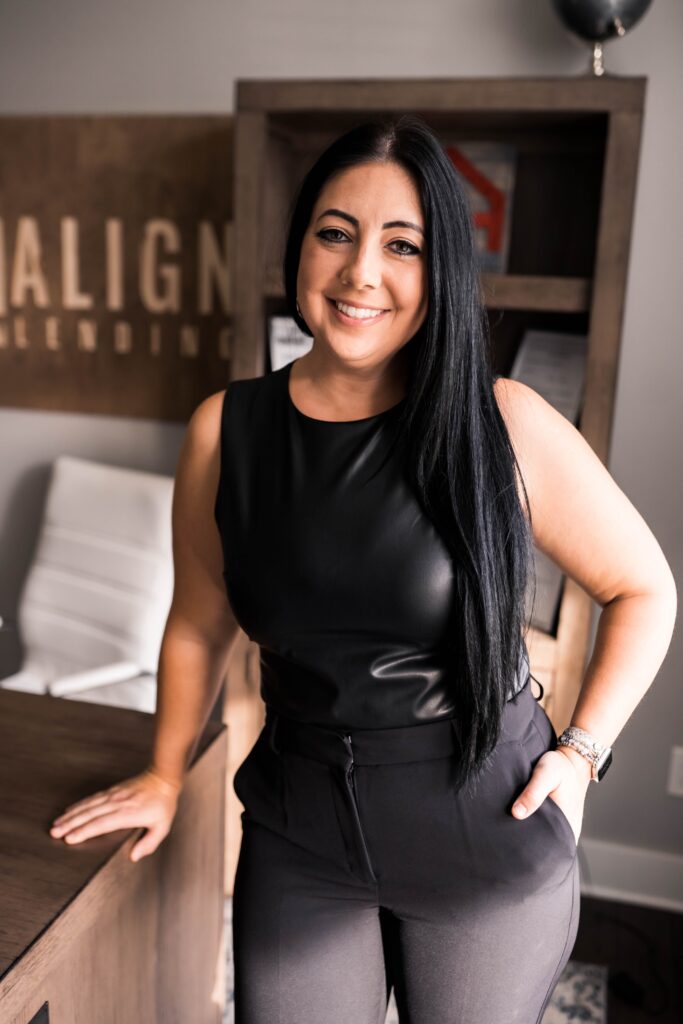
About Samantha
Samantha Shelton has been a licensed loan officer since May 2020 and founded Align Lending in August 2020. Before mortgages she was a stay-at-home mom raising three boys.
In her own words: "I own a mortgage brokerage in Michigan and I help people understand their options before they make one of the biggest financial decisions they are ever going to make."
Recognition includes Hall of AIME, NAMB Broker of the Year, and Woman with Vision, along with her leadership work with AIME.
Align Lending LLC, NMLS #2041154. Samantha Shelton, NMLS 1647301. Licensed in Michigan, Ohio, North Carolina, Florida, Louisiana and Texas.
Read Samantha's storyAlign Lending helped me compare mortgage options for my home purchase in Troy and explained everything clearly. The entire process was smooth and straightforward.
Individual experience. Results vary.
Check it yourself
Where these rules come from
The official pages behind the rules on this page.
Questions people actually ask
If yours is not here, ask it on the call. There are no dumb questions.
What actually happens on the first call?
It helps to have a rough idea of three things: your monthly debts, what you have set aside, and when you would like to move. None of it has to be in good shape yet, and there is no credit pull to talk.
Am I too early to talk to somebody?
Almost certainly not. If you are buying next year, the conversation might be ten minutes. You will still know whether there is anything worth paying attention to between now and then.
Am I wasting your time if I am not ready?
No. You do not need to have everything figured out before you talk to a mortgage professional. We would rather be part of figuring it out.
How much house should I be looking at?
Start from the monthly number that feels comfortable to you rather than the maximum anyone will approve, then work backward. Those are different figures and the difference is yours to decide.
Do I need to talk to a lender before a real estate agent?
It helps. An agent can show you anything. Knowing your range first means the homes you see are homes you would actually be comfortable buying.
Will this affect my credit?
The assessment and the conversation do not. A preapproval does involve reviewing your credit, and we will tell you before that happens.
What if my credit is not where I want it?
That is a reason to start earlier, not a reason to wait. Some things take time to show up, which is exactly why a year out is a better place to start from than two months out.
I am self employed. Is that a problem?
Not by itself. It means your income is documented differently and the preparation looks different. Worth planning for rather than discovering partway through.
Am I committing to anything?
No. It is a conversation. No application, no obligation, no cost.
What clients say
5.0 on Google across 128 reviews
Working with Samantha at Align Lending made buying my home in Royal Oak much easier than I expected. The communication was clear, and I always knew what the next step was.
Align Lending helped make purchasing my home in Madison Heights a smooth experience. I appreciated the regular updates and clear explanations along the way.
As a first time homebuyer in Birmingham, I fully trusted Samantha at Align Lending for my loan. Her guidance was amazing!
Samantha is very professional, organized, and will make the mortgage process as smooth as possible.
Samantha is so smart and helpful. She answered all my questions and she followed up with me a week later to ensure I had my questions answered again. She is amazing.
Individual experiences. Results vary.
You should leave this better, not sold
Tell Samantha what you are trying to do, and she will help you understand what comes next. No application, no credit pull, no obligation.
- 1
Tell us what you are trying to do
Not what mortgage you want. What you are actually trying to accomplish.
- 2
We look at your situation
Samantha works out what matters most for you specifically.
- 3
You leave with a plan
Your budget, your timeline, your cash needs, your next step. No obligation to go further.
Related reading
Background from the Align Learn Center, if you want to read before you talk to anybody.
- Home buying strategies for every market and situation
- The Home Buying Process: Every Step From Start to Finish
- How to prepare for a home closing: your step-by-step checklist
Serving homebuyers across Michigan
See all service areasAlign Lending LLC, NMLS #2041154. Samantha Shelton, NMLS 1647301. Equal Housing Opportunity. Licensed in Michigan, Ohio, North Carolina, Florida, Louisiana and Texas. This page is for educational purposes only. It is not a credit decision, a preapproval, a commitment to lend, or an offer of credit, and it does not evaluate your eligibility for any loan program.
