Align Lending

Home Equity Strategy Review

Your house is not an ATM

Equity is valuable. Before we talk about how to access it, the first question is always why.

  • No application required
  • No credit pull to talk
  • 5.0 on Google, 128 reviews

Should I use my home equity?

Your house has a value. You owe money against it. The difference between those two numbers is basically the equity you have in the home. That does not mean all of it is cash you can take out, but that is the simple idea.

The first question is never which product. It is why. What are we using the money for? What does the new debt look like? How does this fit the rest of your finances?

How much equity do you have, and what is it for?

The arithmetic is the easy part. The question that actually decides whether using it is a good idea is what you would use it for. Enter your own figures, nothing is sent anywhere.

$
$

This is arithmetic on numbers you entered. It is not a quote, an offer, a credit decision or a recommendation, and it does not evaluate your eligibility for any loan program. How much of your equity could actually be borrowed against depends on the program, the property and a full review. Align Lending LLC, NMLS #2041154. Equal Housing Opportunity.

What you will walk away knowing

Why you want to use it, before anything about how.

Talk through my equity options

Why comes before how

What should I think about before borrowing against my home?

What are we using the money for. What does the new debt look like. How does this fit into the rest of your finances.

The reasons people ask about equity are usually debt consolidation, renovations, a large expense, an investment, or wanting liquidity available. Each of those is a question worth examining rather than a use case we would endorse in advance.
When would you tell somebody not to?

When the reason does not hold up.

Sometimes it is because nobody can explain what the money is for. More often it is because, once we talk it through, the person realizes they are solving a short-term problem by creating a bigger long-term one.

Sometimes the best mortgage advice anybody can give is that you should not change anything. That is a completely acceptable outcome, and you will not be talked out of it here.

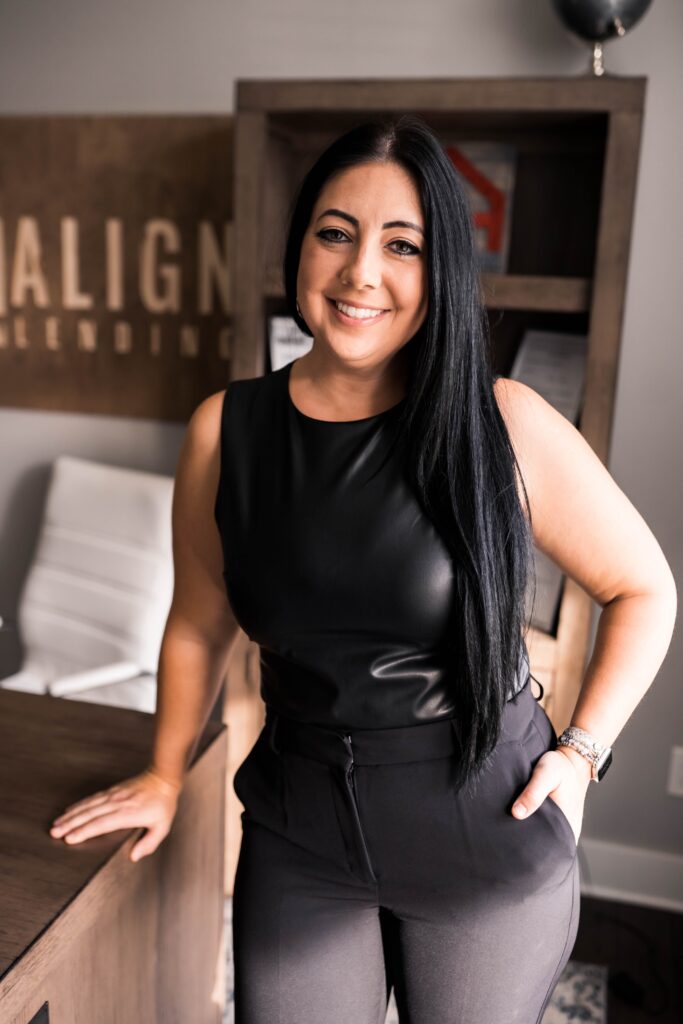
Samantha Shelton in the Align Lending office

About Samantha

Samantha Shelton has been a licensed loan officer since May 2020 and founded Align Lending in August 2020. Before mortgages she was a stay-at-home mom raising three boys.

In her own words: "I own a mortgage brokerage in Michigan and I help people understand their options before they make one of the biggest financial decisions they are ever going to make."

Recognition includes Hall of AIME, NAMB Broker of the Year, and Woman with Vision, along with her leadership work with AIME.

Align Lending LLC, NMLS #2041154. Samantha Shelton, NMLS 1647301. Licensed in Michigan, Ohio, North Carolina, Florida, Louisiana and Texas.

Read Samantha's story

Sam is an expert helping choose the right financing options for her clients!

Andrew Kuhn, Google review

Individual experience. Results vary.

Check it yourself

Where these rules come from

The official pages behind the rules on this page.

Questions people actually ask

If yours is not here, ask it on the call. There are no dumb questions.

What happens if I do not borrow it?

Sometimes that is the right answer, and it belongs on the table next to the others. Sometimes the most useful mortgage advice is that you should not change anything. Doing nothing is a legitimate outcome, not a failure to decide.

There are ways to, yes. Which one fits depends entirely on what you are trying to do.

Sometimes that makes sense and sometimes it moves a short-term problem into a long-term one. It depends on the whole picture.

Not all of it, and the amount depends on the property, your situation and the approach. That is a conversation, not a formula.

When nobody can clearly explain why you are doing it.

Your house has a value. You owe money against it. The difference between those two numbers is basically the equity you have in the home. That does not mean all of it is automatically cash you can take out, but that is the simple idea.

No. Having equity is not a reason to access equity. The reason has to come from what you are trying to accomplish.

Then say that. Working out whether something is a good idea is most of the conversation, and leaving it alone is a legitimate place to land.

Having equity is not a reason to access equity

The reason has to come from what you are trying to accomplish. Doing nothing is a legitimate outcome, not a failure to decide.

  1. 1

    Tell us what you are trying to do

    Not what product you want. What you are actually trying to accomplish.

  2. 2

    We look at your situation

    A licensed Align loan officer works out what matters most for you specifically.

  3. 3

    You leave with a plan

    Your options, the tradeoffs, and your next step. No obligation to go further.

Align Lending LLC, NMLS #2041154. Samantha Shelton, NMLS 1647301. Equal Housing Opportunity. Licensed in Michigan, Ohio, North Carolina, Florida, Louisiana and Texas. This page is for educational purposes only. It is not a credit decision, a preapproval, a commitment to lend, or an offer of credit, and it does not evaluate your eligibility for any loan program.

Scroll to Top
Align Lending logo