Most people think affordability is a single number a lender gives them. It is not. There is a qualification calculation, and then there is your actual life. Both matter.
The maximum somebody can qualify for and the amount they actually feel comfortable paying every month are not always the same number. We do not live in your house. We do not know what you spend on travel, kids, restaurants, sports or daycare, and a mortgage calculation does not know that either.
So we start somewhere more useful than the maximum: what monthly housing expense feels comfortable to you? Then we work backward.
What does comfortable actually have to cover?
Start with the number that feels comfortable rather than the maximum somebody
qualifies you for. Then look at what has to fit inside it, because the monthly housing number is
carrying more than the loan. Enter your own figures, nothing is sent anywhere.
This is arithmetic on numbers you entered. It is not a quote, an offer, a credit
decision or a recommendation, and it does not evaluate your eligibility for any loan program.
Align Lending LLC, NMLS #2041154. Equal Housing Opportunity.
What you will walk away knowing
A monthly housing number that fits your life, and the reasoning behind it.
Taxes and insurance are the ones people forget. Depending on the property there can be association dues as well.
Michigan property taxes deserve their own mention here, because the taxes the seller pays today do not automatically become yours. We estimate your taxes as the new owner rather than using somebody else's bill.
What costs should I expect besides the down payment?
Usually it is not one giant surprise. It is that there are several different buckets, and people only planned for one of them.
There is the money going toward the purchase itself. There are closing costs. There may be prepaid items like taxes and insurance. There may be inspection costs. People hear the words down payment and sometimes assume that is the entire amount of money involved. It is not always.
They also do not all happen at once. An inspection happens before closing. Other items come up during the loan process depending on the transaction. Then there is the final money handled at closing. The part that matters is that nobody should be learning about one of those categories the day before closing. We should be talking through them well before that.
People repeat that one all the time. There are different loan programs with different down payment structures, and which ones apply depends on your situation rather than on a figure somebody heard somewhere.
That does not mean putting less down is automatically better. It means the decision should come from real information about what is available to you. Before you spend another year working toward a number, it is worth finding out whether that number applies to you at all.
The first thing worth asking is who told you that.
What this looks like in practice
Deciding you cannot before anybody has looked
Somebody calls and tells us why they cannot buy a house before we have even asked a question. My credit is not good enough. I do not have enough money. I need to wait. I need a huge down payment.
And they say it like somebody already made the decision. So the first question is usually, who told you that? Sometimes it is a friend. Sometimes a parent. Sometimes something they read online. Sometimes they do not even remember. They have just believed it long enough that it feels true.
That is what we want people to stop doing. Do not deny yourself before anybody understands the situation. Maybe you are ready. Maybe you are not. Maybe you need time. All of those answers are fine.
But get the answer from your actual situation instead of from somebody else's mortgage.
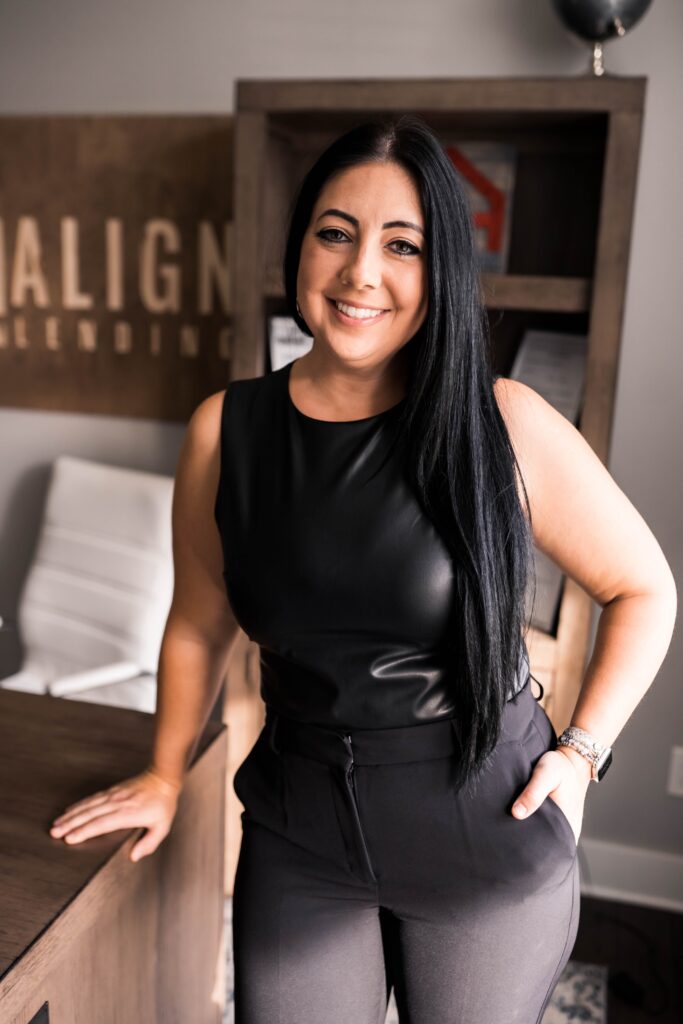
Samantha Shelton has been a licensed loan officer since May 2020 and founded Align Lending in August 2020. Before mortgages she was a stay-at-home mom raising three boys.
In her own words: "I own a mortgage brokerage in Michigan and I help people understand their options before they make one of the biggest financial decisions they are ever going to make."
Recognition includes Hall of AIME, NAMB Broker of the Year, and Woman with Vision, along with her leadership work with AIME.
Align Lending LLC, NMLS #2041154. Samantha Shelton, NMLS 1647301. Licensed in Michigan, Ohio, North Carolina, Florida, Louisiana and Texas.
If yours is not here, ask it on the call. There are no dumb questions.
What am I not willing to give up just to own the house?
That is one of the most useful questions you can answer before you start. Travel, kids, restaurants, sports, whatever it is for you. If buying the house means giving up something you are not actually willing to give up, the number is wrong no matter what the calculation says.
Does preapproval tell me what I should spend?
No. It tells you what you may be able to borrow. What you should spend is a different question, and it is yours to answer.
What if I am comfortable with less than I qualify for?
That is a completely reasonable place to land, and it is the outcome we see most often once somebody actually thinks about it.
Does my car payment matter?
Recurring monthly obligations are part of the picture. Knowing what yours add up to is worth fifteen minutes before any conversation.
Why is the online estimate different from yours?
Online tools guess at taxes and insurance. They are useful for orientation. They are not your actual mortgage.
How do you land on a comfortable number?
We ask you. What does your life look like, what are you paying now, does that feel comfortable, do you travel, do you have kids, is there anything you are not willing to give up just because you bought a house. Then we build the housing decision around your life instead of making your life fit around the mortgage.
Do Michigan property taxes change what I can afford?
They can, and they are one of the most commonly underestimated parts of a Michigan payment. Taxable value generally uncaps the January after a sale, so the tax the current owner pays is not necessarily the tax you will pay. We estimate yours as the new owner rather than quoting somebody else’s bill.
Should maintenance be part of the number?
Yes. You have a house now. Things break, utilities change, and there is ongoing maintenance. That is exactly why we do not build a budget right to the absolute edge.
Get the answer from your actual situation
Not from the maximum, and not from somebody else's mortgage. Maybe you are ready. Maybe you need time. All of those answers are fine.
Align Lending LLC, NMLS #2041154. Samantha Shelton, NMLS 1647301. Equal Housing Opportunity. Licensed in Michigan, Ohio, North Carolina, Florida, Louisiana and Texas. This page is for educational purposes only. It is not a credit decision, a preapproval, a commitment to lend, or an offer of credit, and it does not evaluate your eligibility for any loan program.