
How to spot the hidden costs in a home purchase
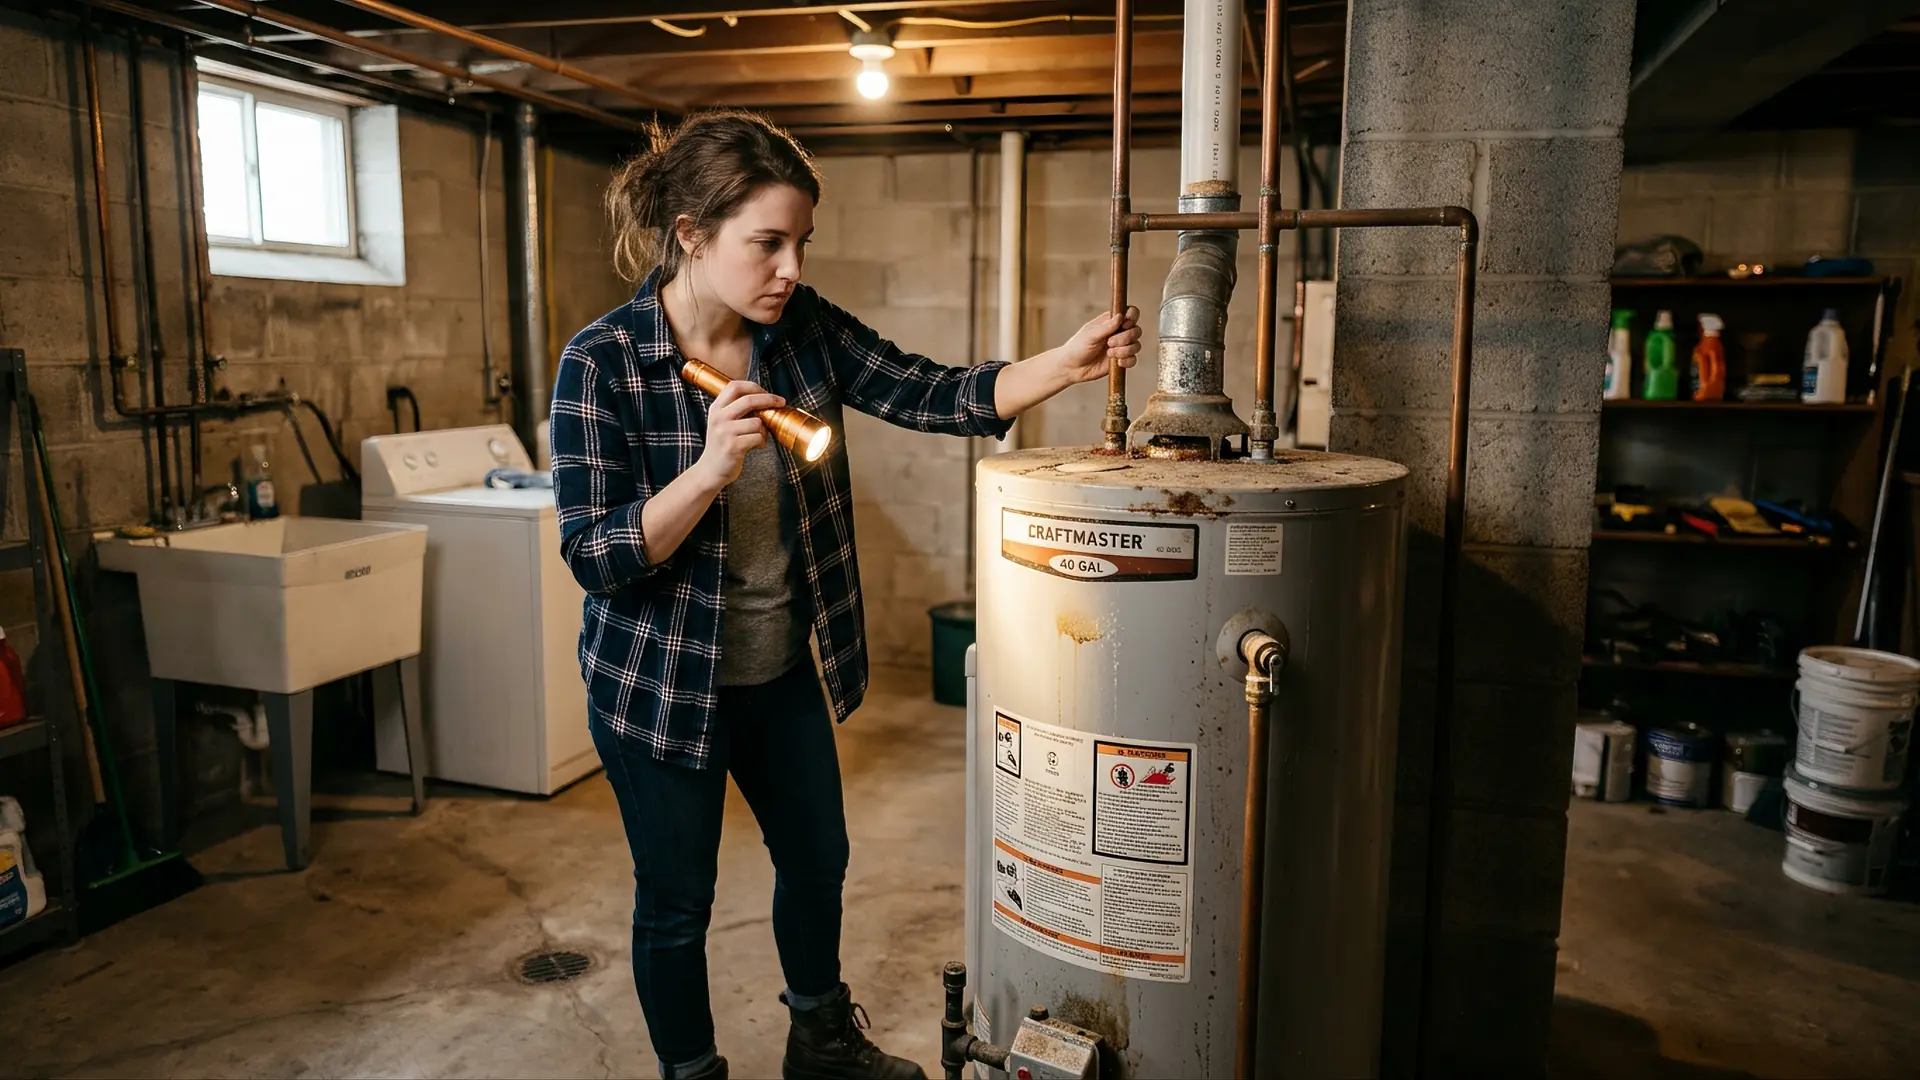
The hidden costs of a home purchase fall into three buckets, and the largest one is closing costs, generally 2% – 5% of the purchase price, owed on top of a down payment that typically runs 3% – 20%. On a $300,000 home, that’s $6,000 – $15,000 in cash due at the table before you own a single appliance.
The second bucket is recurring, property taxes, insurance, HOA dues, and utilities, every month for as long as you own the place. The third is maintenance, where a widely used rule of thumb is 1% – 2% of home value per year, or $3,000 – $6,000 on that same $300,000 house.
Spotting them early takes two habits: read your Loan Estimate line by line, and research the specific property’s taxes, insurance, and utility history before you offer. Learn how to spot the hidden costs in a home purchase, including which fees you can shop for and how Michigan’s tax rules reset the math after you close.
Key takeaways:
- Closing costs are the biggest upfront surprise: Budget 2% – 5% of the purchase price for closing costs, separate from your down payment, $6,000 – $15,000 on a $300,000 home.
- Recurring costs never stop: Taxes, insurance, and HOA dues add hundreds of dollars a month, and because escrow is re-analyzed every 12 months, the payment you close with is not the payment you keep.
- Reserve 1% – 2% of home value a year for maintenance: Setting aside $3,000 – $6,000 annually on a $300,000 home covers the roof, furnace, and water heater bills that arrive on their own schedule.
What are the hidden costs of buying a home?
The hidden costs are every dollar outside the down payment and the principal-and-interest payment, roughly 2% – 5% of the price at closing, a monthly load of taxes, insurance, dues, and utilities, and 1% – 2% of home value a year in upkeep. None are secret; they just arrive on three documents at three different times. Our Home Buying guide maps the sequence; here’s what each piece costs.
| Cost | Typical range | When it hits |
|---|---|---|
| Home inspection | $300 – $500 | Out of pocket, days after your offer is accepted |
| Appraisal | $300 – $600 | Ordered by your lender early in underwriting |
| Earnest money deposit | 1% – 2% of purchase price | With your offer; credited back to you at closing |
| Closing costs | 2% – 5% of purchase price | Cash due at the closing table |
| Escrow reserves and prepaids | About 2 months of taxes and insurance, plus the first year’s premium | At closing, inside the closing-cost total, not on top of it |
| Taxes, insurance, HOA dues, utilities | Varies by property, not by loan | Every month, for as long as you own it |
| Maintenance and repairs | 1% – 2% of home value per year | Unpredictably, starting the week you move in |
What upfront costs should you expect before closing?
Expect roughly $600 – $1,100 out of pocket before you reach the closing table, plus earnest money of 1% – 2% of the purchase price. These costs hurt most, because they’re spent while the deal can still fall apart.
Inspection and appraisal fees come out of pocket early
A home inspection typically runs $300 – $500 and an appraisal $300 – $600, and you pay both whether or not the purchase closes. The inspection is yours. You hire the inspector and decide what to do with the report. The appraisal is your lender’s, confirming the property is worth what you agreed to pay, though federal rules entitle you to a copy.
Specialty inspections stack on top, radon, sewer scope, well and septic, each a few hundred dollars, and cheaper than the repair it might reveal. Our guide to preparing to buy covers what to bank first.
Earnest money and where your cash to close comes from
Earnest money typically runs 1% – 2% of the purchase price, $3,000 – $6,000 on a $300,000 home, and isn’t an extra cost, because it’s credited toward your down payment or closing costs at the table. It only becomes a loss if you walk away outside your contingencies.
Retirement accounts are the most misunderstood source for the rest of your cash. The IRS caps a 401(k) participant loan at the greater of $10,000 or 50% of your vested balance, and never above $50,000, generally repayable within five years, longer if the loan buys your main home.1 A traditional or Roth IRA allows up to $10,000 in your lifetime for a first-time home purchase without the 10% early-distribution penalty, though ordinary income tax may still apply. Read how to finance a home purchase with a 401(k) before you touch retirement money.
Lender fees you can shop for, and the ones you can’t
Your lender must deliver a Loan Estimate within three business days of your application, and before that they can’t charge you anything but a credit report fee. Section C of that form lists the services you’re allowed to shop for, and your lender must hand you a written list of providers. Title work, pest inspection, and survey live there. Shopping them is one of the few places you can move real money.
The benefits of mortgage pre-qualification include a realistic cash-to-close estimate before you fall for a house, and our home buying process guide shows where each fee lands.
What hidden costs land on closing day?
Closing costs generally total 2% – 5% of the purchase price, and the line items buyers forget aren’t lender fees at all, prepaid insurance, escrow reserves, title insurance, transfer taxes, and prorations. Your Closing Disclosure must reach you at least three business days before closing, a legally protected window to compare it against your Loan Estimate.
Prepaids and escrow reserves
Prepaids and escrow reserves are the most misread part of the form. Prepaids are costs paid in advance, commonly your first year of homeowners insurance and the interest before your first payment. Escrow reserves are the starting balance your servicer uses to pay taxes and insurance later; most lenders collect about two months’ worth up front, the maximum cushion federal rules allow.
Neither is an extra fee. Both are money you’d owe anyway, billed early. But they sit inside the closing-cost total, which is why an online calculator’s estimate so often lands thousands below the real number. The CFPB’s Loan Estimate explainer for decoding fees walks the form section by section, and our guide to how to budget for closing costs turns it into a savings target.
Title insurance, transfer taxes, and prorations
Your lender will require a lender’s title insurance policy, and it protects the lender’s loan, not your equity. An owner’s policy, covering claims that predate your purchase, is optional and usually offered at a discounted simultaneous rate at closing, one of the few one-time costs worth paying voluntarily.
Transfer taxes and recording fees are set by state and county, so they’re invisible in national averages and unavoidable once you pick a county. Prorations then split shared expenses at the closing date, property taxes, HOA dues, sometimes fuel oil, either crediting you or costing you several hundred dollars. Seller credits run the other way, cutting your cash to close, subject to program caps. Our breakdown of closing costs and what to expect as a buyer lists them line by line, and first-time home buyers should read it twice.
What are the ongoing costs of owning the home?
Ongoing costs are everything except principal and interest, taxes, insurance, mortgage insurance, HOA dues, utilities, and a maintenance reserve of 1% – 2% of home value a year, or $250 – $500 a month on a $300,000 home. This bucket decides whether a house is affordable, and it’s the one a mortgage calculator ignores.
The four parts of a PITI payment
PITI stands for principal, interest, taxes, and insurance, the four parts of a typical escrowed payment. Principal and interest are fixed on a fixed-rate loan; taxes and insurance are not. Your servicer runs an escrow analysis at least once a year, so when the tax bill or insurance premium changes, your payment changes with it. That’s the year-two payment jump: the escrow account simply got re-priced against real bills.
Mortgage insurance and when it stops
Mortgage insurance protects the lender and follows different rules by loan type. On a conventional loan with private mortgage insurance, federal law lets you request cancellation once the balance reaches 80% of the home’s original value, and your servicer must terminate it automatically at 78% if you’re current on payments.
FHA works differently, and the difference is expensive. On FHA loans with terms longer than 15 years, the annual mortgage insurance premium runs 11 years when the original loan-to-value is 90% or less, and for the full mortgage term when it’s above 90%. Putting less than 10% down on an FHA loan means the premium stays until you refinance or sell.2 Because Align is a broker, we price conventional and FHA side by side so you can see what that costs over the years you plan to stay.
HOA dues, utilities, and flood insurance
HOA dues aren’t escrowed into your payment, but every lender counts them against your qualifying ratios, and an association can levy a special assessment no monthly budget anticipated. Ask for its budget, reserve study, and assessment history before you’re under contract.
Utilities deserve the same scrutiny: ask for 12 months of bills rather than an average, because a drafty 1950s ranch and a new build of the same square footage are not the same house. And in a FEMA-designated Special Flood Hazard Area, federal law requires flood insurance on any mortgage made by a federally regulated or insured lender, which is nearly every mortgage, conventional loans included, a cost tied to the parcel, not your loan.
The 1% – 2% maintenance rule
Set aside 1% – 2% of the home’s value each year for maintenance and repairs, $3,000 – $6,000 on a $300,000 home, or $250 – $500 a month. Older homes, larger lots, and Michigan winters push you toward the top of that range.
The rule works because major systems fail on a schedule you don’t control, and the inspection report you paid $300 – $500 for shows where the roof, furnace, and water heater sit on that horizon, so read it as a budget document. Angi cost data for common home repairs checks local pricing, and our guide to how to budget for home maintenance turns the percentage into a monthly transfer.
What a $300,000 home costs, start to finish
Cash to close on a $300,000 Waterford purchase runs a down payment of $9,000 – $60,000 depending on program, plus $6,000 – $15,000 in closing costs at 2% – 5%, minus your earnest money credit and any seller concession.3 Monthly: principal and interest, escrowed taxes and insurance, any mortgage insurance, HOA dues, utilities, and a $250 – $500 maintenance transfer into an untouched account.
Run that total against your take-home pay, not your gross income. A house that’s comfortable on paper and tight in practice is almost always one where the buyer priced the mortgage and ignored the other five lines. A Realtor.com breakdown of hidden home-buying costs covers the same categories from the agent’s side.
What Michigan buyers should know
Michigan resets your property tax bill the year after you buy, which makes the seller’s current bill one of the most misleading numbers in the transaction. Under Proposal A, a transfer of ownership uncaps the taxable value: for the calendar year following the transfer, taxable value becomes the property’s state equalized value, one half of its true cash value.4
- Budget on half of market value, not the seller’s bill: A long-time owner’s taxable value may sit far below market because increases were capped while they owned it. On a $300,000 purchase, plan for a taxable value near $150,000 after uncapping. Michigan assessors may not simply adopt your purchase price as the new assessed value, so your figure comes from the assessor’s valuation, not the sale.
- File your Principal Residence Exemption: A PRE exempts your principal residence from the local school operating millage, up to 18 mills on $150,000 of taxable value, up to $2,700 a year, the largest tax lever most Michigan buyers control. File Form 2368 with your assessor by the June 1 or November 1 deadline.
- Expect transfer tax on the settlement statement: Michigan’s state real estate transfer tax is $3.75 per $500 of value ($7.50 per $1,000) and the seller is liable for it, plus a county transfer tax of $0.55 per $500 ($1.10 per $1,000). The rate in all 83 Michigan counties, because none has the 2,000,000 residents state law would require before a higher county rate could apply. On a $300,000 sale that’s roughly $2,580, a seller cost that shapes what they’ll accept.
Price your taxes from the uncapped number before writing an offer. Our explainer on how property tax assessments work covers assessment notices and the appeal calendar.
How Align helps you get ready
There is no such thing as calling too early. Samantha would rather see your numbers months before you shop than the week you find a house, because that is when there is still time to fix what matters.
When you are ready, one application goes to multiple wholesale lenders. A 2024 Polygon Research analysis of federal mortgage data found broker borrowers paid about $10,662 less over the life of a $400,000 loan than borrowers at nonbank retail lenders.
FAQ: Hidden costs in a home purchase
Here are answers to common questions about hidden costs in a home purchase.
What hidden costs come with buying a house?
Beyond the down payment, expect closing costs of 2% to 5% of the price, inspection and appraisal fees of several hundred dollars each, and prepaid items like taxes and insurance funding your escrow account. After closing, property taxes, homeowners insurance, HOA fees, utilities, and maintenance continue every month. Budgeting all of these upfront prevents payment shock later, and dues deserve their own line, as our guide to homeowner association fees explains.
How much should I budget for home maintenance each year?
A widely used rule of thumb is 1% to 2% of your home’s value annually, $3,000 to $6,000 on a $300,000 home. Older homes, larger lots, and harsh climates push toward the high end. Even in quiet years, banking that amount builds a reserve for the inevitable roof replacement, furnace failure, or water heater swap, which our guide to the cost of home repairs breaks down by system.
What costs surprise first-time home buyers the most?
The most common surprises are cash due at closing beyond the down payment, escrow prepaids for taxes and insurance, immediate move-in costs like locks and utility deposits, and the first major repair bill. Property tax changes after purchase catch many buyers off guard too, since a transfer of ownership can reset the taxable value the following year. Working through preparing to buy before you shop keeps those numbers from arriving all at once.
How can I estimate the true monthly cost of a home before buying?
Add the full PITI payment, principal, interest, taxes, and insurance, then layer on HOA dues, average utilities (ask the seller for 12 months of bills), and one-twelfth of an annual maintenance budget of 1% to 2% of home value. Comparing that total against your take-home pay gives a far more honest affordability picture than the mortgage payment alone. Our Home Buying guide walks the rest of the sequence from offer to keys.
The bottom line on hidden home-buying costs
The hidden costs of a home purchase are predictable once you stack them in one place. Closing costs generally run 2% – 5% of the purchase price on top of a 3% – 20% down payment, including prepaid insurance and roughly two months of escrow reserves that online calculators leave out. Recurring costs, taxes, insurance, mortgage insurance, HOA dues, utilities, belong to the property rather than the loan, and they move your payment whenever escrow is re-analyzed. Then reserve 1% – 2% of home value a year for maintenance. On a $300,000 home, that’s $6,000 – $15,000 at closing and $250 – $500 a month for upkeep.
If you’re ready to see what a specific house will really cost you, talk to Align Lending, we’ll shop your scenario across our lender network and walk your Loan Estimate line by line so nothing surprises you at the closing table. Call 248-506-5727 or start online today.
Footnotes:
1. This article is for informational purposes only and is not intended to provide legal, financial, or tax advice. Retirement plan loan and early-distribution rules are set by the IRS and by your plan document, and the tax treatment of any withdrawal depends on your circumstances. Consult a qualified tax professional before using retirement funds for a home purchase. Return to text.
2. Align Lending is not acting on behalf of or at the direction of FHA or HUD. FHA mortgage insurance premium amounts and durations are set by HUD and are subject to change. Return to text.
3. Example figures are hypothetical and for educational purposes only; they do not constitute an advertisement of credit terms or a rate quote under federal or state lending laws. Your down payment, closing costs, escrow amounts, and monthly payment depend on your application, the property, the loan program, and market conditions. Return to text.
4. Michigan property tax administration is governed by state law and administered by local assessors, and assessment practice, millage rates, and exemption rules are subject to change. Your actual taxable value is determined by your local assessor, not by your purchase price. This article is not tax advice, consult a qualified tax professional or your local assessor about your situation. Return to text.
Sources: closing costs of 2% – 5% of the purchase price, down payments of 3% – 20%, earnest money deposits of 1% – 2% of the purchase price, and escrow reserves of about two months collected at closing, Freddie Mac (My Home by Freddie Mac, “Understanding homebuying costs”). Loan Estimate delivered within three business days of application, the credit report fee as the only fee chargeable beforehand, section C services you can shop for and the written list of providers, Closing Disclosure delivered at least three business days before closing, escrow account analysis and the two-month cushion limit, and the difference between lender’s and owner’s title insurance, Consumer Financial Protection Bureau (Regulation X § 1024.17 and Regulation Z §§ 1026.19, 1026.37–38). PMI cancellation at 80% and automatic termination at 78% of original value, Homeowners Protection Act of 1998 as described by the CFPB. FHA annual mortgage insurance premium durations of 11 years at 90% LTV or less and the mortgage term above 90% LTV on terms greater than 15 years, U.S. Department of Housing and Urban Development (FHA mortgage insurance premium structure for forward mortgage loans). 401(k) participant loans limited to the greater of $10,000 or 50% of the vested account balance, capped at $50,000, with a general five-year repayment term extendable for a principal-residence purchase, and the $10,000 lifetime IRA first-time homebuyer exception to the 10% additional tax on early distributions, Internal Revenue Service (Retirement Topics, Loans; Publication 590-B). Mandatory flood insurance purchase for buildings in a Special Flood Hazard Area securing a loan made by a federally regulated or insured lender, FEMA National Flood Insurance Program (42 U.S.C. § 4012a). Michigan taxable value uncapping to state equalized value in the calendar year following a transfer of ownership, state equalized value equal to one half of true cash value, and the prohibition on assessors adopting the sale price as the new assessment, Michigan Department of Treasury and State Tax Commission (Transfer of Ownership Guidelines; MCL 211.27a). Principal Residence Exemption of up to 18 mills of local school operating tax and Form 2368 deadlines of June 1 and November 1, Michigan Department of Treasury. State real estate transfer tax of $3.75 per $500 of value with the seller liable for the tax, Michigan Department of Treasury (State Real Estate Transfer Tax); county real estate transfer tax of $0.55 per $500 in counties under 2,000,000 population, the rate applicable in every Michigan county, since none reaches that threshold, MCL 207.504. Home inspection and appraisal fee ranges are industry-standard market ranges, not government-set fees; your Loan Estimate shows the appraisal fee your lender will actually charge.
This article is for informational purposes only and is not intended to provide legal, financial, or tax advice. Property tax treatment, exemption eligibility, and the tax consequences of using retirement funds depend on your individual circumstances, consult a qualified tax professional. Program terms and figures shown are illustrative, are not a rate quote or an offer of credit, and are subject to change. Align Lending is an independent Michigan mortgage broker, NMLS #2041154.
Related resources
12-minute read
How to budget for closing costs on a home purchase
Learn how to budget for closing costs, which typically run 2% to 5% of the purchase price, and see which fees you can shop, negotiate or reduce.
12-minute read
The importance of mortgage preapproval: What it does and why sellers ask for it
Learn why mortgage preapproval matters, how long it lasts, what it does to your credit and how it strengthens an offer before you start house hunting.
12-minute read
How to save for a down payment on a house
Discover proven strategies to save for a down payment, from automated savings to assistance programs that can put homeownership within reach sooner.
