
Mortgage servicing: What your loan servicer actually does
Mortgage servicing is the day-to-day administration of your loan after closing: collecting your payment, managing your escrow account, paying your property taxes and homeowners insurance, and working out options if you fall behind. Federal rules make your servicer reanalyze your escrow account at least once every computation year, and if your servicing is ever sold, notify you at least 15 days before the transfer takes effect.
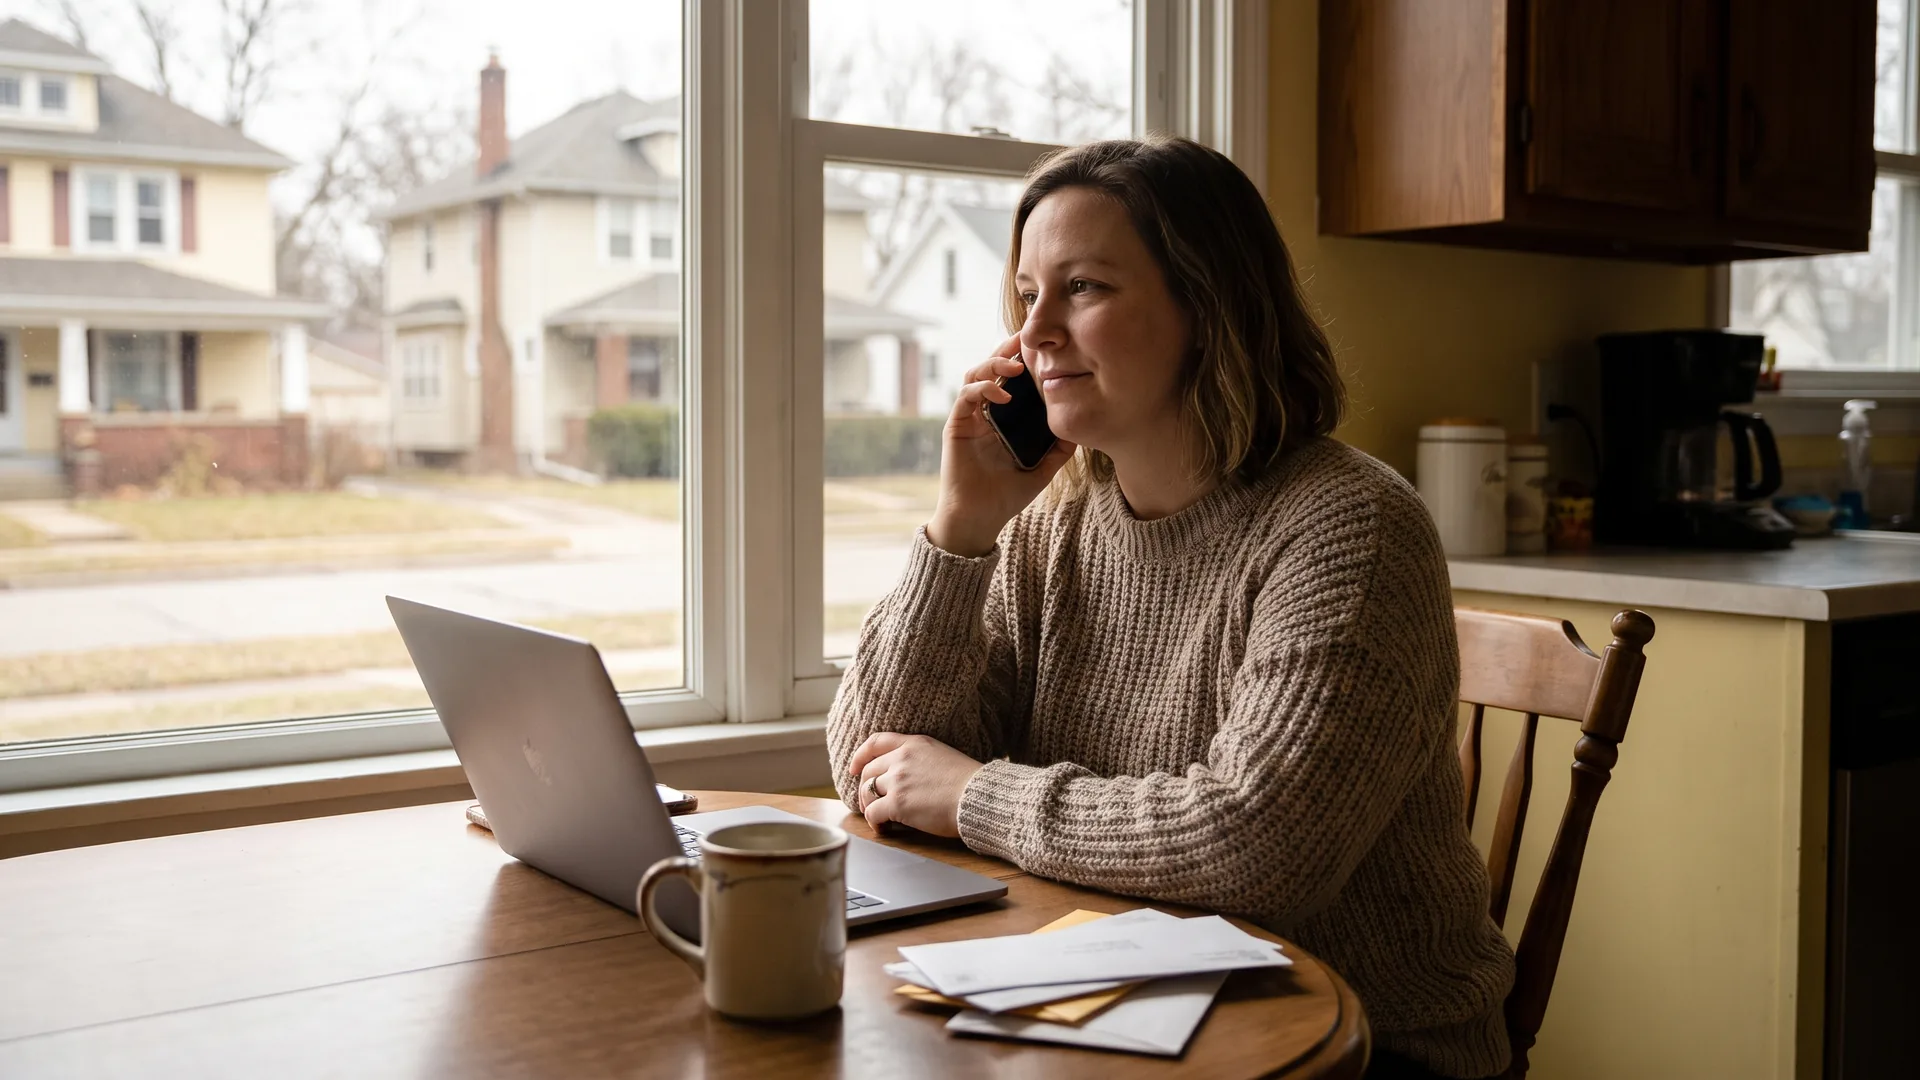
Your servicer may be the lender that originated your loan or a separate company that bought the servicing rights. Either way the sale doesn’t touch your rate, balance or payoff date, the transfer notice has to say so in writing, and for 60 days afterward, a payment you sent to the old servicer on time can’t be treated as late.
Learn what mortgage servicing covers, who the players are, what happens when your loan transfers, and what your servicer owes you when money gets tight. Earlier in the process? Start with our Mortgage Basics guide.
Key takeaways:
- Servicing is your loan’s entire afterlife: One company handles payments, escrow, insurance and hardship options, and owes you a statement every billing cycle plus an escrow statement within 30 days of the end of each computation year.
- A transfer changes the letterhead, not the loan: Notice comes at least 15 days before the effective date and within 15 days after, and for 60 days afterward an on-time payment to the old servicer can’t draw a late fee.
- Call before you miss a payment, not after: Your servicer must attempt live contact by day 36 of delinquency and send written notice by day 45, and on covered loans can’t make a first foreclosure filing until the loan is more than 120 days delinquent.
What is mortgage servicing?
Mortgage servicing is the ongoing administration of a mortgage after it closes: receiving the scheduled payments, holding and disbursing escrow funds for taxes and insurance, and passing principal and interest along to whoever owns the loan. That is close to the federal definition itself.
A servicer is the party responsible for that work, including the lender, when the lender keeps the file. Originating and servicing are different businesses, which is why the company that walked you to the closing table isn’t necessarily the one collecting from you for 30 years. Payment posting, escrow, statements, payoff quotes and hardship options all live with the servicer, including one duty worth naming now: an accurate payoff statement within seven business days of a written request.
All of it sits downstream of origination. For how the file gets built, see the Mortgage Loan Process; our Payments, Escrow & Servicing hub collects the rest of the post-closing topics.
Who are the key players in mortgage servicing?
Four parties touch your loan after closing. Only one answers your phone.
| Party | What they do | When you deal with them |
|---|---|---|
| Your servicer | Collects payments, runs escrow, sends statements, issues payoff quotes, handles hardship requests. | Every month, and whenever you have a question. |
| The loan owner or investor | Holds the note and sets the menu of loss mitigation options the servicer may offer. | Almost never directly. Request their identity in writing; you get an answer within 10 business days. |
| The insurer or guarantor | Backs the loan against default, FHA on an FHA-insured loan, a private insurer on a conventional loan under 20% down. | Indirectly, through the premium inside your payment. |
| You, the homeowner | Make the payment, keep hazard insurance in force, put errors in writing. | Constantly. You’re the only one watching all of it. |
Your broker is a fifth, temporary party: Align Lending places your loan but does not service it, and who services it afterward is the loan owner’s decision. Why work with Align Lending covers that hand-off.
What does your mortgage servicer do every month?
Payment processing
Your servicer must credit a periodic payment (principal, interest and escrow together) as of the date it’s received, not the date it gets keyed in. Send less than a full one and it may sit in suspense until enough accumulates. Late fees can’t be pyramided either: none charged solely because you didn’t pay an earlier late fee.
Escrow account management
An escrow account is money your servicer holds from each payment to cover property taxes and homeowners insurance, then pays those bills before a penalty deadline. The CFPB’s overview of how escrow accounts are managed by servicers is worth five minutes if it’s new to you.
The math is bounded by rule. Say a Waterford home carries $4,800 a year in property taxes and $1,200 in insurance, $6,000 of annual disbursements, about $500 a month. Beyond what’s needed to pay those bills on time, your servicer may hold a cushion of no more than one-sixth of the annual total: $1,000 here, roughly two months.1 Then it gets trued up:
- The initial statement: Delivered at settlement or within 45 calendar days of it.
- The annual analysis: At the completion of each escrow computation year, the servicer reanalyzes the account and delivers an annual escrow account statement within 30 days.
- Surplus and shortage: A surplus of $50 or more must be refunded within 30 days of the analysis; a shortage may generally be repaid in installments over at least 12 months.
That’s why your payment can change on a fixed-rate loan: the rate never moved, but your tax bill did. Our deep dives on mortgage escrow accounts and what escrow is and how it works read an analysis line by line. Your servicer also files IRS Form 1098 and sends you a copy when it takes in $600 or more of mortgage interest from you.2
Insurance oversight and PMI removal
Servicers track whether your hazard insurance is in force, because the collateral is uninsured the moment it lapses. If yours lapses the servicer can buy a policy and bill you, but only on a clock: written notice at least 45 days before the charge, then a reminder no sooner than 30 days after the first and at least 15 days before it. Send proof of coverage inside that window and the charge doesn’t happen.
Your servicer also cancels PMI on a conventional loan, and the Homeowners Protection Act creates three distinct paths that each require you to be current. You may request cancellation on the date the balance is scheduled to fall to 80% of original value, in writing, with a good payment history, a certification of no junior liens, and evidence the value holds if asked. Your servicer must automatically terminate PMI, no request needed, at 78% of original value. If neither happens, PMI ends the month after the midpoint of your amortization schedule. All three measure against original value, not today’s market value; see mortgage insurance.
What happens when your mortgage servicing is transferred?
Servicing rights get bought and sold constantly, and a transfer is an administrative event, not a change to your loan. The federal notice must state that it does not affect any term or condition of the mortgage loan other than terms directly related to servicing. Three numbers define the handoff:
- 15 days before: Your old servicer must give notice not less than 15 days before the effective date.
- 15 days after: Your new servicer must give notice not more than 15 days after it. Both carry the effective date and a collect-call or toll-free number.
- 60 days of protection: During the 60 days beginning on the effective date, a payment the old servicer receives on or before its due date may not be treated as late for any purpose.
When the letters arrive, confirm the two effective dates match and keep proof of anything you send. The 60-day rule protects you, but you’ll need the record to invoke it.
What should you do in the first weeks after a servicing transfer?
Three chores are yours. First, move any automatic payment. According to the CFPB’s page on what happens when your servicer changes, if you pay through your bank’s or credit union’s bill pay, you need to tell the bank to send payments to the new servicer.
Second, check that the letters match each other before you send money anywhere new. If you have no statement handy, the CFPB’s guide to the difference between a lender and a servicer lists the MERS Servicer Identification System, toll-free at (888) 679-6377, as another way to look up who services your loan.
Third, compare the new servicer’s first statement with the old servicer’s last one: principal, escrow balance and next due date. Put any difference in writing. The role of escrow in home buying explains how that escrow balance was first funded.
What happens if you fall behind on your mortgage?
Your servicer must reach out before you do. It has to establish or make good-faith efforts to establish live contact with a delinquent borrower no later than the 36th day of delinquency, and deliver a written early intervention notice no later than the 45th. A notice naming loss mitigation options that may be available and where to find homeownership counseling.
Once you ask for help, the timeline tightens. Your servicer must acknowledge a loss mitigation application in writing within five business days and say whether it’s complete. File a complete one more than 37 days before a scheduled foreclosure sale and it has 30 days to evaluate you for every option available on your loan, and it can’t move for a judgment or order of sale, or conduct the sale, while that evaluation is pending. The usual options, in rough escalation order:
- Repayment plan: Your regular payment plus a slice of the past-due amount until you’re current.
- Forbearance: Payments pause or shrink temporarily. This is the one people misread. The CFPB is explicit that forbearance does not erase or decrease the amount you owe. You pay the difference back later, so get the exit terms in writing at the start. See the CFPB’s explanation of forbearance.
- Deferral: On some loan types the missed amount moves to the back of the loan, due at payoff, sale or refinance.
- Loan modification: A permanent change to rate, term or balance to make the payment sustainable.
- Short sale or deed-in-lieu: Exits when keeping the home isn’t realistic.
FHA-insured loans layer HUD’s servicing requirements on top of these rules; HUD’s Single Family Servicing operation works with FHA homeowners and their lenders to avoid foreclosure, including tools such as the partial claim.3 Our walkthrough of mortgage forbearance covers the exit paths.
One backstop worth memorizing: on covered loans a servicer generally can’t make the first notice or filing for foreclosure unless the loan is more than 120 days delinquent. That’s runway, not a grace period. And don’t pay anyone for help. As the CFPB puts it, the help you need is free from your servicer or a HUD-approved housing counseling agency.
How long can forbearance last on a Fannie Mae or Freddie Mac loan?
If Fannie Mae owns your loan, its servicing guide limits forbearance. Per the Fannie Mae Servicing Guide, section D2-3.2-01, Forbearance Plan (dated April 8, 2026):
- Three months at a time: Forbearance plan terms must be in increments of no greater than three months.
- A 12-month ceiling: Extensions may not exceed a cumulative term of 12 months measured from the start date of the first plan.
- 36 months combined: When the servicer first offers forbearance and a repayment plan together, the combined period must not exceed 36 months.
- A call before it ends: The servicer must begin trying to contact you no later than 30 days before any forbearance term expires.
Plan the exit. Freddie Mac’s homeowner guide to forbearance and your options (last reviewed December 29, 2025) says forbearance postpones payments rather than forgiving them, and describes three ways out: reinstatement, where you get a defined period of time to bring the loan current; a payment deferral, which moves the outstanding payments into an account that does not accrue additional interest; and a modification, a written agreement that permanently changes one or more loan terms. After a disaster, Freddie Mac’s disaster relief FAQ (last reviewed August 17, 2026) says your mortgage company may first offer a 90-day forbearance plan and may extend it up to 12 months.
Planning a new loan later? Read how to refinance a mortgage in forbearance and refinancing after a loan modification.
How often do servicers use forbearance and loan modifications?
According to the Federal Housing Finance Agency’s Foreclosure Prevention and Refinance Report for the second quarter of 2026, Fannie Mae and Freddie Mac servicers completed 48,439 foreclosure prevention actions that quarter, part of 7,425,684 since September 2008, and 37,283 of their loans were still in forbearance at the end of June 2026. For what those numbers mean for a homeowner in forbearance, and how delinquency compares across FHA, VA and conventional loans, see mortgage forbearance: what it means for homeowners.
What extra options do FHA, VA and USDA loans give your servicer?
FHA loans
HUD’s Mortgagee Letter 2025-12, dated April 15, 2025, says the COVID-19 Recovery Loss Mitigation Options expired on September 30, 2025, and that the letter’s remaining provisions took effect on October 1, 2025. Under it, an FHA borrower is limited to one permanent loss mitigation option every 24 months instead of every 18 months.
VA loans
According to the VA’s page for homeowners who have trouble making payments (last updated September 23, 2026), the options include special forbearance, a repayment plan, a VA traditional loan modification, a 30-year modification, the VA partial claim and a 40-year modification. The American Legion reported on June 24, 2026 that the partial claim program is authorized by the VA Home Loan Reform Act: servicers place qualified veterans on a three-month trial payment plan, the servicer then pays the overdue amount to bring the loan current, and VA pays that same amount to the servicer, which must repay VA when the loan is paid in full, refinanced or the property is sold.
USDA guaranteed loans
USDA’s Rural Housing Service issued a final rule published in the Federal Register on August 15, 2024, effective February 11, 2025. Per the rule, traditional servicing options include repayment agreements, special forbearance, loan modifications and Mortgage Recovery Advances, with advances capped at a cumulative 30% of the unpaid principal balance as of the initial default. Its streamline servicing options must cut principal and interest by at least 10% and open once the borrower is at least 90 days past due.
What happens when you send extra principal to your servicer?
Fannie Mae’s Selling Guide calls extra principal a principal curtailment: funds applied to reduce the unpaid principal balance. For a loan Fannie Mae owns, the Fannie Mae Servicing Guide, section C-1.2-01 (dated November 13, 2024) says the servicer must immediately accept and apply an additional principal payment. If, after a substantial curtailment, you ask for the balance to be re-amortized so the payment drops, the servicer must complete an Agreement for Modification, Re-Amortization or Extension, and it may not treat that re-amortization as a modification when deciding whether you can get a modification later. That re-amortization is what most people call a recast; see mortgage recasting.
Before you send a large amount, read your note for a prepayment penalty. The CFPB defines a prepayment penalty as a fee that some lenders charge if you pay off all or part of your mortgage early. For example, before sending a bonus as a lump sum, ask in writing whether a penalty applies. If one does apply, IRS Publication 936 (2025) says you can deduct that penalty as home mortgage interest, provided the penalty is not for a specific service performed or cost incurred in connection with the loan, and that the year’s mortgage interest statement should be sent to you by January 31 of the following year.
To see how an extra payment changes the payoff date, run your own numbers in the mortgage payoff calculator, and read amortization schedules for how each payment splits between interest and principal. See also mortgage interest deductions.
What rules do mortgage servicers have to follow?
Two rulebooks, both administered by the Consumer Financial Protection Bureau. Regulation X, at 12 CFR Part 1024, implements RESPA and governs escrow accounts, transfer notices, early intervention and loss mitigation. Regulation Z, at 12 CFR Part 1026, implements the Truth in Lending Act and covers payment crediting, periodic statements and payoff quotes. Both belong to the CFPB, not HUD, which people still assume because RESPA started there. Read the federal mortgage servicing regulations at the source.
Two tools in those rules start clocks a phone call does not:
- Notice of error: A written assertion that your servicer got something wrong. Acknowledged within five business days, answered within seven business days on a payoff-balance error and 30 business days for most others.
- Request for information: A written request for account information, same five-day acknowledgment. The loan owner’s identity is due within 10 business days; most other requests within 30.
What Michigan homeowners should know
Michigan’s property tax calendar is what makes escrow here feel different from a single-bill state. Most Michigan communities bill property taxes twice a year, a summer installment and a winter installment, collected by your city or township treasurer, with due dates set locally. That changes your escrow account’s rhythm, not the rules governing it.
- Two disbursements, one cushion cap: Your servicer writes two tax checks a year instead of one, but the cushion is still capped at one-sixth of annual escrow disbursements, about two months’ worth.
- Your analysis follows the tax calendar: The computation year is a 12-month cycle and the annual statement is due within 30 days of its completion, so a summer bill larger than projected gets corrected there, not immediately.
- Surpluses and shortages both have rules: A surplus of $50 or more must be refunded within 30 days of the analysis, and a shortage can generally be spread over at least 12 monthly payments. If your servicer demands a lump sum, ask for installments in writing.
New construction and recently sold Michigan homes drift the most: the first full assessment can land well above the projection that funded your closing. That gap is a shortage, not an error. Our breakdown of mortgage escrow accounts shows how to read the worksheet.
How do Michigan tax due dates shape your escrow payments?
A servicer must pay escrowed taxes in a timely manner as they become due, per 12 U.S.C. 2605(g). In Michigan, state law and your treasurer set those dates.
- Summer taxes: Under MCL 211.44a, summer taxes a community is authorized to collect become a lien on the property and are due from the owner on July 1.
- The February penalty: MCL 211.44 allows a late penalty charge equal to 3% of the tax on taxes paid after February 14 and before they are returned as delinquent.
- March 1: Under MCL 211.44a, taxes and interest still unpaid before March 1 are returned as delinquent on March 1. The Waterford row below shows unpaid taxes going to the county treasurer from that date.
Two Oakland County townships, for example:
| Township | Summer bill without interest | Winter bill without penalty | After that |
|---|---|---|---|
| Waterford | July 1 through September 14 | December 1 through February 14 | February 15 to 28 adds a 4% penalty and fee; from March 1, unpaid taxes go to the Oakland County Treasurer |
| Bloomfield | July 1, 2026 through September 14, 2026 | December 1, 2026 through February 16, 2027 | As of March 2, 2027, unpaid taxes are owed to the Oakland County Treasurer with interest and penalty |
Sources: Charter Township of Waterford, Late Taxes; Charter Township of Bloomfield, Payment Options.
A penalty caused by a late escrow payment is a notice-of-error item. Estimate a bill with the Michigan property tax calculator, and see how property tax assessments work.
What happens if a servicer forecloses on a Michigan home?
Michigan allows foreclosure outside court, by advertisement. The Michigan State Housing Development Authority’s stages of foreclosure page puts the start at day 121: if attempts to resolve the default fail and no hardship application has been received, the foreclosure process begins. Until the sheriff’s sale, a homeowner may still submit a loss mitigation application.
- Who may foreclose: MCL 600.3204 allows foreclosure by advertisement only after a default, and if the party foreclosing is not the original mortgagee, a record chain of title must exist before the date of sale.
- Notice: Under MCL 600.3208, the sale notice is published for 4 successive weeks, at least once a week, in a newspaper published in the county, and a copy is posted on the property within 15 days after the first publication.
- Redemption: MCL 600.3240 sets the time to redeem after the sale for a home of up to 4 units: 6 months if the amount claimed due at the notice date is more than 66-2/3% of the original debt, 1 month if the property is abandoned, and otherwise 1 year from the date of the sale.
Late payments are rising in Michigan. FHFA reported that 21,274 of the 1,020,607 Fannie Mae and Freddie Mac loans in Michigan were delinquent on June 30, 2026, and that the state’s delinquent count rose 12.3% during the second quarter.
Per MSHDA’s foreclosure help page, the first step is to contact a HUD-certified housing counselor through MSHDA’s Housing Education Program, and HUD’s avoiding foreclosure page lists (800) 569-4287 to find a counselor. Buyers can read the foreclosure process.
How Align sets up your payment
Align places your loan with a wholesale lender, and that lender or its servicer collects your payments after closing. Before then, Samantha builds your escrow on your real tax bill, not the seller's.
The year after a Michigan home sells, its taxable value resets to half of the assessor's market value, so the seller's tax bill is not your tax bill. She quotes your number on the high side on purpose.
Get a homebuying budget review
Sources: Michigan Treasury, transfer of ownership and uncapping.
FAQ: Mortgage servicing
Here are answers to common questions about mortgage servicing.
What is the difference between a lender and a mortgage servicer?
The lender underwrote and funded your loan. The servicer manages it afterward: taking your payment, running escrow, sending statements, handling hardship requests. They’re often the same company at first, but servicing rights are frequently sold, which is why the name on your statement can change while your loan terms do not. See how the roles split in the mortgage loan process.
How do I find out who services my mortgage?
Check your monthly statement or payment coupon, which lists the servicer’s name and contact information. If servicing transferred recently, you should have notices from both servicers showing the effective date. To learn who owns the loan, send a written request for information; your servicer must respond within 10 business days. Our payments, escrow and servicing hub explains the notices.
What should I do if I can’t make my mortgage payment?
Contact your servicer before you miss a payment, not after. Submit a loss mitigation application and it must be acknowledged within five business days and, if complete and filed more than 37 days before a foreclosure sale, evaluated within 30 days for the options on your loan. Document every call, and know foreclosure-avoidance help is free. Start with mortgage forbearance.
Can I choose or change my mortgage servicer?
Generally no. Servicing rights belong to the loan’s owner and are sold without your consent, so you can’t switch servicers on an existing loan. Refinancing gives you a new loan and possibly a new servicer. If your servicer is mishandling the account, send a notice of error in writing. Align places loans and does not service them; why work with Align Lending explains who does.
Can my mortgage servicer report a late payment while I am disputing it?
Not for 60 days, if you put the dispute in a qualified written request. Under 12 U.S.C. 2605(e)(3), during the 60 days after a servicer receives a written request about a dispute over your payments, it may not give information about an overdue payment tied to that dispute to any credit bureau. Keep a copy, and keep paying anything you do not dispute.
Can a servicer charge late fees during a forbearance plan?
On a Freddie Mac loan in disaster forbearance, no. Freddie Mac’s disaster relief FAQ (last reviewed August 17, 2026) says that during a forbearance period your mortgage company may not assess late fees. Other loan owners set their own terms, so ask your servicer to confirm in writing that no late fees will post and how skipped payments will be repaid.
How do I check that a mortgage servicer is licensed in Michigan?
Search the state’s list. MCL 445.1652 says a person may not act as a mortgage servicer in Michigan without a license or registration under the Mortgage Brokers, Lenders, and Servicers Licensing Act. The Department of Insurance and Financial Services keeps a licensee and registrant locator and answers questions at 877-999-6442, Monday through Friday, 8 a.m. to 5 p.m.
How can I tell if a mortgage relief offer is a scam?
Watch for the requests no servicer makes. The CFPB’s guide to foreclosure relief scams lists telling you to stop making payments, charging up-front fees, asking you to pay someone other than your servicer, and promising a forensic audit of your loan. If you see one, stop and call your servicer at the number on your statement.
The bottom line on mortgage servicing
Mortgage servicing is everything that happens to your loan after closing: payments, escrow, insurance, tax reporting, PMI removal and hardship options. Your servicer reanalyzes escrow each computation year, refunds a surplus of $50 or more within 30 days, and holds a cushion no larger than one-sixth of annual disbursements. A transfer brings 15 days’ notice before and 60 days of late-fee protection after, and changes no loan term. Fall behind and you should expect live contact by day 36, written notice by day 45, and no first foreclosure filing until the loan is more than 120 days delinquent.
If you’re ready to find out whether your current loan is still the right one, talk to Align Lending. We’ll shop your scenario across our lender network and put the payment and escrow numbers in front of you side by side. Call 248-506-5727 or start online.
Footnotes:
1. Example figures in this article are hypothetical and for educational purposes only; they do not constitute an advertisement of credit terms or a rate quote under federal or state lending laws. Your escrow payment, cushion and analysis results depend on your property’s actual tax and insurance bills, your loan program, and your servicer’s computation year. Return to text.
2. This is general information, not tax advice. Whether mortgage interest or property taxes benefit you depends on your individual circumstances and on whether you itemize. Consult a qualified tax professional about your situation. Return to text.
3. Align Lending is not acting on behalf of or at the direction of FHA or HUD. FHA servicing and loss mitigation requirements are set by HUD and are subject to change; availability of any option depends on your loan and your servicer. Return to text.
Sources: definitions of “servicing” and “servicer,” 12 CFR § 1024.2(b). Servicing transfer notices not less than 15 days before and not more than 15 days after the effective date, required notice contents including the statement that transfer does not affect any term or condition of the loan, and the 60-day period during which a payment received by the transferor on or before the due date may not be treated as late, 12 CFR § 1024.33. Escrow cushion of no more than one-sixth of estimated total annual disbursements, annual escrow account analysis, surplus of $50 or more refunded within 30 days, shortage repayable over at least 12 months, initial escrow account statement at settlement or within 45 calendar days, and annual escrow account statement within 30 days of the end of the computation year, 12 CFR § 1024.17. Timely escrow disbursements and return of the escrow balance within 20 business days of payoff, 12 CFR § 1024.34. Notice of error acknowledgment within 5 business days and response within 7 or 30 business days, 12 CFR § 1024.35. Request for information acknowledgment within 5 business days, owner or assignee identity within 10 business days, other requests within 30 business days, 12 CFR § 1024.36. Force-placed insurance notice at least 45 days before assessing a charge, with a reminder no earlier than 30 days after the first notice and at least 15 days before the charge, 12 CFR § 1024.37. Live contact no later than the 36th day of delinquency and written early intervention notice no later than the 45th day, 12 CFR § 1024.39. Acknowledgment of a loss mitigation application within 5 business days, evaluation of a complete application within 30 days when received more than 37 days before a foreclosure sale, the prohibition on moving for judgment or conducting a sale while that evaluation is pending, and no first notice or filing for foreclosure until the loan is more than 120 days delinquent, 12 CFR § 1024.41. Crediting periodic payments as of the date of receipt, the prohibition on pyramiding late fees, and payoff statements within seven business days of a written request, 12 CFR § 1026.36(c). Periodic statements for each billing cycle, 12 CFR § 1026.41. Forbearance does not erase or decrease the amount owed; mortgage relief options including refinance, loan modification, repayment plan, forbearance, short sale and deed-in-lieu; and foreclosure-avoidance help available at no cost from your servicer or a HUD-approved housing counseling agency, Consumer Financial Protection Bureau. PMI cancellation on borrower request at 80% of original value, automatic termination at 78% of original value, and final termination the month after the midpoint of the amortization schedule, each requiring the borrower to be current, Homeowners Protection Act as explained by the Consumer Financial Protection Bureau. Form 1098 filing for $600 or more of mortgage interest received from an individual in the course of a trade or business, IRS Instructions for Form 1098. HUD Single Family Servicing works with FHA homeowners and their lenders to avoid foreclosure and administers the partial claim, U.S. Department of Housing and Urban Development.
This article is for informational purposes only and is not intended to provide legal, financial, or tax advice. Servicing rules, escrow calculations, program options and property tax practices change and vary by loan program, servicer and Michigan community; confirm your figures with your servicer’s escrow analysis and statements and consult a qualified professional about your situation. Figures shown are illustrative, are not a rate quote or an offer of credit, and are subject to change. Align Lending is an independent Michigan mortgage broker, NMLS #2041154.
Sources
Every outside source this guide links to, in the order it appears. How we choose and check sources
- How escrow accounts are managed by servicersConsumer Financial Protection Bureau
- What happens when your servicer changesConsumer Financial Protection Bureau
- The difference between a lender and a servicerConsumer Financial Protection Bureau
- The CFPB’s explanation of forbearanceConsumer Financial Protection Bureau
- D2-3.2-01, Forbearance Planservicing-guide.fanniemae.com
- Forbearance and your optionsFreddie Mac
- Disaster relief FAQFreddie Mac
- Foreclosure Prevention and Refinance Report for the second quarter of 2026Federal Housing Finance Agency
- Mortgagee Letter 2025-12U.S. Department of Housing and Urban Development
- Have trouble making paymentsU.S. Department of Veterans Affairs
- Reported on June 24, 2026legion.org
- Final rule published in the Federal Registergovinfo.gov
- Selling GuideFannie Mae Selling Guide
- Fannie Mae Servicing Guide, section C-1.2-01servicing-guide.fanniemae.com
- Prepayment penaltyConsumer Financial Protection Bureau
- Publication 936Internal Revenue Service
- Federal mortgage servicing regulationsConsumer Financial Protection Bureau
- 12 U.S.C. 2605(g)law.cornell.edu
- MCL 211.44aMichigan Legislature
- MCL 211.44Michigan Legislature
- Charter Township of Waterford, Late Taxeswaterfordmi.gov
- Charter Township of Bloomfield, Payment Optionsbloomfieldtwpmi.gov
- Stages of foreclosureState of Michigan
- MCL 600.3204Michigan Legislature
- MCL 600.3208Michigan Legislature
- MCL 600.3240Michigan Legislature
- Foreclosure helpState of Michigan
- Avoiding foreclosureU.S. Department of Housing and Urban Development
- MCL 445.1652Michigan Legislature
- Licensee and registrant locatorState of Michigan
- Foreclosure relief scamsConsumer Financial Protection Bureau
- 12 CFR § 1024.33Consumer Financial Protection Bureau
- 12 CFR § 1024.17Consumer Financial Protection Bureau
- 12 CFR § 1024.35Consumer Financial Protection Bureau
- 12 CFR § 1024.36Consumer Financial Protection Bureau
- 12 CFR § 1024.39Consumer Financial Protection Bureau
- 12 CFR § 1024.41Consumer Financial Protection Bureau
- 12 CFR § 1026.36(c)Consumer Financial Protection Bureau
- 12 CFR § 1026.41Consumer Financial Protection Bureau
Related resources
20-minute read
Understanding Mortgage Escrow Accounts
Learn how a mortgage escrow account collects property taxes and homeowners insurance each month, why lenders require it and how annual analysis works.
20-minute read
Understanding Mortgage Insurance
Compare mortgage insurance types (PMI, FHA MIP, USDA fees and the VA funding fee) see what each costs and when you can drop it from your payment.
20-minute read
Mortgage forbearance: What it means for homeowners
Learn how mortgage forbearance pauses payments during hardship, how long plans typically last, and the four ways servicers let you repay what you missed.
