
Flipping houses: The risks and rewards investors should weigh
Flipping a house means buying below market, renovating on a deadline, and reselling, usually inside six months. The most expensive thing new flippers get wrong is the tax: the IRS generally treats someone who buys and resells houses as a dealer holding inventory, so the profit is ordinary income taxed at rates topping out at 37% for 2026, plus self-employment tax of 15.3% (12.4% for Social Security on net earnings up to the $184,500 wage base for 2026 and 2.9% for Medicare with no cap at all), not the 0%, 15% or 20% long-term capital gains rates investors assume.
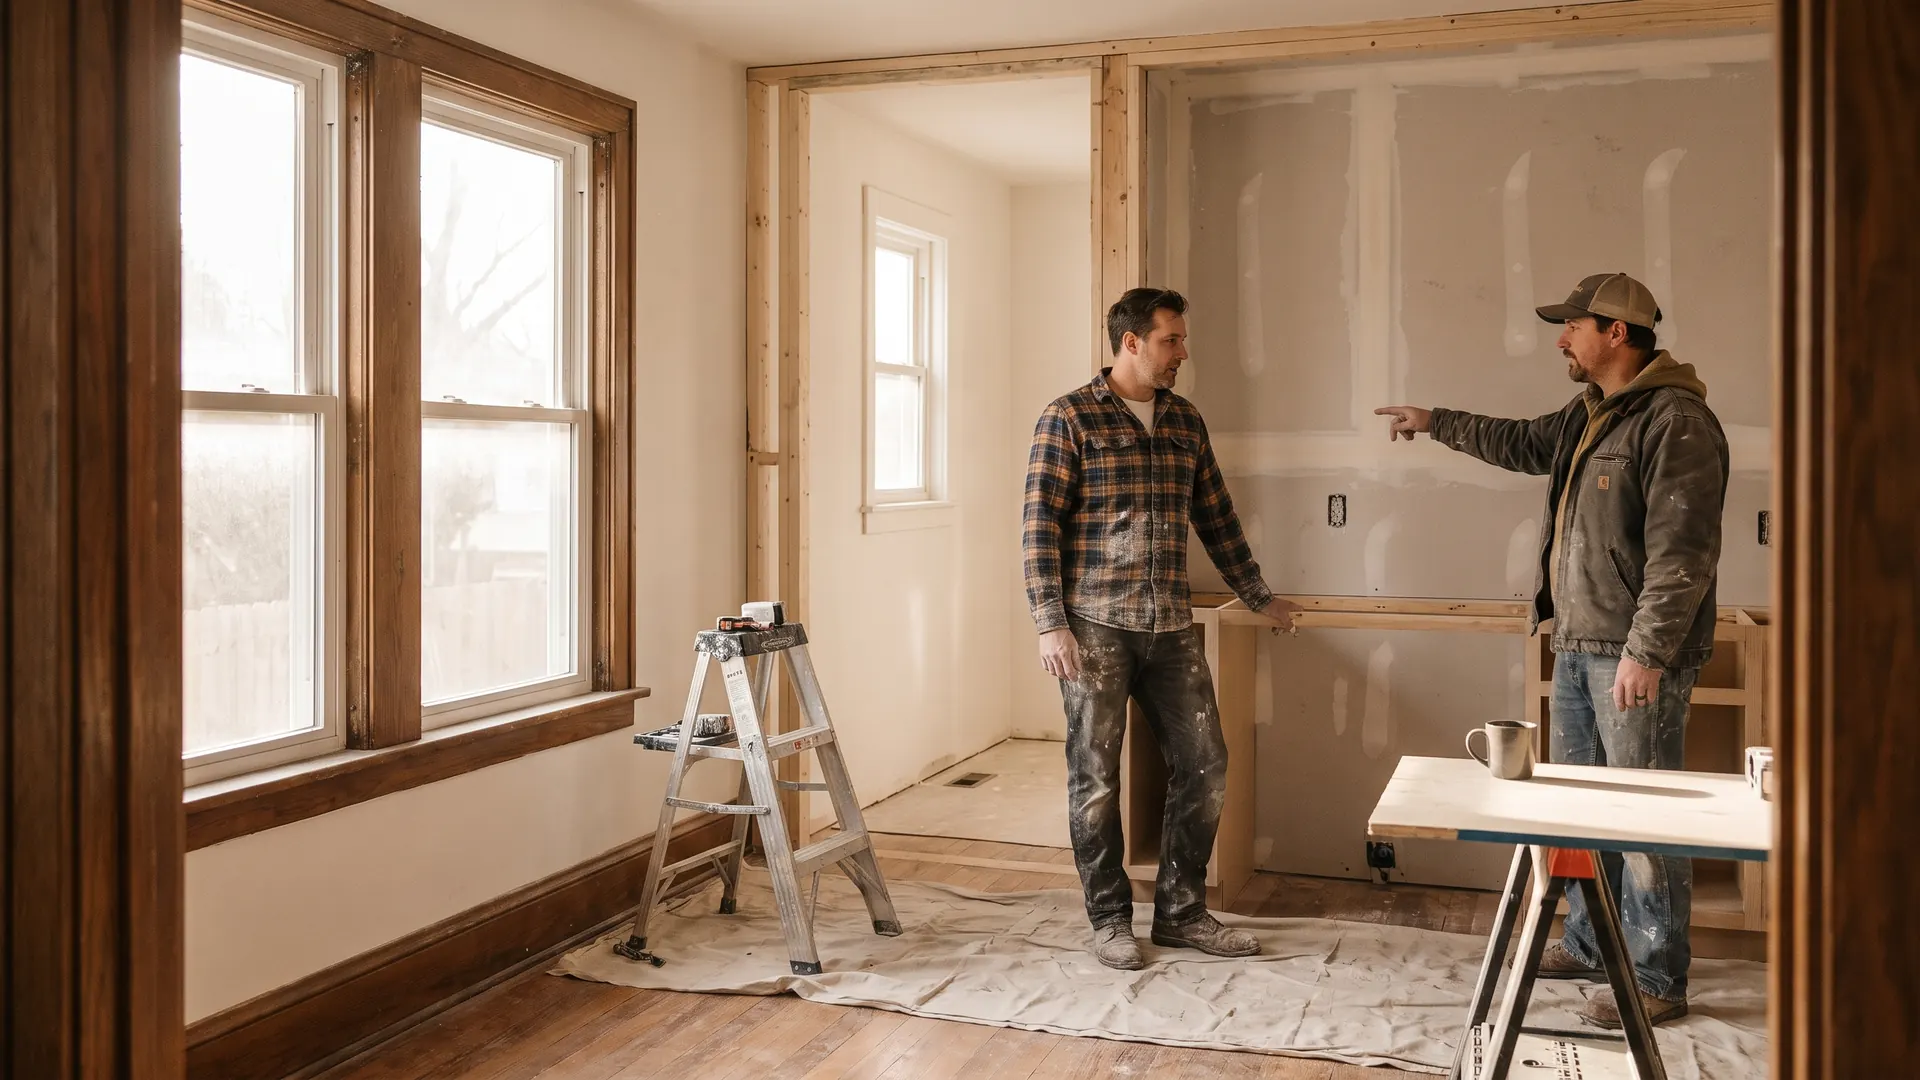
The reward is a concentrated return earned in months instead of decades, on a project you control. The risk is that a rehab overrun, a longer hold and a soft resale all eat the same margin.
Learn how the risks and rewards of flipping houses stack up: the 70% rule, holding costs, financing a short hold, and the tax treatment. If your plan is to renovate and keep the property, that’s a different business.
This article is general information about the house-flipping business model, not tax, legal or investment advice. How a flip is taxed depends on your facts, your entity and your state. Consult a CPA before you buy, and a Michigan real estate attorney on contract and permit questions. Align Lending is an independent mortgage broker, not a CPA firm, broker-dealer or investment adviser.
Key takeaways:
- The 70% rule caps what you can pay: Multiply after-repair value by 0.70 and subtract estimated repairs, so a $260,000 after-repair value with $45,000 of work supports a maximum offer near $137,000. It’s a rule of thumb, not a law, and the 30% haircut exists to absorb overruns.
- Holding costs run every month whether you sell or not: In the illustration below they total about $2,050 a month, or $12,300 across a six-month hold, so a three-month delay costs roughly $6,150 straight off the profit.
- Flip profits are ordinary income, not capital gain: Property held mainly for sale to customers isn’t a capital asset, so profits face ordinary rates up to 37% for 2026 plus self-employment tax of 15.3%, with no 1031 exchange and no depreciation.
What does flipping a house actually involve?
Flipping is a short-hold resale business, not buy-and-hold investing, and the typical project runs three to six months from closing to closing. The property is inventory, and the profit is the spread between what you put in and what a buyer pays.
That distinction drives your financing, your tax return and your risk. A landlord earns rent for years and can wait out a bad market; a flipper earns once and can’t. Our real estate investing guide compares the strategies and investing basics covers the vocabulary.
- Acquisition: The profit is made here, not at the finish line. See buying distressed properties.
- Scope: A written scope of work with line-item pricing, not a wish list. Change orders after demolition cost money and days.
- Exit: A retail sale at the after-repair value your comparables supported. If nobody pays that number, you had a hope, not a deal.
Our post on the advantages of buying a fixer-upper covers the upside. This article covers what it costs when the upside doesn’t arrive.
How do you price a flip using the 70% rule?
Multiply the after-repair value by 0.70, subtract estimated repairs, and the result is the most you should pay. The 70% rule is an industry rule of thumb, not a legal or lending standard, and it guarantees nothing. It forces a 30% cushion between all-in cost and expected sale price.
Say comparables support a $260,000 after-repair value and a contractor prices the work at $45,000.1
- Take 70% of ARV: $260,000 × 0.70 = $182,000.
- Subtract repairs: $182,000 − $45,000 = $137,000 maximum offer.
- Stress the ARV, not the offer: If comparables support $247,000 instead, the formula gives $127,900, so a 5% ARV error moves your maximum offer by $9,100.
Both inputs are estimates. After-repair value comes from closed sales of finished, comparable homes within a half-mile in the last 90 days, the same evidence an appraiser uses, which is why the home appraisal process matters here. The repair number comes from a bid, not a guess. Verifying both is real estate due diligence.
| Line | Amount |
|---|---|
| Resale price (after-repair value) | $260,000 |
| Purchase price | − $137,000 |
| Renovation budget | − $45,000 |
| Holding costs, six months | − $12,300 |
| Buy-side closing costs | − $3,000 |
| Sale-side costs at 7% (agent compensation, transfer tax, title, concessions) | − $18,200 |
| Pre-tax profit | $44,500 |
Keep that $44,500 in mind, because every risk below is measured against it.
What do holding costs really take out of a flip?
About $2,050 a month on a mid-priced project, or $12,300 across a six-month hold, and the cost accrues whether the house is finished, listed or sitting. Holding costs are the quietest line on the pro forma and the one that turns a slow project into a break-even one.2
| Holding cost | Per month (illustrative) | Six months |
|---|---|---|
| Loan interest carry | $1,375 | $8,250 |
| Property taxes | $250 | $1,500 |
| Vacant-property and builder’s risk insurance | $150 | $900 |
| Utilities (heat, power, water) | $175 | $1,050 |
| Lawn, snow removal, security | $100 | $600 |
| Total | $2,050 | $12,300 |
- Insurance isn’t the policy you know: A vacant home under renovation generally needs vacant-property or builder’s risk coverage; a standard homeowners policy can exclude losses on an unoccupied dwelling.
- Every extra month is $2,050: A permit that runs three weeks long, a countertop backorder and a failed inspection aren’t disasters alone. Together they’re a month.
Scheduling controls this line, not hustle: order long-lead items before demolition, sequence trades so nobody waits, and pull home renovation permits first.
How do you finance a short hold?
Not with a standard 30-year mortgage. Conventional and government purchase loans are built for someone who intends to own the home, so flippers use short-term, asset-based money that underwrites the deal more than the borrower. It is priced with origination points and rates above conventional pricing, and it comes due on a fixed date whether or not the house has sold.
- Hard money and private lending: Sized against the property rather than debt ratios, often advancing a percentage of purchase plus a rehab holdback drawn in stages. Expect points up front and a term measured in months.
- Bridge financing: Short-term borrowing against equity you already hold, used to fund an acquisition before another sale closes. See bridge loans.
- Renovation mortgages are for keepers, not flippers: HUD describes both versions of its 203(k) rehabilitation program as available to homebuyers and homeowners, the Limited version financing up to $75,000 of work and the Standard version requiring at least $5,000. See our guides to renovation loans.
One rule shapes your exit, and new flippers miss it. Under HUD’s property-flipping restriction, a property resold 90 days or fewer after the seller acquired it isn’t eligible for an FHA-insured mortgage, subject to listed exceptions.3 Between 91 and 180 days, the lender must get a second appraisal from a different appraiser if the resale price is 100% or more above what the seller paid, and it can’t be charged to the buyer. A fast flip is therefore invisible to a large slice of first-time buyers.
How are flip profits taxed?
As ordinary income, not capital gain, and that is the largest single swing factor in a flipper’s after-tax return.4 IRS Publication 544 lists property held mainly for sale to customers among the assets that aren’t capital assets. When the IRS treats you as a dealer holding inventory, four things follow at once.
- Ordinary rates, not 0%, 15% or 20%: Long-term capital gain treatment requires holding an asset more than one year and the asset being a capital asset. Dealer property fails the second test even after two years. The top 2026 ordinary rate is 37%.
- Self-employment tax on top: Net earnings from a trade or business carry self-employment tax of 15.3%, made up of 12.4% Social Security up to the $184,500 wage base for 2026 and 2.9% Medicare with no cap, plus an additional 0.9% above the statutory thresholds.
- No 1031 exchange: Section 1031 has applied only to real property since 2017 and expressly excludes property held primarily for sale, so you can’t roll a flip forward tax-deferred. See 1031 exchange rules and benefits for the strategy buy-and-hold owners do get.
- No depreciation: IRS Publication 946 is explicit that inventory cannot be depreciated, so the write-offs behind most tax benefits of real estate investing aren’t available.
Living in the house doesn’t automatically convert the sale either: the Section 121 exclusion of up to $250,000 of gain, or $500,000 on a joint return, requires owning and using the home as your main home for at least 24 of the 60 months before the sale. See capital gains tax exemptions.
Apply an ordinary rate to the worked example and a $44,500 pre-tax profit at a 24% marginal rate leaves about $33,800, and that is before self-employment tax and state tax. Whether you’re a dealer at all turns on facts a professional must review. Talk to a CPA before your first flip, not after your first return.
Flipping houses: rewards vs. risks
Every reward in flipping has a matching risk on the same variable.
| Dimension | The reward | The risk |
|---|---|---|
| Speed | Capital returns in months, not decades. | Every month past plan costs about $2,050, and the exit depends on one buyer at your number. |
| Return concentration | One well-bought project can produce a five-figure margin. | A 5% miss on a $260,000 ARV is $13,000, roughly 29% of the profit. |
| Control | You set the scope, finish level and schedule. | You carry contractor, permit, inspection and weather risk, undiversified. |
| Tax treatment | Project costs offset the sale in the year you close. | Ordinary income with self-employment tax. No 1031, no long-term capital gains rate, no depreciation. |
| Financing | Short-term lenders underwrite the deal, so a strong project funds quickly. | Points and higher rates make time expensive, and the note matures on a date. |
| Market exposure | A short hold limits your exposure to a downturn. | It also leaves no time to wait one out. |
How do flips actually lose money?
Rarely from one catastrophe and almost always from three ordinary misses on one project. Take the $44,500 pre-tax profit above: the rehab runs 15% over at $6,750, the timeline slips three months at $6,150 of holding cost, and the house sells 5% under the projected after-repair value for $13,000 less. Total damage: $25,900, or 58% of the profit. Nothing there is a disaster. A fourth miss turns it into a loss.
- Stale or wrong comparables: The most expensive error, because it corrupts the offer, the loan and the exit at once. Use closed sales of finished homes.
- Repair estimates from a walkthrough: Roof, sewer lateral, electrical service, foundation and old wiring break budgets. Price findings from a full inspection, starting with a home inspection checklist.
- Over-improving for the block: Quartz and a wine fridge don’t raise a $260,000 ceiling. Match finish level to the comparables that set your ARV.
- Skipped permits: Cheap and fast until closing, when the buyer’s lender or municipality finds them.
- Undercapitalization: Running out mid-project forces a distressed sale of a half-finished house. Hold a contingency you don’t touch.
How do market conditions change the flip math?
They change the one assumption a flipper can’t control: the resale price six months out. U.S. house prices rose 2.1% between the second quarter of 2025 and the second quarter of 2026 per the FHFA House Price Index released August 25, 2026, while the Consumer Price Index for All Urban Consumers rose 3.4% for the 12 months ending July 2026. Nominal growth below inflation means national prices slipped in inflation-adjusted terms, which matters to anyone counting on appreciation to cover a mistake.
- Underwrite to today’s comparables, never a forecast: Appreciation during a six-month hold is a bonus, not a line item. Past performance does not predict future results.
- Use a local series, not a national one: The FHFA House Price Index publishes state and metro data; a national number says nothing about a ZIP code.
- Have a plan B before you need one: If resale stalls, the alternatives are renting, refinancing into longer-term debt, or cutting price early. Model the refinance case with how to refinance an investment property before you close.
A price cut in week three costs less than the same cut in month five, because by then you’ve paid four more months of carry.
What Michigan flippers should know
Three Michigan costs land on a flip that a first spreadsheet often misses.
- No principal residence exemption: A flip is not the home you live in, so the exemption from up to 18 mills of school operating tax does not apply, and the bills during your hold carry the full rate. Our guide to Michigan taxable value explains the exemption.
- The uncapping can land during your hold: The year after a Michigan home sells, its taxable value resets to half of the assessor’s market value, so the seller’s tax bill is not your tax bill. On a hold that crosses the new year, the higher bill can be yours before you resell. The Michigan property tax calculator estimates it on a specific address.
- Transfer tax at resale: Michigan charges $3.75 for every $500 of the price for the state, plus $0.55 per $500 for the county, and by custom the seller pays it at closing. On a flip you are the seller, so budget it with the resale costs. Our guide to the Michigan transfer tax covers who pays and the exemptions.
How Align finances investors
Samantha looks at the property's numbers before the loan's, and she says so plainly: "I don't love a deal that only works when nothing goes wrong."
Align places DSCR loans, which qualify on the rent the property brings in rather than your tax returns, as well as conventional investment loans, through multiple wholesale lenders.
FAQ: Flipping houses
Here are answers to common questions about flipping houses.
How much money do I need to start flipping houses?
More than a down payment. Plan for the renovation budget plus a 15% to 20% contingency, six months of holding costs, and closing costs on both the buy and the sell. Short-term lenders finance a percentage of purchase plus a staged rehab holdback, but require meaningful cash in the deal. Undercapitalization is the most common reason first flips fail. Compare structures in financing home renovations.
Is flipping houses profitable in the current market?
It depends on your acquisition price more than on the market. Margins compress when purchase prices stay high while resale demand cools, and higher financing costs raise the carry on every month of delay. Flippers who succeed in slow markets buy well below market and refuse to underwrite appreciation.
What are the biggest mistakes new flippers make?
Underestimating repair costs and overestimating after-repair value from stale comparables, in that order. Close behind: over-improving beyond what the neighborhood supports, hiring contractors without verifying license and insurance, and skipping permits that surface at resale. Then timeline, since every extra month adds carrying costs. See avoiding common home inspection pitfalls.
How are house flipping profits taxed?
As ordinary income in most cases. The IRS generally treats a flipper as a dealer holding property mainly for sale to customers, which isn’t a capital asset, so long-term capital gains rates don’t apply no matter how long you hold. Self-employment tax may apply on top, and a flip doesn’t qualify for a 1031 exchange.
The bottom line on flipping houses
Flipping rewards discipline at the purchase and punishes everything else. Price with the 70% rule (after-repair value times 0.70 minus repairs, so a $260,000 ARV with $45,000 of work supports about $137,000), then budget roughly $2,050 a month, or $12,300 over six months, in holding costs. The profit is ordinary income taxed at rates up to 37% for 2026 plus self-employment tax of 15.3%, with no 1031 exchange and no depreciation. Three ordinary misses took 58% of the profit above.
If the numbers point toward keeping the house as a rental, talk to Align Lending about the long-term financing: DSCR loans and conventional investment property loans to buy or refinance a rental. We’ll shop your scenario across our lender network and show you the options side by side. Call 248-506-5727 or start online. Take tax questions to a CPA and contract, permit and title questions to a Michigan real estate attorney.
Footnotes:
1. Example figures are hypothetical and for educational purposes only; they do not constitute an advertisement of credit terms or a rate quote under federal or state lending laws. The $260,000 after-repair value, $45,000 renovation budget, $137,000 maximum offer, $3,000 buy-side closing costs, 7% sale-side cost assumption and resulting $44,500 pre-tax profit are Align Lending calculations shown to demonstrate how the 70% rule and a flip pro forma are constructed. The 70% rule is an industry rule of thumb, not a legal, lending or appraisal standard, and it does not guarantee a profit. Agent compensation is negotiable and is not set by any lender, association or law. Actual acquisition prices, renovation costs, transaction costs and sale prices depend on the property, the contractor, the municipality and market conditions. Return to text.
2. Example figures are hypothetical and for educational purposes only; they do not constitute an advertisement of credit terms or a rate quote under federal or state lending laws. The $1,375 monthly interest carry, $250 property tax, $150 insurance, $175 utility and $100 maintenance figures, and the resulting $2,050 monthly and $12,300 six-month totals, are Align Lending illustrations of how holding costs accumulate. They are not a quote, are not drawn from any specific loan program, and do not reflect any particular interest rate. Your actual carrying costs depend on your loan terms, your county’s millage, your insurer and the property. Return to text.
3. Align Lending is not acting on behalf of or at the direction of FHA or HUD. FHA property-flipping restrictions, the exceptions to the 90-day resale rule, the second-appraisal threshold for resales between 91 and 180 days, and the owner-of-record requirement are set by HUD and are subject to change. Confirm current requirements with an FHA-approved lender before relying on them to plan an exit. Return to text.
4. This is general information, not tax advice. Whether the IRS treats you as a dealer holding property primarily for sale to customers, whether self-employment tax applies, which costs must be capitalized rather than deducted, and how an LLC, partnership or S corporation election changes the result all depend on your individual facts and are decided on the totality of the circumstances. Tax rates, wage bases and thresholds change annually. Consult a qualified tax professional or CPA about your situation before you buy. Return to text.
Sources: Long-term capital gain requires holding the asset more than one year, and the applicable rates for most individuals are 0%, 15% and 20%, Internal Revenue Service Topic No. 409, Capital Gains and Losses. Property held mainly for sale to customers is not a capital asset, and property held primarily for sale is excluded from like-kind exchange treatment, which has applied only to real property since 2017, with a 45-day identification period and a 180-day exchange period, Internal Revenue Service Publication 544, Sales and Other Dispositions of Assets. Inventory (property held primarily for sale to customers in the ordinary course of business) cannot be depreciated, and land cannot be depreciated, Internal Revenue Service Publication 946, How To Depreciate Property. Self-employment tax rate of 15.3%, consisting of 12.4% for Social Security and 2.9% for Medicare, Internal Revenue Service Topic No. 554, Self-Employment Tax. Social Security wage base of $184,500 for 2026 and Additional Medicare Tax of 0.9%, Internal Revenue Service Topic No. 751, Social Security and Medicare Withholding Rates, and Social Security Administration 2026 cost-of-living adjustment fact sheet. Top individual income tax rate of 37% for tax year 2026, applying above $640,600 for single filers and $768,700 for married couples filing jointly, Internal Revenue Service, “IRS releases tax inflation adjustments for tax year 2026,” Rev. Proc. 2025-32. Section 121 exclusion of up to $250,000 of gain, or $500,000 on a joint return, with the 24-month ownership and use tests within the five years before the sale and the two-year frequency limit, Internal Revenue Service Topic No. 701. Ineligibility for FHA mortgage insurance where resale occurs 90 days or fewer after the seller’s acquisition, the second-appraisal requirement for resales between 91 and 180 days where the resale price is 100% or more above the seller’s acquisition price, the prohibition on charging that second appraisal to the buyer, and the owner-of-record requirement, 24 CFR 203.37a and U.S. Department of Housing and Urban Development, FHA Single Family Housing Policy Handbook 4000.1. Limited 203(k) financing of up to $75,000 of repairs and Standard 203(k) minimum rehabilitation of $5,000, both described as available to homebuyers and homeowners, U.S. Department of Housing and Urban Development, 203(k) Rehabilitation Mortgage Insurance Program. U.S. house prices up 2.1% between 2025 Q2 and 2026 Q2 and up 0.3% quarter over quarter, with prices rising in 46 states and the District of Columbia, Federal Housing Finance Agency House Price Index news release, August 25, 2026. Consumer Price Index for All Urban Consumers up 3.4% for the 12 months ending July 2026, after 3.5% for the 12 months ending June 2026, U.S. Bureau of Labor Statistics, Consumer Price Index Summary, July 2026.
This article is for informational purposes only and is not intended to provide legal, financial, investment or tax advice, and it is not an offer or solicitation to buy or sell any security. Tax rules, agency program requirements and market data change and vary by property, entity and locality; confirm current figures with your loan officer, confirm tax treatment and entity structure with a qualified tax professional or CPA, and confirm contract, permit and title obligations with a Michigan real estate attorney. Figures shown are illustrative, are not a rate quote or an offer of credit, and do not constitute an advertisement of credit terms. Past performance of any housing index does not predict future results. Align Lending is an independent Michigan mortgage broker, NMLS #2041154. Align Lending is not a broker-dealer, investment adviser, securities issuer, property manager or accounting firm.
Related resources
13-minute read
Buying a home as an investment property: A step-by-step guide
Learn how buying a home as an investment property works, from 15%+ down payments and financing options to ROI math, so your first rental starts profitable.
13-minute read
Real estate appreciation: How property values grow and why it matters
Learn how real estate appreciation works, why U.S. homes have averaged roughly 3% to 5% a year, and how forced appreciation can add to returns.
12-minute read
1031 exchanges: Rules, deadlines and benefits for investors
Learn how a 1031 exchange defers capital gains tax, why the 45-day and 180-day deadlines are absolute, and which properties qualify as like-kind.
