
A guide to real estate due diligence for investors
This article is general information, not legal, tax or investment advice. Contract deadlines, disclosure duties, zoning, environmental liability and tax treatment depend on your property and your contract. Consult a Michigan real estate attorney and a qualified tax professional.
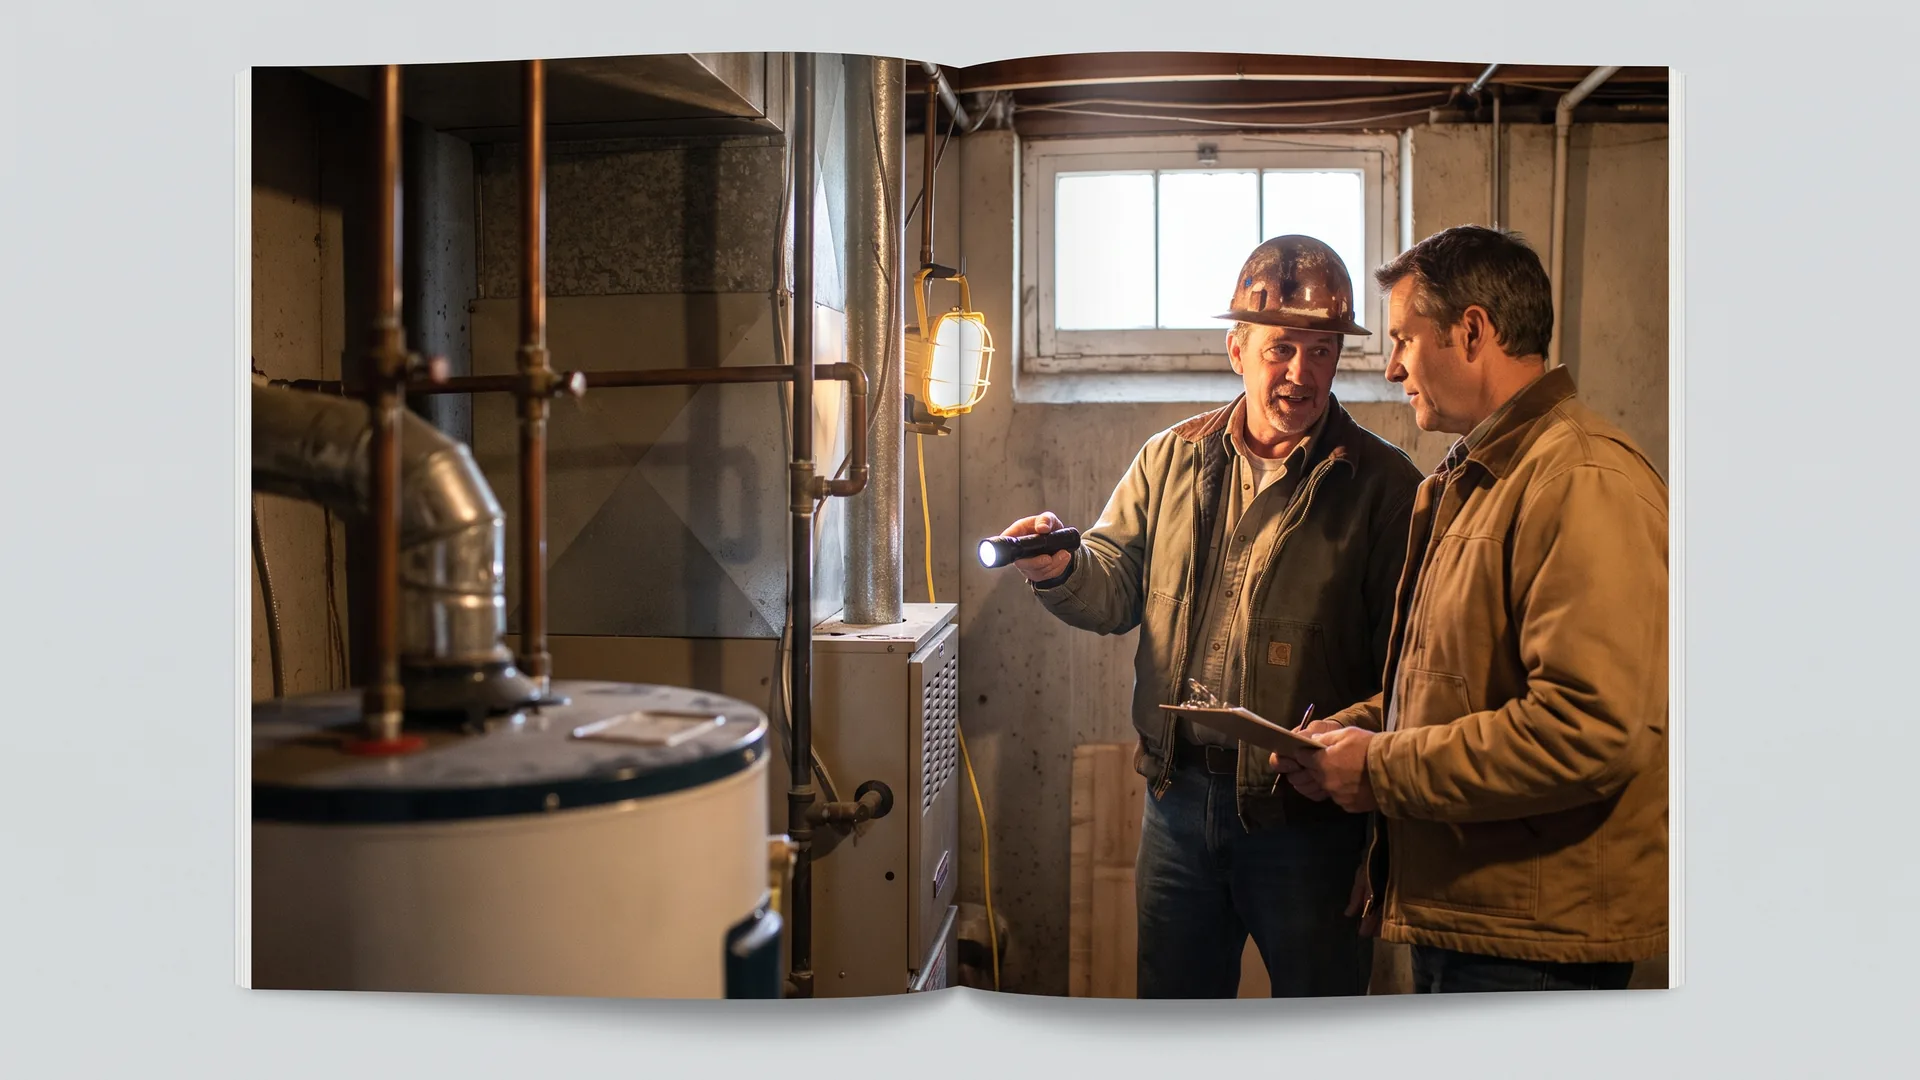
Real estate due diligence is the verification window between an accepted offer and closing, and its job is narrow: confirm in writing what the seller told you to get that offer signed. Two of its deadlines come from federal rule rather than your contract. The seller of pre-1978 target housing must give the buyer a 10-day period, before the buyer is obligated under the contract, to conduct a lead-based paint risk assessment or inspection unless both parties agree in writing to a different window, and a Phase I environmental site assessment only supports the federal landowner liability protections if it was conducted or updated within one year before you take title.1
Everything else runs on the clock your purchase agreement sets. Across Align Lending’s broker network, investment purchase agreements typically allow 30 to 60 days of due diligence from execution, compressing to 10 to 21 days on a small residential rental.
Learn what belongs on the checklist, who performs each item, and how to turn findings into a price reduction or a clean exit. Still choosing a property rather than verifying one? Start with our Real Estate Investing guide.
Key takeaways:
- Due diligence runs on a contractual clock: Investment purchase agreements commonly allow 30 to 60 days from execution, and the inspection, title objection and financing deadlines inside that window drive the schedule.
- Four tracks, any one of which can end the deal: Title and survey, physical condition, leases and financials, and environmental and zoning each justify renegotiating or terminating, and the federal lead-paint testing period alone is 10 days.
- Budget 0.5% to 1% of purchase price: Inspection, survey, environmental and attorney costs are non-refundable even if you walk, and a documented condition report is your strongest tool for winning a credit.
What is real estate due diligence, and when does the clock start?
Real estate due diligence is the contractual investigation period in which a buyer verifies a property’s legal, physical, financial and regulatory condition before the purchase becomes unconditional. The clock starts at the effective date of the purchase agreement, the day the last party signs, not the day the seller’s documents arrive. A seller who takes nine days to produce a rent roll has spent a quarter of a 35-day window.
Due diligence is not deal evaluation. Evaluation is what you did before you offered: comparing markets, running numbers, deciding the property was worth pursuing. If that is still ahead of you, work through how to evaluate a real estate market for investment, how to find undervalued properties and cap rates in real estate first, alongside our Investing Basics hub. Due diligence asks a different question: was it true?
What does a full due diligence checklist cover?
Four tracks, one calendar. Here is the master checklist, who does the work, and how much of your window each item consumes.2
| Track | What you verify | Who performs it | Typical timing |
|---|---|---|---|
| Title | Ownership, liens, easements, restrictions, access | Title company; attorney reviews | Order day 1; commitment in 5 to 15 days |
| Survey | Boundaries, encroachments, setbacks, easement locations | Licensed land surveyor | Order day 1; 2 to 4 weeks |
| Physical condition | Structure, roof, mechanicals, plumbing, life safety | Inspector or engineer, plus trade specialists | Week 1; report in 2 to 5 days |
| Leases and tenants | Lease terms, concessions, options, deposits, estoppels | You and your attorney; tenants sign | Weeks 2 to 4 |
| Financials | Rent roll against deposits, trailing 12 months, taxes, utilities | You, with a CPA on anything material | Weeks 2 to 4 |
| Environmental | Phase I, radon, lead paint, asbestos, tanks, flood zone | Environmental professional; certified testers | Order week 1; Phase I in 2 to 3 weeks |
| Zoning and permits | Legality of current use, open permits, violations | You or your attorney, at the municipality | Weeks 1 to 3 |
Order the long-lead items (title, survey, Phase I) in the first three days. What blows a deadline is ordered late, not performed slowly.
How do you verify title and survey?
Read the title commitment’s exceptions, not its cover page. Schedule A says what is insured, the requirements schedule says what must clear before closing, and the exceptions schedule says what the policy will not cover. That last list is where the money is: an easement crossing the only place a parking lot could go shows up there and nowhere else.
- Buy the owner’s policy: Lender’s title insurance protects the lender only, and the CFPB is explicit that an owner’s policy is typically optional. You hold the equity at risk. See choosing a title company.
- Order the survey even when the lender does not require it: Boundaries, encroachments and access are not in the title commitment. A neighbor’s fence three feet inside your line is a survey finding.
- Use the current standard: The 2026 Minimum Standard Detail Requirements for ALTA/NSPS Land Title Surveys took effect February 23, 2026, replacing the 2021 version. Specify that edition and the Table A items you need, see ALTA resources on title review and closing.
- Object in writing, by the deadline: Most contracts set a title objection window separate from the inspection period. Miss it and you have accepted every exception.
What should the property inspection actually cover?
A general inspection is the screen, not the answer. It tells you which specialists to hire, and on a building older than 30 years expect at least two. Schedule it in week one so their reports land inside your window.
- Structure and roof: Foundation movement, framing and remaining roof life, the two most common sources of five-figure credits.
- Mechanicals: Age and condition of furnace, air conditioning, water heater and electrical panel. Write down the manufacture year of every unit; that list is your capital plan.
- Plumbing and sewer: Supply line material, plus a camera scope of the lateral to the main. A collapsed lateral is invisible to a general inspector.
- Hazards inside the building: Radon testing, and lead and asbestos assessment on older stock. The EPA recommends fixing a home at a radon level of 4 picocuries per liter or higher, and considering a fix between 2 and 4 pCi/L.
- Life safety: Alarms, egress windows, handrails, and anything a rental inspection will fail.
Hire on credentials. Here is how to find a qualified home inspector through ASHI. Then read the report properly: reading a home inspection report and the buyer’s inspection checklist show what a summary page leaves out. And the inspection is not the lender’s valuation. The home appraisal process answers what the property is worth, not what is wrong with it.
How do you review leases and estoppel certificates?
Read every lease in full, then have every tenant confirm it in writing. A rent roll is the seller’s summary; an estoppel certificate is the tenant’s sworn version, and where the two disagree the tenant is usually right. Ask each tenant to confirm rent, deposit held, end date, options, concessions, and whether the landlord owes them anything.
- Reconcile the rent roll to actual deposits: Match 12 months of bank statements to the rent roll line by line. A tenant three months behind still shows at full rent on most rent rolls.
- Hunt for terms the rent roll omits: Free months, below-market renewal options, a right of first refusal on a sale, or an oral promise about a parking space all transfer with the property.
- Confirm the deposits transfer: Security deposits are the tenants’ money. Verify the balance and confirm it is credited to you at closing.
- Check what your lender will count: Fannie Mae requires the lender to multiply gross monthly rent by 75% when using current leases or the market rents on Form 1007 for one-unit or Form 1025 for two- to four-unit properties, with the remaining 25% absorbed by vacancy and maintenance. Existing leases generally need two months of consecutive bank statements or transfers as proof of receipt, see analyzing a property’s rental potential.
How do you verify the seller’s financial numbers?
Rebuild the income statement from source documents. Ask for the trailing 12 months of operating statements, then the evidence behind each line: bank statements for income, the actual tax bill, utility bills, the insurance policy with loss runs, and repair invoices.
- Reprice the taxes at your basis: Many jurisdictions reassess on transfer, so the seller’s tax line may understate yours materially. Pull the assessor’s record.
- Add back what the seller left out: Management, vacancy, capital reserves and turnover costs are missing from most seller pro formas, and that omission is why a verified deal underperforms the advertised one.
- Read the loss runs: Three years of insurance claims tell you about water intrusion and roof history faster than any inspection narrative.
- Separate one-time from recurring: A year with no turnover is not a year with no turnover expense.
These records also become the basis for how you report the property later. The IRS rules for residential rental property income and expenses in Publication 527 explain what is deductible, what must be capitalized and depreciated, and why land is never depreciable.3 Set the recordkeeping up now, with a CPA.
What environmental and zoning checks belong in due diligence?
These are the two tracks investors skip and then regret, because both create liabilities that survive closing. A Phase I environmental site assessment is a records-and-interviews review by an environmental professional, and it is the practical route to the federal innocent landowner, contiguous property owner and bona fide prospective purchaser protections under CERCLA. EPA’s All Appropriate Inquiries rule names ASTM E1527-21 as a standard that may be used to comply, not the only permissible method. If it flags a recognized environmental condition, a Phase II adds sampling.
- Order a Phase I on anything with a commercial past: Former gas stations, dry cleaners, auto shops and heating oil tanks are the triggers. The assessment must be conducted or updated within one year of acquisition, with the interviews, records review, lien search and site visit refreshed if older than 180 days.
- Check the flood map first: Federal law requires flood insurance for the term of the loan on a building in a Special Flood Hazard Area securing a loan from a federally regulated or insured lender.
- Confirm the current use is legal, not just existing: A four-unit building in a two-unit zone may be a legal nonconforming use, or a violation you inherit. Ask in writing, see zoning regulations.
- Pull the building department file: Open permits and unpermitted finished basements are public record. Unpermitted work is a lender, insurance and resale problem at once.
How do the contingency deadlines actually work?
Each contingency is a separate deadline with its own notice requirement, and missing one usually waives it. Build the calendar the day the contract is executed and work backward from the shortest deadline. A 45-day example:
- Days 1 to 3: Order title and survey, schedule the inspection, and send a written document request, leases, rent roll, trailing 12 months, tax and utility bills, loss runs and permits.
- Days 4 to 10: Inspection and specialist walk-throughs. Order the Phase I. On pre-1978 target housing, the federal 10-day lead-paint evaluation period runs before you are obligated under the contract, so negotiate it into the offer rather than starting it here.
- Days 10 to 20: Title and survey reviewed with counsel, estoppels out to tenants, lender appraisal ordered.
- Days 20 to 30: Financial reconciliation complete, Phase I delivered, estoppels returned and compared against the leases.
- Days 30 to 40: Title objection notice, repair or credit request, renegotiation.
- Days 40 to 45: Contingency removal or written termination notice, loan conditions cleared.
One protection you may be assuming does not apply. Regulation Z’s official commentary deems credit to acquire, improve or maintain rental property that is not owner-occupied, regardless of unit count, to be business-purpose credit, placing most investment purchase loans outside Truth in Lending, including the rule that a consumer receive the Closing Disclosure at least three business days before consummation. If you expect to occupy the property more than 14 days in the coming year, that treatment does not apply.4 Either way, your contract’s deadlines are the schedule protecting you. See home purchase contingencies, contingencies in home offers and earnest money deposits.
What do you do with what due diligence turns up?
Every window ends in one of three decisions: proceed, renegotiate, or terminate and recover the deposit. Renegotiate on documented cost, not on feeling: a roof with four years left, quoted at $18,000, is an $18,000 conversation, and “the roof looked old” is not. Say plainly whether you want a price reduction, a credit or the repair done before closing, how to price and stage that ask is in tips for negotiating a real estate deal, see negotiating repairs after a home inspection and managing repairs during escrow. If the findings hit the thesis rather than the building, terminating is a result.
How Align finances investors
Samantha looks at the property's numbers before the loan's, and she says so plainly: "I don't love a deal that only works when nothing goes wrong."
Align places DSCR loans, which qualify on the rent the property brings in rather than your tax returns, as well as conventional investment loans, through multiple wholesale lenders.
FAQ: Real estate due diligence
Here are answers to common questions about real estate due diligence.
How long does real estate due diligence take?
Most investment deals allow 30 to 60 days, though small residential rentals often compress to 10 to 21 days and large commercial deals can extend to 90. The clock starts at contract execution, so order the title commitment, survey and inspections in the first week. Waiting until day 20 to schedule a specialist inspection is the most common cause of a blown deadline. See how the home closing process runs.
How much does due diligence cost?
Budget roughly 0.5% to 1% of purchase price on smaller investment deals. A general inspection commonly runs several hundred to a few thousand dollars depending on size, with separate line items for a survey, an environmental Phase I, roof or structural specialists, and attorney review. These costs are typically non-refundable even if you terminate, which is the price of information. Plan for them alongside budgeting for closing costs.
What are the biggest red flags in due diligence?
Watch for gaps between the rent roll and actual deposits, leases with unrecorded concessions or renewal options, unpermitted work visible in the building department file, deferred maintenance on roof and mechanicals, zoning that does not match the current use, and title exceptions such as easements crossing usable land. Any one can change value materially. See avoiding common home inspection pitfalls.
Can I do due diligence myself or should I hire professionals?
You can coordinate it yourself, but the technical reviews should be professional. A licensed inspector or engineer for condition, a title company and attorney for legal, and a CPA for financial verification each catch problems a generalist misses. Your job is assembling the team, holding the schedule, and turning their findings into a negotiating position.
The bottom line on real estate due diligence
Due diligence is the verification window between an accepted offer and closing, it typically runs 30 to 60 days on investment deals, and it exists to confirm in writing what the seller told you. Run all four tracks, order the long-lead items in the first three days, and treat every contingency as a separate deadline with its own written notice. Budget 0.5% to 1% of purchase price, and expect one of three outcomes: proceed, renegotiate on documented cost, or terminate and take the deposit back.
If you’re ready to line up financing while your due diligence clock is running, talk to Align Lending. We’ll shop your scenario across our lender network and show you the numbers side by side. Call 248-506-5727 or start online. Take contract, title and environmental questions to a Michigan real estate attorney, and tax questions to a qualified tax professional.
Footnotes:
1. This is general information, not legal advice. Federal lead-based paint disclosure duties, the all appropriate inquiries standard, and the CERCLA landowner liability protections carry statutory conditions and continuing obligations that depend on the property and the transaction, and they are subject to change. Consult a real estate attorney and a qualified environmental professional about your situation. Return to text.
2. Timing and cost ranges shown in the table and elsewhere in this article are general observations from Align Lending’s broker network and are illustrative only. They are not quotes, estimates, or an offer of any service, and actual vendor turnaround times and fees vary by market, property type, property size, and provider. Return to text.
3. This is general information, not tax advice. Whether an expense is currently deductible or must be capitalized and depreciated, how basis is allocated between land and improvements, and how rental activity is reported depend on your individual circumstances and on tax rules that change. Consult a qualified tax professional about your situation. Return to text.
4. This is general information, not legal advice. Whether a particular loan is business-purpose credit exempt from Regulation Z is a determination made by the creditor on the facts of the transaction, and coverage under other federal and state rules may differ. Align Lending is a mortgage broker, not a law firm; confirm the treatment of your transaction with your loan officer and a Michigan real estate attorney. Return to text.
Sources: requirement that, before a purchaser is obligated under any contract to purchase target housing built before 1978, the seller permit the purchaser a 10-day period, unless the parties mutually agree in writing upon a different period of time, to conduct a risk assessment or inspection for the presence of lead-based paint or lead-based paint hazards, together with the disclosure, records and pamphlet requirements, 42 U.S.C. 4852d, and implementing rules at 40 CFR 745.110 and 40 CFR Part 745 Subpart F and 24 CFR Part 35 Subpart A. Requirement that all appropriate inquiries be conducted within one year prior to the date of acquisition, with interviews, lien searches, on-site inspection and government records review conducted or updated within 180 days of and prior to acquisition, 40 CFR 312.20; listing of ASTM International Standard E1527-21 among the industry standards that may be used to comply with the rule, 40 CFR 312.11, Standards and Practices for All Appropriate Inquiries, U.S. Environmental Protection Agency. Availability of the innocent landowner, contiguous property owner and bona fide prospective purchaser liability protections under the Comprehensive Environmental Response, Compensation, and Liability Act on satisfaction of all appropriate inquiries and continuing obligations, U.S. Environmental Protection Agency, Superfund Landowner Liability Protections. EPA recommendation that homes be fixed at radon levels of 4 pCi/L or higher and that a fix be considered between 2 and 4 pCi/L, U.S. Environmental Protection Agency, What Is EPA’s Action Level for Radon and What Does It Mean? Lender’s title insurance protecting the lender only, and owner’s title insurance being typically optional for the consumer, Consumer Financial Protection Bureau, Ask CFPB. Adoption of the 2026 Minimum Standard Detail Requirements for ALTA/NSPS Land Title Surveys, effective February 23, 2026 and replacing the 2021 version, American Land Title Association and National Society of Professional Surveyors. Requirement that lenders calculate rental income by multiplying gross monthly rent by 75%, with the remaining 25% absorbed by vacancy losses and maintenance, use of Form 1007 for one-unit and Form 1025 for two- to four-unit properties, and documentation of existing leases with two months of consecutive bank statements or electronic transfers of rental payments, Fannie Mae Selling Guide, Rental Income. Requirement that flood insurance be maintained for the term of the loan on improved real estate located in a Special Flood Hazard Area and securing a loan from a federally regulated or insured lending institution, 42 U.S.C. 4012a, Flood Disaster Protection Act of 1973 as amended by the National Flood Insurance Reform Act of 1994. Official interpretation deeming credit extended to acquire, improve, or maintain rental property that is not owner-occupied, regardless of the number of housing units, to be for business purposes, and the test treating a property as owner-occupied where the owner expects to occupy it more than 14 days in the coming year, Official Interpretations to 12 CFR 1026.3(a), comment 3(a)-4, Regulation Z. Requirement that the consumer receive the Closing Disclosure no later than three business days before consummation, 12 CFR 1026.19(f)(1)(ii). Reporting of residential rental income and expenses on Schedule E (Form 1040), the 27.5-year recovery period and mid-month convention for residential rental property under the MACRS general depreciation system, and the rule that land is not depreciable, Internal Revenue Service Publication 527, Residential Rental Property. Due diligence period lengths of 30 to 60 days on investment purchase agreements, 10 to 21 days on small residential rentals, and due diligence costs of 0.5% to 1% of purchase price, Align Lending broker network observations.
This article is for informational purposes only and is not intended to provide legal, financial, tax, or investment advice. Contract deadlines, disclosure duties, zoning treatment, environmental liability, loan program requirements and tax rules change and vary by property, program, and locality; confirm loan requirements with your loan officer, confirm contract, title, zoning and environmental obligations with a Michigan real estate attorney and a qualified environmental professional, and confirm tax treatment with a qualified tax professional. Figures shown are illustrative, are not a rate quote or an offer of credit, and do not constitute an advertisement of credit terms. Align Lending is an independent Michigan mortgage broker, NMLS #2041154, and is not a broker-dealer, investment adviser, securities issuer, or property manager.
Related resources
13-minute read
Buying a home as an investment property: A step-by-step guide
Learn how buying a home as an investment property works, from 15%+ down payments and financing options to ROI math, so your first rental starts profitable.
13-minute read
Real estate appreciation: How property values grow and why it matters
Learn how real estate appreciation works, why U.S. homes have averaged roughly 3% to 5% a year, and how forced appreciation can add to returns.
12-minute read
1031 exchanges: Rules, deadlines and benefits for investors
Learn how a 1031 exchange defers capital gains tax, why the 45-day and 180-day deadlines are absolute, and which properties qualify as like-kind.
