
Selling a home as-is: Pros and cons for sellers
This article is general information about selling strategy, not legal or tax advice. Disclosure duties, contract language and tax treatment depend on your property and your circumstances. Consult a Michigan real estate attorney and a qualified tax professional.
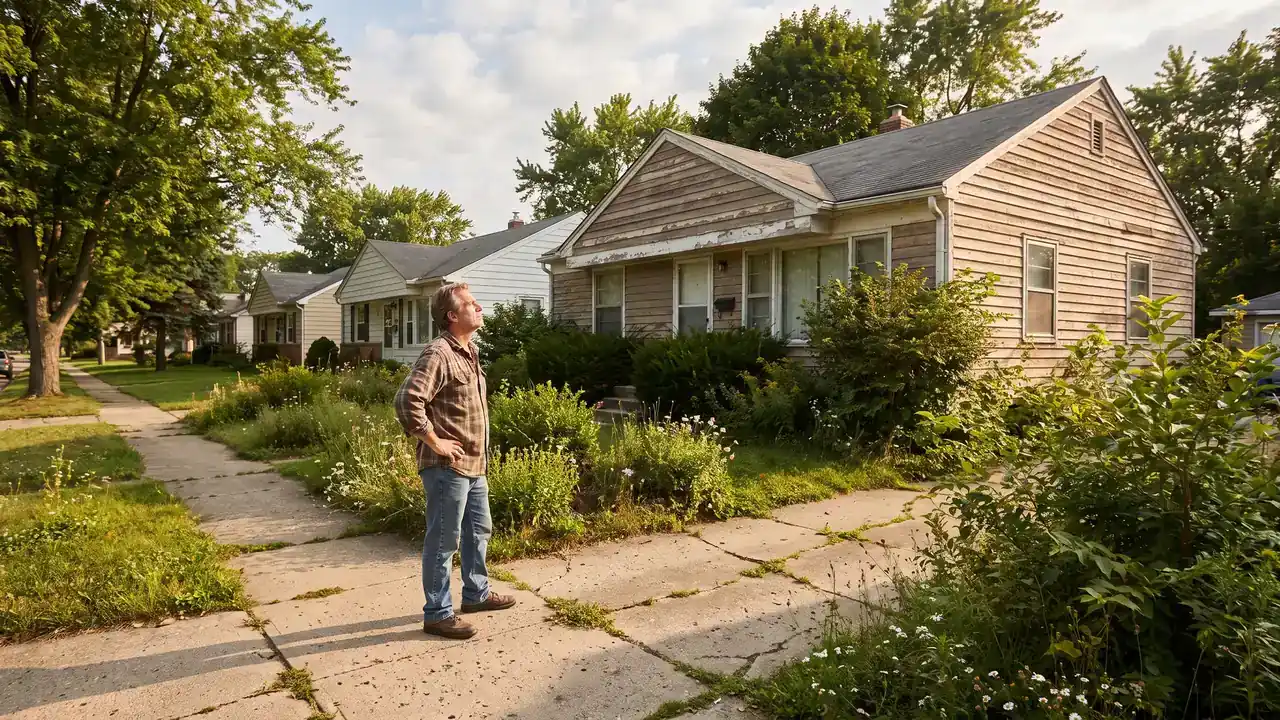
Selling as-is means you list the home in its current condition and tell buyers up front that you will not make repairs. It does not mean you stop disclosing: Michigan’s Seller Disclosure Act applies to transfers of any interest in real estate of not less than 1 or more than 4 residential dwelling units, and an as-is sale is not on the statute’s list of exempt transfers.
What as-is buys is the end of repair negotiation. What it costs is price, because buyers discount for repair cost plus the risk of what the repair uncovers. Federal law adds a floor: on pre-1978 housing you must give the buyer the lead hazard pamphlet, disclose known lead-based paint and hazards, and allow a 10-day inspection period unless you both agree otherwise.
Learn what an as-is clause changes, the discount it invites, which buyers can still finance the home, and when repairs beat it. Earlier in the process? Start with our Selling a Home guide and the Selling Strategies hub.
Key takeaways:
- As-is limits repairs, not disclosure: Michigan’s disclosure statute covers transfers of 1 to 4 residential dwelling units, and its statutory form warns in capital letters that failing to give a purchaser a signed disclosure statement will let that purchaser terminate an otherwise binding purchase agreement.
- As-is does not mean cash-only: Fannie Mae accepts properties rated C1 through C5 as-is and rejects only C6, and an FHA appraiser must limit required repairs to what protects safety, security, soundness, marketability and occupant health.
- Fix what blocks a loan, sell the rest as-is: A roof with less than two years of remaining life makes an FHA appraisal subject to a roofer’s inspection, while an FHA Limited 203(k) lets your buyer finance up to $75,000 of repairs into the mortgage.
What does selling a home as-is mean?
Selling as-is means the purchase contract limits your obligation to repair, and nothing else. It is a negotiating term, not a legal shield: you will not credit, fix or renegotiate over what an inspection turns up. Three things survive it.
- Your disclosure duty: The statutory seller’s disclosure must still be completed, signed and delivered. See what a seller’s disclosure is.
- The buyer’s inspection: An as-is listing does not remove an inspection contingency unless the contract explicitly waives it. Buyers still inspect; they use the result to decide whether to walk, not to ask for repairs.
- The lender’s opinion: If the buyer is financing, the appraiser reports condition to the lender regardless of what your listing says. See the home appraisal process.
As-is converts an unknown repair negotiation into a known price concession. Often a good trade, never a disappearing act.
Does an as-is listing let you skip the seller’s disclosure?
No. Michigan’s Seller Disclosure Act requires the written statement on transfers of 1 to 4 residential dwelling units, and its exemptions are situations, not sale styles, court orders, foreclosures, fiduciary transfers, close-family transfers. Selling in current condition is not among them.
Timing is strict: the statement must reach the buyer before you execute a binding purchase agreement. If a required disclosure or amendment lands after you sign, the buyer may terminate in writing within 72 hours of personal delivery, or 120 hours by registered mail, a right that expires once the property transfers by deed or installment sales contract.
The Act also protects an honest seller. You are not liable for an error or omission outside your personal knowledge, and it is not a violation to miss something findable only by inspecting inaccessible portions of the property, or only by someone with expertise beyond yours. Disclosure must be made in good faith, defined as honesty in fact. What the Act will not do is erase other law: it expressly does not limit any obligation regarding fraud, misrepresentation or deceit, so writing “as-is” in bold does not turn a known, concealed defect into a permitted omission. Nolo’s overview of seller disclosure duties and legal exposure is a starting point; take your specifics to a Michigan attorney.
What does the fall 2026 market mean for an as-is seller?
Buyers have more homes to choose from than a year ago. NAR’s existing-home sales report put September 2026 existing-home sales at 3.99 million, with inventory rising to 1.60 million homes and prices up 1.3%, and NAR Chief Economist Lawrence Yun said higher inventory and lengthening days on market give buyers improved negotiating power. Prices are still rising slowly: FHFA reported on August 25, 2026 that U.S. house prices rose 2.1% between the second quarter of 2025 and the second quarter of 2026, and 4.5% in the East North Central census division.
For an as-is seller, more inventory means every buyer who reads your inspection report has other houses to compare it with. A price that reflects the condition from the first day gives buyers less reason to wait for a cut. For list price strategy, see how to price your home for a quick sale.
The national survey picture shows why financing matters to an as-is seller. In the REALTORS® Confidence Index survey for September 2026, released October 13, 2026, 27% of buyers paid cash, so 73% did not. Members reported that 20% of buyers waived the inspection contingency, 18% waived the appraisal contingency, 5% of contracts were delayed by appraisal issues and 7% of contracts were terminated in the prior three months. A house that clears the loan programs’ condition lines stays open to the financed majority; one that fails them is selling mainly to the cash share, 27% of buyers in that survey.
How much does an as-is listing cost you in price?
Expect a discount larger than the repair bill, because a buyer prices three things you do not: the contractor’s number, the risk behind the wall, and the cost of carrying the house during the work. There is no reliable percentage for this, and any article quoting one without a named study and a year is guessing.
Say a home would appraise at $260,000 repaired and needs a $12,000 roof.1 A buyer holding a signed roofing bid negotiates against $12,000. A buyer holding only an inspection note reading “roof at end of service life, recommend evaluation” negotiates against an unknown, and unknowns get padded. That padding is the real cost of an unpriced as-is listing, and two written bids remove it.
The second pressure is competition: every buyer eliminated on financing grounds is one fewer bidder. Model the net, not the headline price, with the finances of selling and seller-paid closing costs. Selling to an investor is a separate decision, covered in the pros and cons of selling to a cash buyer; an as-is listing and a cash sale are not the same choice, and you can list as-is and still take a financed offer.
Which buyers can finance an as-is home?
More than most sellers assume. No major loan program refuses a home because the listing says as-is; each draws its line at condition, and that line sits well below move-in ready. Because Align Lending is a broker, not one bank, we can tell you which programs could close on your house as it sits.
- Conventional: Fannie Mae rates condition C1 to C6, and C1 through C5 are eligible as-is. A C5 home has obvious deferred maintenance and needs significant repairs but stays useable and functional. Only C6 (deficiencies severe enough to affect safety, soundness or structural integrity) is ineligible, and those must be repaired to a minimum resulting rating of C5.
- FHA: An appraiser may complete an as-is appraisal on an existing property when minor deficiencies from deferred maintenance and normal wear and tear do not affect occupant health and safety or the property’s security and soundness. Cosmetic items (handrails that pose no threat, holes in window screens, cracked glass, a dripping faucet) are not required repairs. Where repairs are required, they must be limited to what maintains safety, security and soundness, preserves marketability, and protects occupant health. Roofs get a specific test: less than two years of remaining physical life makes the appraisal subject to inspection by a professional roofer.2
- VA: No purchase loan is eligible for guaranty unless the property conforms to the standards of planning, construction and general acceptability prescribed by the Secretary of Veterans Affairs, condition-based standards, not cosmetic ones.3
- USDA: An existing dwelling must be structurally sound, functionally adequate, in good repair or placed in good repair with loan funds, with adequate and safe electrical, heating, plumbing, water and wastewater systems.
- Renovation loans: The buyer-pool fix when a house fails the others. An FHA Limited 203(k) finances up to $75,000 of repairs into the mortgage, a ceiling HUD set in Mortgagee Letter 2024-13 and reviews annually alongside its loan limits; a Standard 203(k) covers major rehabilitation and structural work and requires a minimum of $5,000 in eligible improvements.
The consequence is clean: defects crossing the safety, soundness or structural line remove financed buyers and leave you cash offers. Cosmetic defects cost price, not buyers.
Can you offer a credit instead of making repairs?
You can offer one, but each loan program caps what a seller may contribute and limits what the money pays for, and a credit does not change the appraiser’s condition report. A roof at the end of its life is still reported to the lender even if you give the buyer money at closing.
- Conventional: Fannie Mae’s Selling Guide B3-4.1-02 (topic dated May 7, 2025) caps interested party contributions on a principal residence or second home at 3% when the LTV/CLTV ratio is greater than 90%, 6% from 75.01% to 90%, and 9% at 75% or less, and at 2% on an investment property. The acceptable uses it lists are the buyer’s closing costs, including prepaids, and some homeowners association assessments, and the contribution cannot be used for the down payment. See conventional loans.
- FHA: According to HUD’s Single Family Housing Policy Handbook 4000.1, Update 18 (last revised August 12, 2026), interested parties may contribute up to 6% of the sales price toward the borrower’s origination fees, other closing costs, prepaid items and discount points. See FHA loans.
- VA: According to VA’s funding fee and closing costs page (last updated October 5, 2026), VA limits seller’s concessions to no more than 4% of the home’s reasonable value and does not limit credits for a loan’s closing costs. It defines a concession as anything of value added to the transaction at no additional cost to the buyer, such as a credit for the VA funding fee, paying off the buyer’s debt or prepaying hazard insurance. See VA loans.
The practical split: a credit helps a buyer with cash to close, while a repair is what moves a home back across a condition line. A cosmetic defect costs price, not buyers, so a credit or a price adjustment is a negotiating choice. A safety, soundness or structural defect needs the fix itself, or a buyer using a renovation loan such as one of the FHA 203(k) loans described above.
When does selling as-is beat making repairs?
As-is wins when the repair costs as much as the value it unlocks, when you cannot fund it, or when contractors will not fit your timeline. Repair-first wins when a targeted fix moves the house back across a financing line.
| Factor | Selling as-is | Repairing first |
|---|---|---|
| Upfront cash | None beyond normal listing prep | Paid before closing, out of pocket or on credit |
| Buyer pool | Narrows only if defects affect safety, soundness or structure | Widest, including buyers needing a clean appraisal |
| Financing eligibility | Conventional to C5; FHA, VA, USDA if condition standards are met | All programs, with fewer appraisal conditions |
| Time to close | Faster to contract; no repair renegotiation | Weeks added before listing, usually smoother after |
| Net proceeds | Lower price, no repair spend, no carrying cost | Higher price, minus repair cost and time held |
| Disclosure exposure | Unchanged | Unchanged |
As-is is usually right for an inherited or long-vacant property you cannot manage from a distance, for a house where deferred maintenance is spread across roof, mechanicals and finishes so no single fix changes the condition rating, and for a seller whose cash is committed to the next purchase.
Repairs usually pay on a financing-blocking defect with a known price (a roof at the end of its life, a dead furnace) and on any safety item an appraiser will condition the loan on. Two categories need their own playbook rather than a blanket as-is clause, because both frighten buyers out of proportion to the repair.
What does an as-is sale leave you after Michigan transfer tax?
Less than the headline price, and the transfer tax follows the price down. Under MCL 207.525 the state real estate transfer tax is $3.75 for each $500 or fraction of $500 of the property’s value, and under MCL 207.504 the county tax is 55 cents per $500 in a county with a population of less than 2,000,000. MCL 207.523 makes the seller liable for the state tax, and Michigan Treasury’s State Real Estate Transfer Tax page says it is paid through the county when the deed is recorded and that some buyers and sellers agree the buyer will pay it on the seller’s behalf.
Hypothetical example, not an offer. Take the $260,000 repaired value and $12,000 roof from the pricing section above, and suppose an as-is buyer pads the unknown and pays $240,000.
| Line | Sell as-is | Replace the roof first |
|---|---|---|
| Sale price | $240,000 | $260,000 |
| State transfer tax ($3.75 per $500) | $1,800 | $1,950 |
| County transfer tax (55 cents per $500) | $264 | $286 |
| Roof replacement | None | $12,000 |
| Left before payoff, commission and other costs | $237,936 | $245,764 |
Tax rates: MCL 207.525 and MCL 207.504 as linked above; Oakland County Register of Deeds fees list the same $3.75 state and $.55 county rates per $500. Sale prices and roof cost are illustrative.
In this example, repairing first leaves $7,828 more, before the cost of carrying the house while the roof goes on and before the chance that the work uncovers more. The transfer tax difference is only $172; the buyer’s padding decides the outcome. Run your own figures in the seller net sheet calculator or the Michigan transfer tax calculator, and see sellers’ closing costs for the rest of the list. A principal residence that meets the conditions in MCL 207.526 can be exempt from the state portion; if the tax was paid, Treasury’s page says a refund request must be filed within four years and 15 days of the sale.
How do you list as-is without shrinking your buyer pool?
Price the condition instead of hiding it, and give buyers numbers to underwrite. Every unknown gets padded, so replacing unknowns with documents is the cheapest price protection you have.
- Get a pre-listing inspection: It tells you which side of the financing line your house sits on before a buyer’s inspector tells their agent. See the benefits of a pre-listing home inspection, then the American Society of Home Inspectors on finding a certified inspector for a pre-listing inspection.
- Collect two written bids on big-ticket items: A signed bid is a negotiating anchor; without one, you argue against the buyer’s guess.
- Complete the disclosure carefully, not defensively: The statutory form tells sellers to answer all questions, report known conditions, fill it out themselves, and check “unknown” where they do not know. “Unknown” is an honest answer. A blank is not.
- Describe the property, never the buyer: Federal fair housing law makes it unlawful to publish any advertisement for the sale of a dwelling indicating a preference, limitation or discrimination based on race, color, religion, sex, handicap, familial status or national origin. Michigan’s Elliott-Larsen Civil Rights Act separately bars real estate advertising indicating, directly or indirectly, an intent to discriminate based on religion, race, color, national origin, age, sex, sexual orientation, gender identity or expression, familial status or marital status. “Solid bones, full rehab needed” describes the house. Anything describing who should live there, or who the neighbors are, does not.
- Put the marketing plan in the listing agreement: An as-is home takes different work than a turnkey one.
One note on compensation, because it changed. Since August 17, 2024, offers of compensation to buyer agents cannot be communicated through a multiple listing service, and MLS-participant buyer agents must have a written agreement with their buyer before touring. Commission has always been negotiable and there is no standard or customary rate; a concession toward the buyer’s costs is negotiated in the contract, not published on the MLS.
How do you vet a cash offer on an as-is house?
Treat an unsolicited cash offer as a starting number, not a verdict on your house. Fraud.org warned on June 1, 2023 that some buyers of “ugly” houses may significantly undervalue the home, tack on junk fees or trap the owner in complicated contracts, citing a ProPublica report on an 82-year-old homeowner with dementia who lost one third of the value of her house in such a deal. Its tips for homeowners:
- Know your home’s value from recent sale prices of comparable homes nearby.
- Get offers from several buyers and compare them.
- Review fees, future obligations and cancellation terms in writing.
- Have a trusted advisor read the offer; Fraud.org points to HUD’s directory of housing counselors.
- Treat pressure to sign quickly, and offers you did not ask for, as red flags.
Michigan added its own guard in 2024. Under MCL 339.2512g, added by 2024 PA 122 with immediate effect on July 25, 2024, a right-to-list home sale agreement is void and unenforceable if it is not in writing, is not signed by everyone with an ownership interest, runs longer than 2 years, or does not include an early termination option and a first-page statement of its term and that option. The payment to end it early is capped at the money the broker paid the owner plus 6% interest per year. If a company offers you money now for the right to list your house later, read the offer against that section. For an inherited house, see selling a home in probate before you accept anything.
What Michigan sellers should know about an as-is sale
Michigan’s disclosure statute controls an as-is sale here. Four points matter most.
- Coverage is by unit count, not sale type: It reaches 1-to-4-unit residential transfers by sale, exchange, installment land contract, lease with an option to purchase, or transfer of stock in a residential cooperative.
- The exemptions are situational: Court-ordered transfers, foreclosure sales and deeds in lieu, transfers by a nonoccupant fiduciary administering an estate, guardianship, conservatorship or trust, transfers between co-tenants, transfers to close family, and transfers to or from a governmental entity. Inherited a home and living in it? Ask counsel before assuming the fiduciary exemption reaches you.
- Late delivery hands the buyer an exit: A disclosure delivered after you sign gives the buyer 72 hours from personal delivery, or 120 by registered mail, to terminate in writing.
- The form is a disclosure, not a warranty: The statute says so, and adds that it is no substitute for inspections or warranties the buyer may wish to obtain. That cuts both ways: you are not promising the roof, and the buyer is not excused from checking it.
Pre-1978 housing carries the federal lead duties on top of the state form. For disclosure wording or contract questions, talk to a Michigan real estate attorney.
How Align helps when you are selling
If you are buying your next home too, the order matters. Samantha lines up your next mortgage before your home lists, so the sale and the purchase run on one timeline instead of two.
Your closing date is set by your purchase agreement. Her job is to have your loan ready well before it.
She lives and works in Oakland County, and local agents bring her in for second opinions when their buyers arrive preapproved elsewhere. You get one person who knows your goals from the first call to the closing table, with a processor supporting her behind the scenes.
FAQ: Selling a home as-is
Here are answers to common questions about selling a home as-is.
Does selling as-is mean I don’t have to disclose problems?
No. As-is limits your obligation to repair, not to disclose. Michigan requires a written seller disclosure of known conditions on 1-to-4-unit residential transfers, and federal law separately requires a lead-based paint disclosure on pre-1978 homes. Concealing a known defect can support a fraud claim after closing, even with as-is in the contract. See what a seller’s disclosure is.
Do buyers still get an inspection on an as-is home?
Almost always. An as-is listing does not remove a buyer’s inspection contingency unless the contract explicitly waives it; buyers use the result to decide whether to walk. Many sellers publish their own report first, so offers arrive priced for the condition. See the benefits of a pre-listing home inspection.
How much less does an as-is home sell for?
There is no single reliable figure, and the discount typically exceeds the repair cost because buyers price in risk, delay and financing friction. The gap widens when a defect pushes the property past what conventional, FHA, VA or USDA guidelines allow, since that removes financed buyers. Two written bids let you argue the number instead of accepting the buyer’s estimate. Model it with the finances of selling.
Should I sell as-is or make repairs first?
Repair when the fix costs less than the value it unlocks, especially financing blockers: a failing roof, a dead furnace, unsafe electrical, structural damage. Sell as-is when repair cost approaches the value gain, when you lack the cash, or when contractors will not fit your timeline. A pre-listing inspection tells you which you are in, and if the house is a full project, read our guide to selling a fixer-upper.
Can I sell a house as-is in Michigan without a realtor?
Yes, though few owners do. NAR reported in its 2025 Profile of Home Buyers and Sellers, covering July 2024 to June 2025, that 5% of homes sold by owner, at a median price of $360,000 against $425,000 for agent-assisted homes. NAR noted the gap may reflect that owner-sold homes are more often lower-cost mobile homes. Weigh the trade-offs in selling without a realtor.
Do I have to test for lead paint before selling an older house as-is?
No. EPA's real estate disclosure page, last updated May 27, 2026, lists what sellers must do, and testing or removing lead is not on the list. You must hand over all available records and reports on lead-based paint, include a Lead Warning Statement with the contract, and keep a signed copy of the disclosures for three years after the sale. Real estate agents share responsibility for compliance with the seller.
Can a financed buyer back out if an as-is home appraises low?
On a VA loan, yes. The VA Home Loan Buyer's Guide explains the escape clause: the buyer has the option not to purchase when VA's Notice of Value is below the contract price, or may proceed anyway. The options it lists are a reconsideration of value, renegotiating the price, or bringing cash. HUD's Handbook 4000.1 sets out a similar amendatory clause for FHA purchases. See selling a home with a low appraisal.
Do I owe capital gains tax when I sell my house as-is?
Not on gain within the home sale exclusion, if you qualify. According to IRS Topic 701, last reviewed October 12, 2026, you may exclude up to $250,000 of gain, or $500,000 on a joint return, if you meet the ownership and use tests during the 5 years ending on the sale date. IRS Publication 523 figures gain from the amount realized, the sale price minus selling expenses. See capital gains tax exemptions.
The bottom line on selling a home as-is
Selling as-is is a pricing decision, not a legal one. It ends repair negotiation and saves the cash and calendar of contractors, and it costs you price because buyers pad every unknown. It does not touch your disclosure duty: Michigan’s Seller Disclosure Act still applies to transfers of 1 to 4 residential dwelling units, and pre-1978 homes still carry the federal lead pamphlet, disclosure and 10-day inspection opportunity. Before you list, find out which side of the financing line your house sits on, defects affecting safety, soundness or structure remove financed buyers, while cosmetic ones only cost dollars.
If you’re ready to find out whether a financed buyer could close on your home as it sits, and what your proceeds will buy next, talk to Align Lending. We’ll shop your scenario across our lender network, including renovation programs, and show you the numbers side by side. Call 248-506-5727 or start online. Buying before you sell? Price bridge financing and get preapproved first. Take contract questions to a Michigan real estate attorney and tax questions to a tax professional.
Footnotes:
1. Example figures are hypothetical and for educational purposes only; they do not constitute an advertisement of credit terms or a rate quote under federal or state lending laws. The $260,000 repaired value and $12,000 roof cost are illustrative figures chosen to demonstrate how a buyer prices a known repair against an unknown one. They are not an estimate of any actual property value or contractor cost, and your results depend on your property, your local market and actual bids. Return to text.
2. Align Lending is not acting on behalf of or at the direction of FHA or HUD. FHA minimum property requirements, appraisal repair conditions, and 203(k) rehabilitation limits are set by HUD and are subject to change. Return to text.
3. Align Lending works with VA-approved lenders and is not endorsed or sponsored by the Dept. of Veterans Affairs or any government agency. VA minimum property requirements and standards of general acceptability are set by the Department of Veterans Affairs and are subject to change. Return to text.
Sources: application of the seller disclosure requirements to the transfer of any interest in real estate consisting of not less than 1 or more than 4 residential dwelling units, whether by sale, exchange, installment land contract, lease with an option to purchase, other option to purchase, ground lease coupled with proposed improvements, or transfer of stock or an interest in a residential cooperative, Michigan Seller Disclosure Act, 1993 PA 92, MCL 565.952. List of exempt transfers, including transfers pursuant to court order, foreclosure sales, transfers to a mortgagee by a mortgagor in default, deeds in lieu of foreclosure, transfers by a nonoccupant fiduciary in the administration of a decedent’s estate, guardianship, conservatorship or trust, transfers from one co-tenant to other co-tenants, transfers to a spouse, parent, grandparent, child or grandchild, transfers between spouses resulting from a divorce judgment or incidental property settlement, and transfers or exchanges to or from a governmental entity, MCL 565.953. Delivery of the written statement to the prospective transferee before the transferor executes a binding purchase agreement, and the transferee’s right to terminate by written notice not later than 72 hours after personal delivery or 120 hours after delivery by registered mail, with that right expiring upon transfer by deed or installment sales contract, MCL 565.954. Transferor not liable for an error, inaccuracy or omission not within personal knowledge, and no violation for failing to disclose information obtainable only through inspection of inaccessible portions of the real estate or only by a person with expertise beyond the transferor’s knowledge, MCL 565.955. Prescribed Seller’s Disclosure Statement form, including the statement that it is not a warranty and is not a substitute for any inspections or warranties the buyer may wish to obtain, the instruction to check “unknown” where the seller does not know the facts, and the notice that failure to provide a purchaser with a signed disclosure statement will enable a purchaser to terminate an otherwise binding purchase agreement, MCL 565.957. Good faith defined as honesty in fact in the conduct of the transaction, MCL 565.960. Preservation of all other disclosure obligations created by law regarding fraud, misrepresentation or deceit in transfer transactions, MCL 565.961. Requirement that sellers of target housing provide a lead hazard information pamphlet, disclose known lead-based paint and known lead-based paint hazards, and permit the purchaser a 10-day period, unless the parties mutually agree upon a different period, to conduct a risk assessment or inspection, with target housing defined as housing constructed prior to 1978, 42 U.S.C. 4852d. Condition ratings C1 through C6, the C5 and C6 definitions, eligibility of properties rated C1 through C5 in “as is” condition, ineligibility for sale to Fannie Mae of loans secured by properties rated C6, and the requirement that deficiencies affecting safety, soundness or structural integrity be repaired to a minimum resulting condition rating of C5, Fannie Mae Selling Guide B4-1.3-06, Property Condition and Quality of Construction of the Improvements, version dated June 4, 2025. Limitation of FHA-required repairs to those necessary to maintain the safety, security and soundness of the property, preserve continued marketability, and protect the health and safety of the occupants; permission to complete an as-is appraisal on existing properties where minor deficiencies resulting from deferred maintenance and normal wear and tear do not affect the health and safety of the occupants or the security and soundness of the property, with cosmetic repairs not required; the requirement that a roof covering have a remaining physical life of at least two years, with the appraisal made subject to inspection by a professional roofer where it does not; and the appraisal conditions applied where repairs are needed to protect occupant health and safety, protect the security of the property, or correct physical deficiencies or conditions affecting structural integrity, U.S. Department of Housing and Urban Development, FHA Single Family Housing Policy Handbook 4000.1, II.D, Appraiser and Property Requirements for Title II Forward and Reverse Mortgages. Limited 203(k) total rehabilitation cost limit of $75,000, and the statement that the limit is evaluated annually in conjunction with the forward mortgage loan limits, U.S. Department of Housing and Urban Development, Mortgagee Letter 2024-13, Revisions to the 203(k) Rehabilitation Mortgage Insurance Program, dated July 9, 2024 and effective for FHA case numbers assigned on or after November 4, 2024. Requirement of a minimum of $5,000 in eligible improvements for a Standard 203(k), FHA Single Family Housing Policy Handbook 4000.1, II.A.8.a. Requirement that no loan for the purchase or construction of residential property be eligible for VA guaranty or insurance unless the property complies or conforms with the standards of planning, construction and general acceptability prescribed by the Secretary, 38 CFR 36.4351. Requirement that existing dwellings be structurally sound, functionally adequate, in good repair or placed in good repair with loan funds, and have adequate and safe electrical, heating, plumbing, water and wastewater disposal systems, 7 CFR 3555.202(b). Prohibition on making, printing or publishing any notice, statement or advertisement with respect to the sale of a dwelling that indicates any preference, limitation or discrimination based on race, color, religion, sex, handicap, familial status or national origin, Fair Housing Act, 42 U.S.C. 3604(c). Prohibition on causing to be published a statement, advertisement, notice or sign in a real estate transaction that indicates, directly or indirectly, an intent to make a preference, limitation, specification or discrimination on the basis of religion, race, color, national origin, age, sex, sexual orientation, gender identity or expression, familial status or marital status, Michigan Elliott-Larsen Civil Rights Act, MCL 37.2502. Prohibition on communicating offers of compensation through a multiple listing service and the requirement that MLS-participant buyer agents enter a written agreement with the buyer before touring a home, effective August 17, 2024, National Association of REALTORS®.
This article is for informational purposes only and is not intended to provide legal, financial, or tax advice. Disclosure duties, statutory deadlines, loan program guidelines and fair housing requirements change and vary by program, property and locality; confirm current loan program requirements with your loan officer, confirm contract and disclosure obligations with a Michigan real estate attorney, and confirm tax treatment with a qualified tax professional. Figures shown are illustrative, are not a rate quote or an offer of credit, and do not constitute an advertisement of credit terms. Align Lending is an independent Michigan mortgage broker, NMLS #2041154.
Sources
Every outside source this guide links to, in the order it appears. How we choose and check sources
- Seller disclosure duties and legal exposureNolo
- Existing-home sales reportNational Association of Realtors
- FHFA reported on August 25, 2026Federal Housing Finance Agency
- REALTORS® Confidence IndexNational Association of Realtors
- Fannie Mae’s Selling Guide B3-4.1-02Fannie Mae Selling Guide
- Single Family Housing Policy Handbook 4000.1, Update 18U.S. Department of Housing and Urban Development
- Funding fee and closing costs pageU.S. Department of Veterans Affairs
- MCL 207.525Michigan Legislature
- MCL 207.504Michigan Legislature
- MCL 207.523Michigan Legislature
- State Real Estate Transfer Tax pageState of Michigan
- Oakland County Register of Deeds feesoaklandcountymi.gov
- MCL 207.526Michigan Legislature
- Finding a certified inspector for a pre-listing inspectionAmerican Society of Home Inspectors
- Fraud.org warned on June 1, 2023fraud.org
- MCL 339.2512gMichigan Legislature
- NAR reportedNational Association of Realtors
- NotedNational Association of Realtors
- EPA's real estate disclosure pageU.S. Environmental Protection Agency
- VA Home Loan Buyer's GuideU.S. Department of Veterans Affairs
- IRS Topic 701Internal Revenue Service
- IRS Publication 523Internal Revenue Service
- MCL 565.952Michigan Legislature
- MCL 565.953Michigan Legislature
- MCL 565.954Michigan Legislature
- MCL 565.955Michigan Legislature
- MCL 565.957Michigan Legislature
- MCL 565.960Michigan Legislature
- MCL 565.961Michigan Legislature
- 42 U.S.C. 4852dlaw.cornell.edu
- Fannie Mae Selling Guide B4-1.3-06Fannie Mae Selling Guide
- Mortgagee Letter 2024-13, Revisions to the 203(k) Rehabilitation Mortgage Insurance ProgramU.S. Department of Housing and Urban Development
- 38 CFR 36.4351law.cornell.edu
- 7 CFR 3555.202(b)law.cornell.edu
- Fair Housing Act, 42 U.S.C. 3604(c)law.cornell.edu
- Michigan Elliott-Larsen Civil Rights Act, MCL 37.2502Michigan Legislature
- National Association of REALTORS®National Association of Realtors
Related resources
20-minute read
How to choose a real estate agent: 7 steps to vet the right one
Learn how to choose a real estate agent using recent sales data, a comparative market analysis, license checks, and the red flags that signal a poor fit.
20-minute read
Real estate agent commissions: How they work now
Learn how agent commissions work, who pays each side after the 2024 NAR settlement, how the split is calculated, and where sellers can negotiate.
19-minute read
Pros and cons of seller financing for home sellers
Discover the pros and cons of seller financing, from interest income and a wider buyer pool to balloon payments, default risk, and installment-sale taxes.
