
What is net operating income (NOI)? The formula every investor uses
This article explains an investment metric and is general information only. It is not tax, legal or investment advice, and not an offer to sell or a solicitation to buy any security. Take depreciation and recapture questions to a qualified tax professional, and lease, title and entity questions to a Michigan attorney. Align Lending is an independent Michigan mortgage broker, not a commercial lender, broker-dealer, investment adviser, syndicator or property manager.
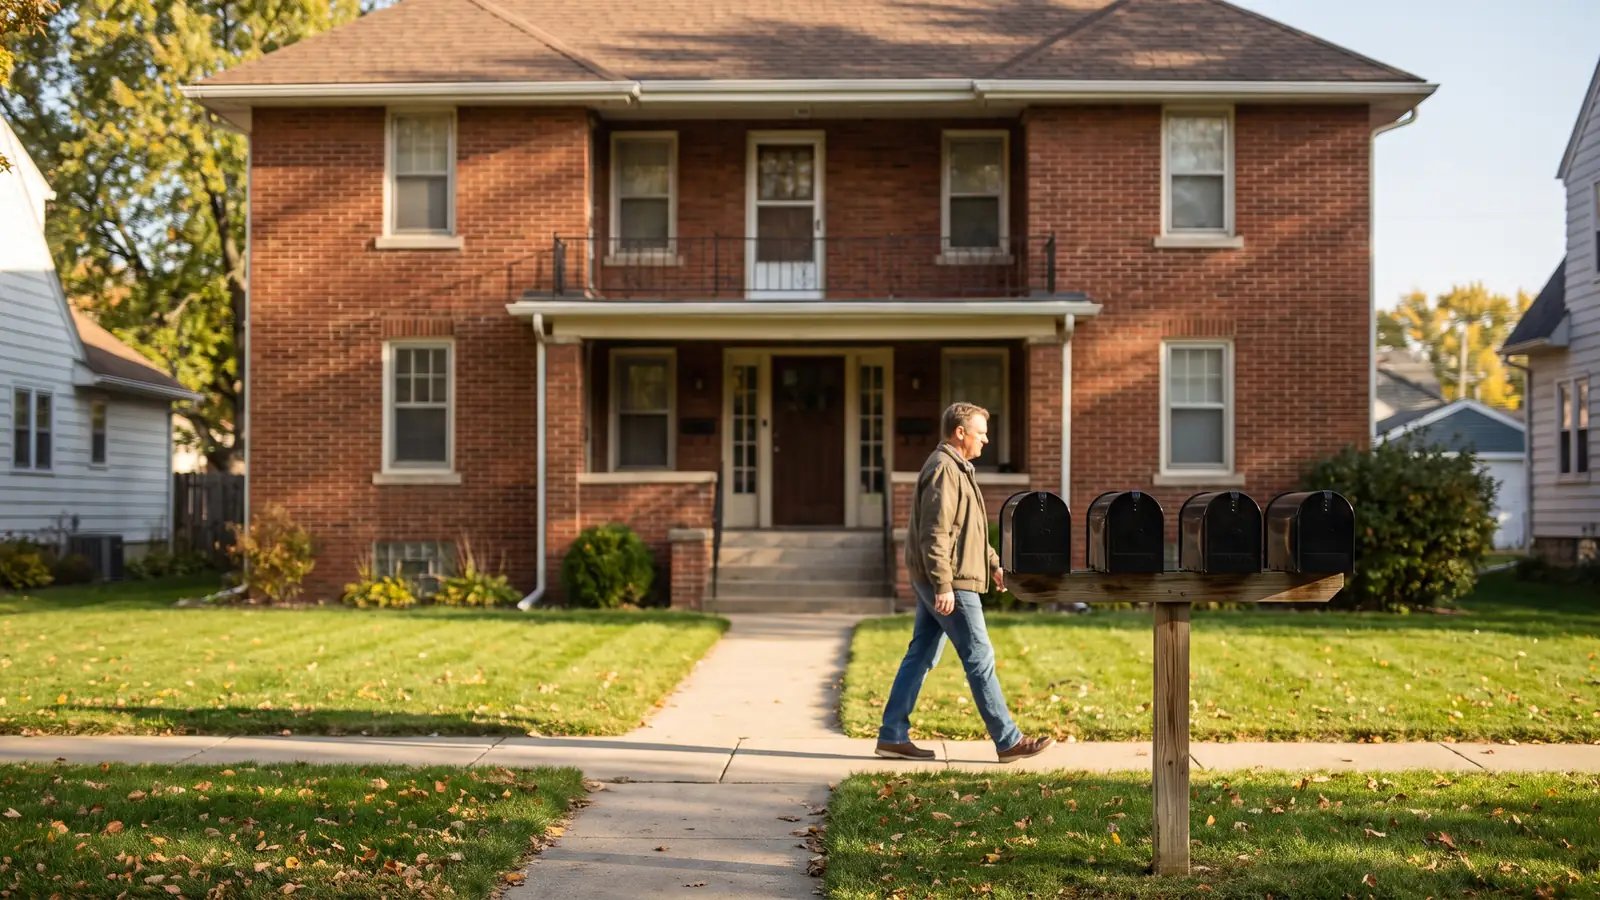
Net operating income is a property’s effective gross income minus its operating expenses. A fourplex that collects $60,000 after vacancy and spends $24,000 on property taxes, insurance, utilities, repairs and management has $36,000 of net operating income.
What the subtraction leaves out is the entire point. Your mortgage payment, your capital expenditures, depreciation and your income taxes never enter the calculation, so NOI measures the building rather than your deal.
Learn how net operating income (NOI) works: which lines belong on each side, how NOI sets value and loan size, and how a seller’s pro forma inflates it. New here? Start with our Real Estate Investing guide or the Investing Basics hub.
Key takeaways:
- Two subtractions, in that order: Vacancy and credit loss come out of gross income first, then operating expenses, $60,000 of effective gross income minus $24,000 of operating expenses is $36,000 of NOI.
- Four costs are excluded on purpose: Debt service, capital expenditures, depreciation (27.5 years for residential rental property under the IRS general depreciation system) and income taxes stay out, because they describe the owner rather than the building.
- NOI is the value lever: At a 6% market cap rate, every additional $1,000 of annual NOI adds roughly $16,667 to what an income property is worth.
What is net operating income?
Net operating income is the annual income a property produces after operating expenses and an allowance for vacancy and credit loss, but before financing, capital spending, depreciation and income taxes. It is the closest thing real estate has to a clean measure of the asset itself.
The definition works because of what it refuses to include. Two investors buying the identical fourplex (one paying cash, one borrowing 75%) compute the same NOI. Let a mortgage payment in and the number stops being comparable.
| Included in NOI | Excluded from NOI |
|---|---|
| Scheduled rent from all units | Mortgage principal and interest (debt service) |
| Other income: parking, laundry, storage, pet and application fees | Capital expenditures: roofs, furnaces, full unit rehabs |
| A deduction for vacancy and credit loss | Depreciation and amortization |
| Property taxes and insurance | Federal and state income taxes |
| Owner-paid utilities and common-area services | Loan fees, closing costs and entity fees |
| Repairs, maintenance, landscaping, snow removal | Owner-specific costs: travel, home office |
| Property management fees and leasing commissions | One-time items: a settlement, an insurance payout |
Read the right column twice. Debt service, capital expenditures, depreciation and income taxes are the four people get wrong.
How do you calculate NOI, step by step?
Three moves: build potential gross income, subtract vacancy and credit loss, then subtract operating expenses. Here is the walk on a hypothetical Waterford fourplex renting at $1,325 a unit.1
| Line | Amount | Note |
|---|---|---|
| Scheduled rent (4 units × $1,325 × 12) | $63,600 | Market rent, not a below-market rent roll |
| Other income (coin laundry, one garage) | $900 | Counted, and often forgotten |
| Potential gross income | $64,500 | The 100%-occupancy fantasy number |
| Less vacancy and credit loss (7%) | −$4,500 | Empty units plus rent never collected |
| Effective gross income | $60,000 | Where the expense side starts |
| Property taxes (non-homestead) | −$8,800 | Largest line in most Michigan rentals |
| Insurance | −$3,200 | Landlord policy, not a homeowner policy |
| Owner-paid heat, water, common-area electric | −$4,000 | Only what the lease leaves with you |
| Repairs and maintenance | −$2,600 | Fixing what exists, not replacing it |
| Property management (8% of EGI) | −$4,800 | Charged even if you self-manage |
| Landscaping and snow removal | −$600 | Seasonal contract, billed year-round |
| Net operating income | $36,000 | $60,000 minus $24,000 of expenses |
The vacancy line is the one most often set to zero, and the one with real data behind it. The national rental vacancy rate was 7.3% in the second quarter of 2026 per the U.S. Census Bureau, so a sheet assuming 12 collected months on every unit describes a market that does not exist.
That $24,000 against $60,000 is a 40% operating expense ratio. Practitioner benchmarks commonly quote a 35% to 45% band, and the 50% rule is the cruder cousin. Both are rules of thumb, not standards, and neither replaces the actual tax bill, insurance quote and utility history.2
Why does NOI exclude your mortgage, capex, depreciation and taxes?
Because all four describe the owner, not the property, and letting any of them in would break the comparison the metric exists to make. Each is still a real cost NOI ignores.
- Debt service is excluded first: Principal and interest never appear. That makes NOI portable between a cash buyer and a leveraged one, and makes it, alone, a terrible predictor of whether you can pay your bills.
- Capital expenditures are capitalized, not expensed: A furnace replacement is not a repair. The IRS draws the same line: you deduct amounts paid to repair and maintain rental property, but must capitalize an expense that betters, restores or adapts it. See the IRS list of deductible rental expenses.
- Depreciation is a tax entry, not a cash cost: Residential rental property is depreciated over 27.5 years under the IRS general depreciation system, and land is never depreciable. It changes your tax return every year and your NOI never.3
- Income taxes sit below the line: Your bracket, entity and passive-activity position have nothing to do with what the building earns.
A property with $30,000 of deferred roof and mechanical work shows the same NOI as an identical property with a new roof. NOI will not warn you; only an inspection and a capital reserve line in your own model will.
How does NOI decide what a property is worth?
Rearrange one equation: value equals NOI divided by the market cap rate. At a 6% cap rate, the $36,000 fourplex above is worth roughly $600,000, because $36,000 divided by 0.06 is $600,000. That is the income approach to value. Income property is priced on what it earns, not on what the neighbors sold for.
That is a lever a homeowner does not have. Every $1,000 of durable annual NOI is worth about $16,667 at a 6% cap rate, so raising rent $25 a month across 4 units ($1,200 a year) adds roughly $20,000 of value, while a $3,000 insurance increase removes about $50,000. The metric performing that conversion is the cap rate; NOI is the input it consumes.
The mechanism bites hardest above the four-unit line.
- One to four units is residential financing: Fannie Mae purchases or securitizes first-lien mortgages secured by residential properties when the dwelling consists of one to four units, and appraisers value those largely on comparable sales. Owner-occupants of 2- to 4-unit properties can also reach FHA and VA financing; non-occupant investors cannot. FHA then splits the property classes again: under HUD Handbook 4000.1 a self-sufficiency test applies to three- and four-unit properties, where the mortgage payment divided by net self-sufficiency rental income may not exceed 100%, and that test does not apply to a two-unit property.4
- Five or more units is commercial: Fannie Mae’s Multifamily Guide generally treats a stand-alone building of fewer than five dwelling units as not multifamily. At five units, the appraisal, the loan and the price all run on NOI, see investing in multi-family properties and commercial real estate investing.
- Commercial credit is not consumer credit: Under Regulation Z, credit extended primarily for a business purpose is exempt from the Truth in Lending Act. No Loan Estimate, no Closing Disclosure, and balloon maturities are normal. Align Lending finances 1- to 4-unit residential investment property; a 12-unit building belongs with a commercial lender.
How do lenders use NOI to size a loan?
Through the debt service coverage ratio: NOI divided by annual debt service. The $36,000 fourplex carrying $30,000 of annual principal and interest has a 1.20 ratio, operations cover payments 1.2 times over. Move NOI and the borrowable amount moves with it.
Coverage thresholds are published underwriting criteria, not folk numbers. In Mortgagee Letter 2025-2, issued January 8, 2025, HUD lowered the debt service coverage ratio for qualifying Middle Income Housing under FHA Section 221(d)(4) from 1.176 to 1.11 and raised loan-to-cost from 85% to 90%. Those figures govern only that program, but they show how directly coverage sets loan size.
On 1- to 4-unit property, the picture splits in two.
- Agency financing qualifies you, not the building: Conventional investment loans underwrite your personal debt-to-income ratio, counting part of documented rental income toward it. NOI informs your analysis; it is not the qualifying math.
- DSCR programs qualify the building: Non-agency investor loans size the deal on the property’s income against the payment, with no personal income calculation. Lenders in Align’s network offering them typically look for coverage of roughly 1.00 to 1.25 depending on the product, and pricing improves as coverage rises. Terms vary by lender and change often, so confirm current requirements before modeling them.
- Refinances run the same test: A property whose NOI has grown since purchase can often support more debt at the same coverage ratio, the arithmetic behind refinancing an investment property.
Why can a lender’s NOI come in lower than the seller’s?
Because a lender underwrites a stabilized NOI, not the owner’s actual year. The OCC’s Comptroller’s Handbook booklet on Commercial Real Estate Lending (version 2.0, March 2022), written for OCC examiners, says operating expenses do not include depreciation or capital items but do include a reserve for replacing capital items, and that this replacement reserve is imputed for underwriting purposes whether or not it is actually funded. The same booklet says the lender’s NOI analysis may assume vacancy above or below actual, and expenses that are not an actual or immediate cash cost, such as management fees.
A tax return is not a shortcut around that work. According to the same OCC booklet, recurring capital items such as heating and air conditioning systems, roofs and parking lots are captured in a replacement reserve rather than shown as an expense on the return, and a cash-basis return for a year in which property taxes went unpaid understates expenses and overstates income.
Hypothetical example, not an offer. Impute a replacement reserve of $250 per unit per year on the fourplex and underwritten NOI drops from $36,000 to $35,000. Against the same $30,000 of annual debt service, coverage falls from 1.20 to about 1.17, and the value at a 6% cap rate falls from $600,000 to about $583,333.
The OCC booklet also defines debt yield: NOI divided by the loan amount, expressed as a percent, which it describes as independent of the interest rate, amortization period and cap rate, with lower debt yields indicating higher leverage. For example, the fourplex’s $36,000 of NOI against a hypothetical $450,000 loan is an 8% debt yield. HUD’s insured apartment loans run several tests at once: as HUD’s January 8, 2025 Mortgagee Letter summarizes its Multifamily Accelerated Processing Guide, the loan is the lesser of the requested amount, the statutory limit, the amount supportable by debt service and the amount supportable by the loan ratios.
Credit conditions for larger buildings move as well. In the Federal Reserve’s July 2026 Senior Loan Officer Opinion Survey, a modest net share of banks reported easing standards over the second quarter for loans secured by multifamily properties, while demand for those loans was reported as basically unchanged. How rate changes run through these ratios is covered in how interest rates affect real estate investing, and the loan types themselves in financing investments.
How does Fannie Mae turn rent into qualifying income on a 1- to 4-unit loan?
Not with NOI. According to Fannie Mae’s Selling Guide topic B3-3.8-02, Rental Income from the Subject Property, dated September 2, 2026, the lender multiplies gross monthly rent by 75% to get net rental income, with the appraiser’s Form 1007 or Form 1025 supporting the gross rent. When the property already appears on your tax return, cash flow equals the net amount on Schedule E plus any depreciation, interest, homeowners’ association dues, taxes or insurance expenses, and the lender may add back non-recurring property expenses that are documented.
Hypothetical example, not an offer. The Waterford fourplex above, run both ways:
| Method | Starting figure | Monthly result |
|---|---|---|
| NOI (this article) | $60,000 of effective gross income less $24,000 of operating expenses, divided by 12 | $3,000 |
| Fannie Mae 75% factor | $5,300 of gross monthly rent × 0.75 | $3,975 |
Source: Fannie Mae Selling Guide B3-3.8-02 (September 2, 2026) for the 75% factor. Figures are a hypothetical example, not an offer.
The two numbers answer different questions. The 75% factor in B3-3.8-02 is a fixed cut applied to rent; NOI subtracts each actual bill, so a building with heavy owner-paid heat can show a much thinner NOI than its qualifying rent suggests. How rental income then sits against your payments is covered in our guide to debt-to-income ratio, the tax side of the add-backs in real estate depreciation, and the purchase itself in buying a multi-family home.
How does a seller’s pro forma NOI get inflated?
By quietly moving costs out of the operating column and income in. A pro forma projects what the seller says the property could earn, and every assumption in it was chosen by someone with an interest in a higher price.
- Vacancy set to zero or 2%: The most common edit. On $64,500 of potential gross income, moving the allowance from 7% to 2% manufactures $3,225 of NOI and about $54,000 of value at a 6% cap rate, from one spreadsheet cell.
- No management fee because the seller self-manages: Your time is not free, and an appraiser underwrites management anyway. Add 8% to 10% of effective gross income back in.
- Capital work reclassified as maintenance: A roof pushed into “repairs” understates capital need and overstates operations at once.
- Property taxes at the seller’s basis: In Michigan this is the largest recurring error, covered below.
- “Market rents” the property has never achieved: Pro forma rent is a forecast, not a fact. Verify it against signed leases, using the discipline in how to spot a good real estate deal.
Underwrite the trailing 12 months of collected income and paid expenses first, then build your own forward view. The gap between a pro forma and the real trailing numbers is where undervalued properties hide, and overpriced ones too.
How do you project NOI forward when rents and costs rise at different speeds?
Grow each line at its own rate, because rent and expenses rarely move together. According to the Bureau of Labor Statistics consumer price index table for September 2026, rent of primary residence rose 2.8% over the prior 12 months, while water, sewer and trash collection services rose 4.8% and utility (piped) gas service rose 5.0%. These indexes track what households pay, not landlord invoices, but they show which way each line is moving.
Heating is the line to model from several winters, not one. The U.S. Energy Information Administration says in its Winter Fuels Outlook for the 2026 to 2027 winter that its household heating forecasts are sensitive to weather conditions, which is why it publishes warmer and colder side cases beside its base case. Use the property’s own gas bills for at least two heating seasons before setting the line.
Hypothetical example, not an offer. Grow the fourplex’s $60,000 of effective gross income by 2.8% and its $24,000 of operating expenses by 4.8%, and next year’s NOI is $61,680 minus $25,152, or $36,528. NOI rose about 1.5%, not 2.8%, so at a 6% cap rate the building gained about $8,800 of value instead of the $16,800 that growing NOI at the rent rate would show.
Samantha put the principle plainly in an interview for this site: “I don’t love a deal that only works when nothing goes wrong.” Ways to research where local rents are heading are in analyzing rental market trends, and keeping the expense side in check is covered in rental management.
How is NOI different from cash flow, cap rate and cash-on-cash return?
NOI is the input; the rest are built on it. Confusing NOI with cash flow is the expensive mistake: a property can post a healthy $36,000 NOI and still hand you a negative number every month once the mortgage is paid.
| Metric | What it measures | Includes your mortgage? | Best used for |
|---|---|---|---|
| Net operating income | Effective gross income minus operating expenses | No | The building’s own earning power |
| Cash flow | NOI minus debt service, in dollars | Yes | What reaches your bank account |
| Cap rate | NOI divided by value, as a percentage | No | Comparing properties and pricing risk |
| Cash-on-cash return | Annual pre-tax cash flow divided by cash invested | Yes | What your dollars earn in year one |
| Debt service coverage ratio | NOI divided by annual debt service, as a multiple | Yes | How much debt the property carries |
Run them in that order. NOI sizes the asset, the cap rate prices it, then cash flow in real estate and cash-on-cash return tell you what the deal does for you. Past performance does not predict future results.
What Michigan investors should know
Two of the largest lines in a Michigan NOI change the day you close, and the seller’s tax bill will not warn you.
- You lose the principal residence exemption, up to 18 mills: It relieves an owner’s principal residence from up to 18 mills of local school operating millage, and the Michigan Department of Treasury states that income property is not occupied as a principal residence and may not claim it. Your rental pays a non-homestead rate the owner-occupant next door does not.
- Taxable value uncaps the year after you buy: Under Proposal A, a transfer of ownership uncaps taxable value in the calendar year following the transfer, and taxable value then equals the state equalized value, which under the Michigan Constitution cannot exceed 50% of true cash value. The seller may be taxed on a fraction of what you will be.
- Winter is an NOI line, not a surprise: In its Winter Fuels Outlook published October 15, 2025, the U.S. Energy Information Administration forecast Midwest households heating with natural gas would spend about $610 from November 2025 through March 2026, roughly 2% above the prior winter. Owner-paid heat lands straight in operating expenses, next to the snow contract.
- Rebuild the tax line before you offer: Ask the assessor for the state equalized value and the non-homestead millage rate, recompute taxes, then compute NOI. Occupancy is a lending question too. Calling an investment property your primary residence to get better loan terms is mortgage fraud, a federal crime. See buying a home as an investment property and the Treasury’s principal residence exemption page.
How do Michigan’s deposit, rent and assessment rules show up in NOI?
Three Michigan rules touch the income and tax lines directly, beyond the exemption and uncapping points above.
- Security deposits are held, not earned: MCL 554.602 caps a security deposit at one and a half months’ rent, and MCL 554.604 requires the deposit to be placed in a regulated financial institution, with the landlord free to use the money only after filing a cash bond or surety bond with the Secretary of State. A seller’s operating statement that counts deposits as income overstates NOI. For example, on a $1,325 unit the cap is $1,987.50 (hypothetical example, not an offer). Keeping part of a deposit is a process, not a bookkeeping entry: according to Michigan Legal Help’s overview of security deposits for landlords, the landlord has 30 days from the time the tenant moves out to return the deposit or send a list of damages, a landlord who sends no list in that time is treated as agreeing there is no damage, and the landlord has 45 days from move-out to file a court case for all or part of the deposit. Move-in duties are covered in becoming a landlord.
- The tax line can be appealed, on a fixed calendar: Under MCL 211.30, the local board of review meets on the second Monday in March, or the Tuesday or Wednesday after it if the city or township sets that date. Under MCL 205.735a, property classified as residential must be protested at the board of review before the Michigan Tax Tribunal takes the case, with a petition filed by July 31 of the tax year; commercial and industrial property files by May 31. Check the classification on your assessment notice. In the hypothetical fourplex, every $600 cut from the yearly tax bill adds $10,000 of value at a 6% cap rate. How assessors set the number is in how property tax assessments work.
- Pro forma rent can be checked against HUD’s county figures: HUD’s fiscal year 2027 Fair Market Rents file, published on its Fair Market Rents data page, set the two-bedroom figure at $1,459 for Oakland County (Detroit-Warren-Livonia HUD Metro FMR Area) and $1,630 for Kent County (Grand Rapids-Wyoming). Under 24 CFR 888.113, Fair Market Rents are estimates of rent plus the cost of utilities, except telephone, so take tenant-paid utilities out before comparing them with a contract rent like the fourplex’s $1,325.
Then rebuild the tax line with the Michigan property tax calculator, whose non-homestead (second home) setting uses the district’s published non-homestead rate, the rate a rental pays.
How Align finances investors
Samantha looks at the property's numbers before the loan's, and she says so plainly: "I don't love a deal that only works when nothing goes wrong."
Align places DSCR loans, which qualify on the rent the property brings in rather than your tax returns, as well as conventional investment loans, through multiple wholesale lenders.
FAQ: Net operating income
Here are answers to common questions about net operating income.
How do you calculate net operating income?
Start with potential gross income: scheduled rent plus other income such as parking, laundry or pet fees. Subtract a vacancy and credit-loss allowance to reach effective gross income. Then subtract operating expenses, taxes, insurance, owner-paid utilities, repairs, management and snow removal. What remains is NOI. The sequence for verifying each line is in real estate due diligence.
What is not included in NOI?
NOI excludes mortgage principal and interest, capital expenditures such as a new roof, depreciation, income taxes, loan and closing costs, and one-time or owner-specific items. Each depends on how a particular owner financed the deal, so removing them lets two buildings be compared on operating performance alone. The tax side is in real estate tax benefits for investors.
Why do lenders care about NOI?
Because loan size is set by the debt service coverage ratio: NOI divided by annual debt service. A property producing $36,000 of NOI against $30,000 of annual payments covers its debt 1.2 times. Raise NOI and it supports more debt; let NOI slip and the approvable loan shrinks. Start with analyzing a property’s rental potential.
Hypothetical example, not an offer. Actual rates, costs and payments vary.
How can I increase a property’s NOI?
Work both sides. Raise income by bringing below-market rents to market at turnover, cutting vacancy and adding storage, parking or pet income. Lower expenses by rebidding insurance, appealing the assessment and negotiating annual landscaping and snow contracts. At a 6% cap rate, $1,200 of added annual NOI is worth roughly $20,000. Work through evaluating a property’s cash flow potential next.
Is NOI calculated monthly or yearly?
Yearly, by convention. The OCC’s commercial real estate lending booklet defines NOI as annual gross income less operating expenses, and cap rates and debt yield are annual ratios. Monthly figures show up in qualifying math instead: under Fannie Mae Selling Guide B3-3.8-02, Schedule E cash flow is divided by a number of months to reach a monthly amount. Annualize seasonal lines such as snow removal and heat before you divide NOI by 12.
Is NOI the same as EBITDA?
No. EBITDA is a company-level earnings figure: it starts from a whole business’s profit, including corporate salaries, offices and other overhead, then adds back interest, taxes, depreciation and amortization. NOI is property-level and is built from one building’s rent roll and bills, so owner and entity costs never enter it. A company that owns ten buildings reports one EBITDA and can show ten separate NOIs.
What is the difference between NOI and net income?
Net income comes after financing and tax entries; NOI comes before them. On IRS Schedule E, per the 2025 Schedule E instructions, rents go on line 3, mortgage interest paid to banks on line 12, depreciation on line 18 and total expenses on line 20, and line 21 shows the income or loss. That line 21 figure has already subtracted interest and depreciation, so it usually sits well below the same property’s NOI.
Are security deposits included in NOI?
Not a deposit you plan to return: IRS Publication 527 (2025) says to leave it out of income. Any part you keep is income in the year you keep it. A deposit that will be used as the final month’s rent is advance rent, which counts as income when you receive it, and so does a tenant’s payment to cancel a lease. Treat kept deposits and lease-break payments as one-time items, not recurring NOI.
Is a loan on a 1- to 4-unit rental covered by the Truth in Lending Act?
Usually not when no owner lives there. The CFPB’s official interpretation of Regulation Z, comment 3(a)-4, deems credit to acquire, improve or maintain a rental property the owner does not occupy to be for business purposes, whatever the number of units. That does not apply if the owner expects to live there more than 14 days in the coming year. If the owner lives in one unit, comment 3(a)-5 deems a purchase loan business purpose above two units.
The bottom line on net operating income
Net operating income is effective gross income minus operating expenses: $60,000 minus $24,000 is $36,000 of NOI on the fourplex above. Vacancy and credit loss come out first; debt service, capital expenditures, depreciation and income taxes never come out at all, which makes the number comparable between two buildings and incomplete for your own deal. Because value equals NOI divided by the cap rate, every $1,000 of durable annual NOI is worth about $16,667 at a 6% cap rate, and every inflated pro forma line is worth the same in the wrong direction.
If you’re ready to see what your NOI supports on a 1- to 4-unit investment property, talk to Align Lending. We’ll shop your purchase or refinance across our lender network and show you the numbers side by side. Call 248-506-5727 or start online. Take depreciation questions to a qualified tax professional.
Footnotes:
1. Example figures are hypothetical and for educational purposes only; they do not constitute an advertisement of credit terms, a rate quote, an offer of credit, or a projection of investment returns under federal or state law. The $1,325 rent, the $63,600, $900, $64,500, $4,500, $60,000, $8,800, $3,200, $4,000, $2,600, $4,800, $600, $24,000, $36,000, $30,000, $1,200, $3,225 and $600,000 figures, the 7% vacancy allowance, the 8% management fee, the 6% cap rate and the 1.20 coverage ratio and every value derived from them at a 6% cap rate ($16,667, $20,000, $50,000 and $54,000) are Align Lending arithmetic shown to demonstrate the formulas. They do not describe any specific property, market, rate or loan, and no interest rate is stated or implied. Your actual income, expenses, taxes, insurance and financing will differ. Return to text.
2. The 35% to 45% operating expense band and the 50% rule are widely repeated practitioner rules of thumb, not statutory, regulatory or index-published standards, and neither carries predictive force. Operating expense ratios vary substantially by property age, unit count, utility structure, management arrangement, local tax rate and insurance market, and a well-run property can sit far outside the band for sound reasons. Benchmark data published by industry bodies such as the Institute of Real Estate Management is a starting point, never a substitute for the property’s actual bills. Past performance does not predict future results. Return to text.
3. This is general information, not tax advice. Depreciation recovery periods, the land-versus-improvement basis allocation behind any depreciation figure, the deductible-versus-capitalized treatment of a given expense, depreciation recapture on sale, passive-activity loss rules and entity choice all depend on your individual circumstances and change over time. Depreciation recapture applies to depreciation allowed or allowable, whether or not you claimed it. Consult a qualified tax professional about your situation. Align Lending is a mortgage broker and does not provide tax, legal or investment advice. Return to text.
4. Align Lending is not acting on behalf of or at the direction of FHA or HUD, works with VA-approved lenders, and is not endorsed or sponsored by the U.S. Department of Housing and Urban Development, the Federal Housing Administration, the U.S. Department of Veterans Affairs or any other government agency. FHA and VA financing require the borrower to occupy the property as a primary residence, so neither is available for a non-owner-occupied investment purchase; program requirements, including the FHA self-sufficiency test for three- and four-unit properties, are set by the agencies and change over time. Confirm current requirements with your loan officer before relying on them. Return to text.
Sources: national rental vacancy rate of 7.3% in the second quarter of 2026, U.S. Census Bureau, Quarterly Residential Vacancies and Homeownership, Housing Vacancies and Homeownership (CPS/HVS), released July 28, 2026. Deduction of amounts paid to repair and maintain rental property, the requirement to capitalize an expense that betters, restores or adapts the property, the list of common deductible rental expenses, the 27.5-year recovery period for residential rental property under the general depreciation system, and the statement that the cost of land cannot be depreciated, Internal Revenue Service Publication 527, Residential Rental Property. Revision of underwriting thresholds for Middle Income Housing under FHA Section 221(d)(4), lowering the debt service coverage ratio for new construction and substantial rehabilitation from 1.176 to 1.11 and raising loan to cost from 85% to 90%, U.S. Department of Housing and Urban Development, Mortgagee Letter 2025-2, January 8, 2025. Treatment of a stand-alone building containing fewer than five dwelling units as not a Multifamily Property, subject to stated exceptions for buildings originally constructed as part of a single multifamily development or sharing a tax parcel with other multifamily properties, Fannie Mae Multifamily Selling and Servicing Guide. Exemption of credit extended primarily for a business, commercial or agricultural purpose from the Truth in Lending Act, Regulation Z, 12 CFR 1026.3(a). Principal residence exemption from the local school operating millage of up to 18 mills, and the statement that vacation homes, seasonal homes and income property are not occupied as a principal residence and may not be claimed, Michigan Department of Treasury, Principal Residence Exemption. Uncapping of taxable value in the calendar year following a transfer of ownership, with taxable value becoming the state equalized value, Michigan Department of Treasury, Changes in Ownership and Uncapping of Property, and MCL 211.27a. Assessment at not more than 50% of true cash value, Michigan Constitution of 1963, Article IX, Section 3. Forecast that Midwest households heating with natural gas would spend about $610 from November 2025 through March 2026, approximately 2% more than the prior winter, U.S. Energy Information Administration, Winter Fuels Outlook 2025 to 2026, published with the Short-Term Energy Outlook, October 15, 2025. Purchase or securitization of first-lien mortgages secured by residential properties when the dwelling consists of one to four units, Fannie Mae Selling Guide B2-3-01, General Property Eligibility. Self-sufficiency test for three- and four-unit Properties, under which the Mortgage Payment divided by monthly Net Self-Sufficiency Rental Income may not exceed 100%, and the calculation of Net Self-Sufficiency Rental Income by subtracting the greater of the Appraiser’s vacancy and maintenance estimate or 25% of fair market rent, U.S. Department of Housing and Urban Development, Single Family Housing Policy Handbook 4000.1. The 35% to 45% operating expense band and the 50% rule are drawn from general real estate investing literature and are presented as rules of thumb only.
This article is for informational purposes only and is not intended to provide legal, financial, tax or investment advice, and it is not an offer to sell or a solicitation of an offer to buy any security. Operating expenses, vacancy rates, cap rates, tax rules, millage rates, assessment practices and loan program requirements change and vary by property, program and locality; confirm current figures with your loan officer, confirm tax treatment with a qualified tax professional, and confirm assessment, entity and lease questions with a Michigan attorney. Figures shown are illustrative, are not a rate quote or an offer of credit, and do not constitute an advertisement of credit terms or a projection of investment returns. Past performance does not predict future results. Align Lending is an independent Michigan mortgage broker, NMLS #2041154, and is not a commercial lender, broker-dealer, investment adviser, syndicator or property manager.
Sources
Every outside source this guide links to, in the order it appears. How we choose and check sources
- U.S. Census Bureau
- IRS list of deductible rental expensesInternal Revenue Service
- Fannie Mae purchases or securitizesFannie Mae Selling Guide
- Fannie Mae’s Multifamily Guidemfguide.fanniemae.com
- Under Regulation ZElectronic Code of Federal Regulations
- Mortgagee Letter 2025-2, issued January 8, 2025U.S. Department of Housing and Urban Development
- Comptroller’s Handbook booklet on Commercial Real Estate Lendingocc.treas.gov
- July 2026 Senior Loan Officer Opinion SurveyFederal Reserve Board
- Selling Guide topic B3-3.8-02, Rental Income from the Subject PropertyFannie Mae Selling Guide
- Consumer price index table for September 2026bls.gov
- Winter Fuels Outlook for the 2026 to 2027 wintereia.gov
- The Michigan ConstitutionMichigan Legislature
- Winter Fuels Outlook published October 15, 2025eia.gov
- Principal residence exemptionState of Michigan
- MCL 554.602Michigan Legislature
- MCL 554.604Michigan Legislature
- Michigan Legal Help’s overview of security deposits for landlordsmichiganlegalhelp.org
- MCL 211.30Michigan Legislature
- MCL 205.735aMichigan Legislature
- Fiscal year 2027 Fair Market Rents fileHUD Office of Policy Development and Research
- Fair Market RentsHUD Office of Policy Development and Research
- 24 CFR 888.113Electronic Code of Federal Regulations
- 2025 Schedule E instructionsInternal Revenue Service
- Official interpretation of Regulation Z, comment 3(a)-4Consumer Financial Protection Bureau
- MCL 211.27aMichigan Legislature
Related resources
13-minute read
Buying a home as an investment property: A step-by-step guide
Learn how buying a home as an investment property works, from 15%+ down payments and financing options to ROI math, so your first rental starts profitable.
13-minute read
Real estate appreciation: How property values grow and why it matters
Learn how real estate appreciation works, why U.S. homes have averaged roughly 3% to 5% a year, and how forced appreciation can add to returns.
20-minute read
1031 exchanges: Rules, deadlines and benefits for investors
Learn how a 1031 exchange defers capital gains tax, why the 45-day and 180-day deadlines are absolute, and which properties qualify as like-kind.
