
Avoiding common home inspection pitfalls: Mistakes that cost buyers money
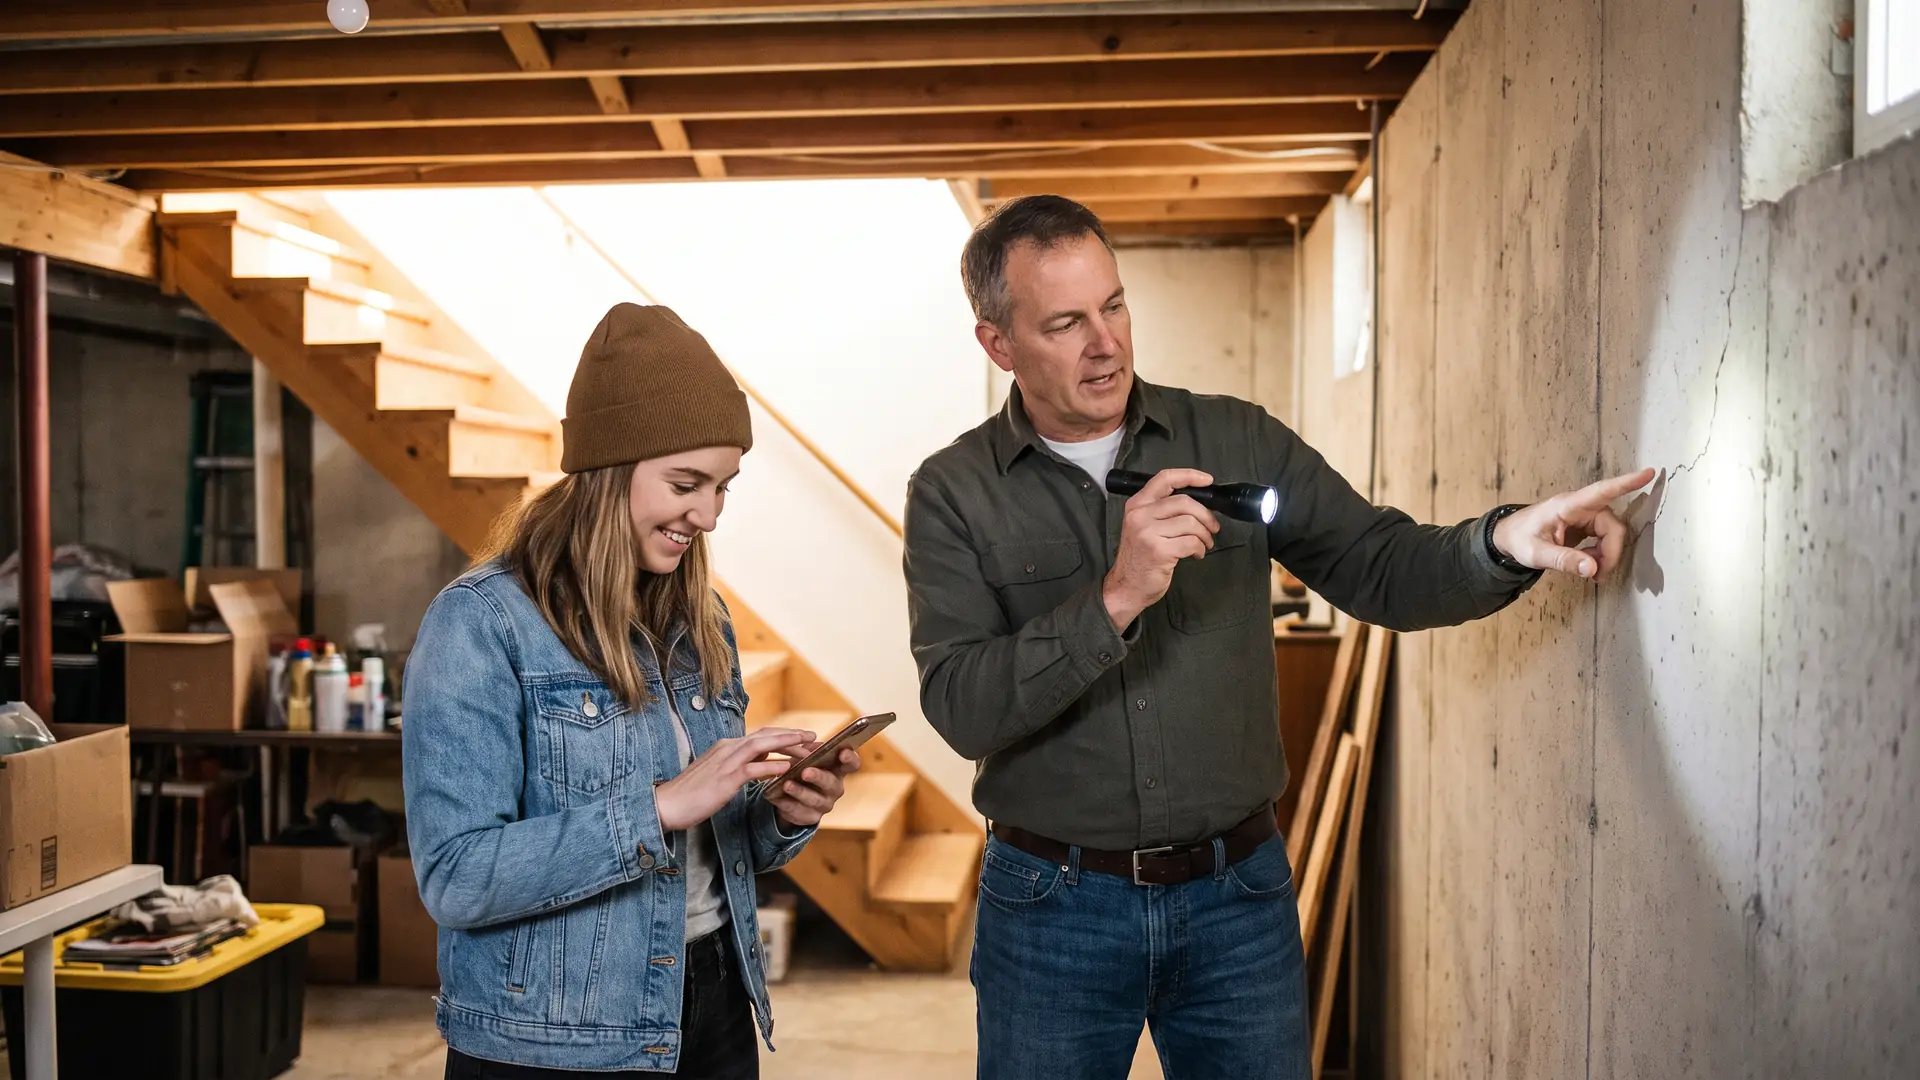
The five costliest home inspection pitfalls are hiring an unvetted inspector, skipping the walkthrough, leaving attics and crawl spaces blocked, misreading the report, and mishandling the negotiation that follows. A general home inspection typically runs about $300 – $500, which is small money next to the five-figure repair bill an overlooked foundation, roof, or electrical problem hands you after closing.
These mistakes are expensive because nobody else in the transaction is checking the house for you. Your appraiser is estimating value for your lender. Your agent isn’t licensed to evaluate a furnace. The inspection is the one step that exists to tell you what you’re actually buying.
Learn how to avoid common home inspection pitfalls, including how to vet an inspector, what to do while the inspection is happening, and how to turn the report into a repair negotiation. If you’re earlier in the process, start with our Home Buying guide.
Key takeaways:
- Vetting the inspector matters more than the price: Confirm certification through ASHI or InterNACHI, read a full sample report, and check reviews before you hire. A $300 – $500 inspection is the cheapest due diligence in a six-figure purchase.
- Attend at least the final hour: Watching an inspector explain a finding in person tells you more about severity than the report does, and it’s your chance to ask the 2 questions the standards don’t require them to answer: how bad is it, and what will it cost?
- Negotiate 4 categories, not 40 line items: Structure, roof, major systems, and health or safety findings are worth pushing on; the routine maintenance list every house generates is not.
How do you choose the right home inspector?
Choose on credentials and a sample report, not on price. A $75 gap between two quotes is meaningless next to the gap between an inspector who crawls the crawl space and one who photographs the hatch. HUD’s buyer notice tells you how to screen: “ask the prospective inspector for their Standards of Practice (SOP) or for a sample home inspection report.”
- Certification: Look for a current credential from the American Society of Home Inspectors (ASHI) or an inspector who meets InterNACHI’s inspector certification standards. Both publish a standard of practice defining the minimum scope of a general inspection.
- A full sample report: Ask for a complete recent report, not a summary page. You want photographs, a severity rating on each finding, and specifics, “no visible drip leg on the gas line at the furnace,” not “plumbing appears serviceable.”
- Licensing: Home inspector licensing is set at the state level. HUD’s notice points buyers toward “local licensing authorities and organizations that qualify and test home inspectors”. Check whether your state has one.
- Experience with this kind of house: A century-old home, a rural property on well and septic, and a first-year new build are three different inspections. Ask how many of your property type they did last year.
Don’t hire off one recommendation. HUD advises gathering references from friends, real estate professionals, and licensing bodies, so get two names beyond your agent’s and compare sample reports.
One thing your inspector is not: your appraiser. HUD’s notice puts it in capital letters. “Appraisals are NOT Home Inspections!”, and states that FHA does not perform home inspections or guarantee the condition of the home.1 The home appraisal process answers one question: what is this property worth? Our guide to how to choose a home inspector covers interview questions and pricing.
Pitfall: skipping the inspection walkthrough
Skipping the walkthrough is the most common pitfall and the easiest to fix, show up for at least the final hour. The report tells you what was found. Standing in the basement while someone points a flashlight at it tells you how bad it is.
There’s a structural reason to ask in person. ASHI’s standard says an inspector isn’t required to determine the remaining life expectancy of systems and components, or the methods, materials, and costs of corrections. That’s scope, not evasion, but most inspectors will talk it through on site.
- “How serious is this, honestly?”: Ask them to sort findings into safety, expensive, and eventual. That ranking is your negotiation plan.
- “How much life is left in it?”: Roof, furnace, water heater, and service panel are the 4 items where a replacement date changes your budget.
- “What couldn’t you get to?”: Note every limitation out loud so you can decide whether to send a specialist.
- “Where are the shutoffs?”: Main water valve, gas shutoff, panel, and furnace filter.
Bring the home inspection checklist for buyers, take your own photos, and note the room each came from. When the report lands, your notes make it readable.
Pitfall: blocked access and bad timing
An inspector who can’t reach something doesn’t inspect it, and the report says so in language that’s easy to skim past. InterNACHI’s standards are explicit: the inspector isn’t required to move obstructions such as furniture, carpeting, snow or debris, enter unsafe areas, or operate systems that have been shut down.
Temperature is a scope limit too. Under InterNACHI’s standard, an inspector isn’t required to operate equipment when the exterior temperature is below 65°F. Which is how a cooling system goes untested on a cold spring morning.
- Attic and crawl space access: Ask the listing agent in writing to have the attic hatch and crawl space entry clear. Boxes in front of an access panel are a finding you’ll never see.
- Panels and mechanicals: The electrical panel, furnace, and water heater need clear working space. A shelving unit against the panel means no panel inspection.
- Utilities on: On vacant, bank-owned, or estate properties, confirm water, gas, and electric are live before the inspector arrives. A shut-off house produces a report full of blanks.
- Weather and season: Snow on a roof or frozen ground over a septic field narrows the inspection. Note what got skipped and schedule a second look.
Timing is the other half. Schedule in the first days of your contingency window, not the last, you need room for a specialty inspection, contractor quotes, and a written response. Our guide to contingencies in home offers explains what each clause protects, and the home buying process guide shows where inspection falls in the sequence.
Pitfall: misreading the inspection report
A 40-page report with 60 findings is normal, and it is not a verdict on the house. Your job is triage: separate defects that cost real money or create a safety problem from the maintenance list any home would generate. Buyers lose both ways: walking away over cosmetics, or waving through a roof because it was item 47.
| Finding category | Worth negotiating | Usually routine maintenance |
|---|---|---|
| Structure and foundation | Active movement, stair-step cracking, sagging beams or posts | Hairline settlement cracks, no displacement or moisture |
| Roof | Active leaks, damaged decking, flashing failure, end of service life | A few lifted shingles, clogged gutters, a loose downspout |
| Electrical | Knob-and-tube or aluminum branch wiring, double-tapped breakers, ungrounded circuits | Missing outlet covers, a dead fixture, reversed polarity |
| Plumbing and sewer | A collapsed or root-blocked sewer lateral, active supply leaks, failing galvanized pipe | A dripping faucet, a running toilet, a slow drain |
| HVAC and water heater | A cracked heat exchanger, no combustion air, equipment past service life | A dirty filter, a missing filter door, a dirty coil |
| Water and moisture | Active seepage, grading sloped toward the foundation, a failed sump pump | Efflorescence with no active moisture, a disconnected downspout |
Put numbers on it before you react. Say the report flags a 22-year-old furnace at the end of its service life plus 31 smaller items. A contractor quotes $6,400 for the furnace. That figure is your negotiation. The 31 smaller items might total $400 and one Saturday.2
Read every summary bullet back to its detail page, the summary compresses severity out of the finding. Our guide to how to read a home inspection report walks through the rating language inspectors use.
What a home inspection can’t see
A general inspection is limited by design. InterNACHI describes it as a non-invasive, visual examination of the accessible areas of a residential property. ASHI’s standard covers readily accessible systems and components, states the inspection is not technically exhaustive, and doesn’t require identifying concealed conditions or latent defects. Both exclude mold, pests, lead paint, and asbestos.
Specialty inspections close that gap, and the time to order them is your general inspection window.
- Sewer scope: A camera run to the main is the only way to see the lateral. On a home with mature trees or clay-era piping, it’s the highest-value add-on you can buy.
- Radon test: EPA and the Surgeon General recommend that all houses be tested, and EPA’s action level is 4 pCi/L at or above that reading, EPA recommends fixing the home. See EPA’s guidance on radon testing.
- Lead-based paint on pre-1978 homes: Under the federal Real Estate Notification and Disclosure Rule, Section 1018 of Title X, sellers of pre-1978 housing must disclose known lead-based paint and hazards and give buyers a 10-day period to conduct a paint inspection or risk assessment. You can waive it. On an older home, don’t.
- Pests, well, septic, and chimney: Wood-destroying insect inspections are standard in much of the country. Water testing, a septic pump-and-inspect when you’re buying a home with a septic system, and a chimney scan each need their own specialist.
Pitfall: mishandling the repair negotiation
You have four moves after a rough report, and choosing one before you have a written quote is the mistake.
- Request repairs: Best for safety items and anything a lender or insurer may flag. The trade-off is that you inherit the seller’s contractor and their motivation to do it cheaply.
- Ask for a closing-cost credit: You control the contractor and timing, and the money reduces your cash to close. Credits are capped by loan program and by what the appraised value supports, so run the number past your loan officer.
- Ask for a price reduction: Cleanest when the defect is large and permanent. It lowers your loan amount and payment, but puts no cash in your pocket at closing.
- Walk away under the contingency: The reason you kept the clause. Miss the deadline and the option closes.
Bring written contractor quotes. A seller’s agent can argue with a buyer’s opinion of a roof; a bid from a licensed roofer is harder to dismiss. Our guide to negotiating repairs after a home inspection covers how to write the request, and home purchase contingencies explains what your clause lets you do.
Tell your loan officer the same day. Lenders in Align’s network sometimes condition final approval on repairs the appraiser flags too, and a repair addendum or a moved closing date can affect your rate lock. Our guide to preparing for a home closing shows what a compressed timeline demands.
If you’re selling as well as buying, the same problem runs in reverse, and getting ahead of it is cheaper. Read the benefits of a pre-listing home inspection before you list a house with unknown defects.
How Align moves your purchase to the closing table
Over the last 12 months, Samantha's loans averaged under 14 days from application to clear to close, across more than 100 loans. Your closing date is set by your purchase agreement. Her job is to have your loan ready well before it.
She handles your file herself, with a processor supporting her behind the scenes. You always know who to call, and the person who answers knows your goals.
Build your homebuyer game plan
Sources: Align Lending loan records, 12 months to October 2026.
FAQ: Common home inspection pitfalls
Here are answers to common questions about home inspection pitfalls.
What is the biggest mistake buyers make with home inspections?
The biggest mistake is treating the inspection as a formality. That shows up as hiring the cheapest inspector without checking credentials, skipping the walkthrough, or waiving the inspection entirely to win a bidding war. Any of those can leave you owning five-figure problems, foundation movement, roof failure, outdated wiring, that a qualified inspector would have found and you could have negotiated. Before you drop the clause to compete, read our guide to home inspection waivers: risks and benefits.
Should buyers attend the home inspection?
Yes, at least for the final hour. Attending lets you see problems in context, ask which findings are serious versus routine, and learn the home’s systems. Where the shutoffs, panels, and filters are. Buyers who only read the written report tend to overreact to minor notes and underreact to expensive ones. The same rule holds on a brand-new build, where the walkthrough is the entire point, see home inspections for new construction.
What do home inspectors commonly miss?
Inspections are visual and non-invasive, so inspectors can miss what’s behind walls, under carpet, or blocked by stored items. Plus anything they can’t safely reach, like a locked attic or a tight crawl space. Sewer lines, chimney interiors, and pest, mold, or radon issues need specialty inspections. Ensuring full access and adding targeted specialty inspections closes most of the gap. Our home inspection checklist for buyers lists what a general inspection does cover.
What should you do after a bad inspection report?
It depends on what’s on the list, so prioritize before you react. Get contractor quotes on the major items, then decide whether to request repairs, ask for a credit or price reduction, or walk away under your inspection contingency. Focus on health, safety, structural, and systems issues; a long list of minor items is normal and rarely worth a standoff. If the seller agrees to repairs, our guide to managing home repairs during escrow covers verifying the work before closing.
The bottom line on home inspection pitfalls
Avoiding common home inspection pitfalls comes down to five decisions. Hire on credentials and a sample report rather than on a $300 – $500 price tag. Attend at least the final hour and ask how serious each finding is. Make sure the attic, crawl space, panel, and mechanicals are accessible and the utilities are on. Read the report as triage, separating the four categories that cost real money, structure, roof, major systems, and health or safety, from routine maintenance. Then negotiate with written quotes, inside your contingency window.
If you’re ready to buy with your eyes open, talk to Align Lending, we’ll shop your scenario across our lender network and keep your financing on schedule while you work through inspection findings. Call 248-506-5727 or start online today.
Footnotes:
1. Align Lending is not acting on behalf of or at the direction of FHA or HUD. Statements about FHA appraisals and home inspections reflect HUD’s buyer notice “For Your Protection: Get a Home Inspection” (form HUD-92564-CN) and are subject to change. Return to text.
2. Example figures are hypothetical and for educational purposes only; they do not constitute an advertisement of credit terms or a rate quote under federal or state lending laws. Repair costs, inspection fees, and any credit or price reduction a seller agrees to depend on the property, the contractors you hire, your purchase agreement, and market conditions. Return to text.
Sources: inspection cost range of $300 – $500, Angi home inspection cost data. “Appraisals are NOT Home Inspections,” FHA not performing home inspections, and the advice to request an inspector’s standards of practice, sample report, and references, HUD form HUD-92564-CN. Non-invasive visual scope, exclusions for obstructions and shut-down systems, and the 65°F limit on operating equipment, InterNACHI Standards of Practice. Readily accessible scope, the “not technically exhaustive” limit, and exclusions for remaining life expectancy and concealed conditions, ASHI Standard of Practice. Radon action level of 4 pCi/L, U.S. EPA. Lead-based paint disclosure and the 10-day inspection period on pre-1978 housing, Section 1018 of Title X.
This article is for informational purposes only and is not intended to provide legal, financial, or tax advice. Purchase agreement language, inspection contingencies, disclosure obligations, and repair addenda should be reviewed by a licensed real estate professional or attorney in your state. Figures shown are illustrative, are not a rate quote or an offer of credit, and are subject to change. Align Lending is an independent Michigan mortgage broker, NMLS #2041154.
Related resources
12-minute read
The Home Appraisal Process: What to Expect
Learn how the home appraisal process works, from the lender’s order to the final report, including typical costs of $300-$1,500 and what appraisers check.
12-minute read
Home inspection checklist for buyers: What to look for room by room
See the complete home inspection checklist for buyers, from foundation to attic, so you can spot costly problems before you close on your next home.
12-minute read
How to prepare for a home closing: your step-by-step checklist
Learn how to prepare for a home closing with a step-by-step timeline, documents to bring, and final walk-through tips for a smooth closing day.
