
Zoning regulations: How they limit what you can build, add or run at home
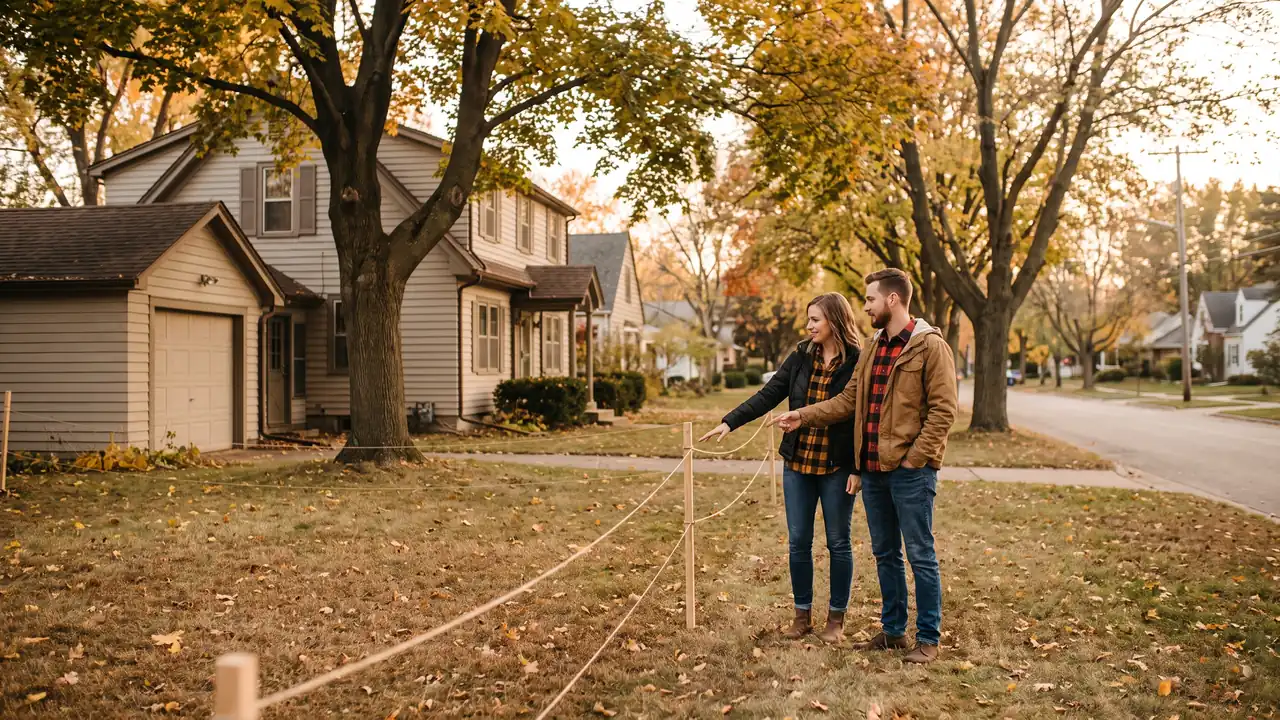
Zoning regulations are local laws that decide how a specific parcel of land can be used and what can be built on it. They reach your mortgage more directly than most buyers expect: Fannie Mae’s Selling Guide requires the appraiser to sort every property into one of exactly four zoning categories (legal conforming, legal non-conforming (grandfathered), an illegal use, or no local zoning at all) a rule carried in Selling Guide topic B4-1.3-04, last updated June 4, 2025.
Communities sort land into base districts (residential (R), commercial (C), industrial (I), agricultural (A) and mixed-use (MU)) then layer on rules for setbacks, height, lot size and density. Houston is the notable holdout: its Planning and Development Department says plainly that the city “does not have zoning.” Here’s how the rest of it works, what the district codes mean, which rules decide how much house fits on your lot, and how a non-conforming classification shows up in underwriting.
Key takeaways:
- Zoning is local, and Michigan hands it to four kinds of government: Counties, townships, cities and villages each write their own ordinances under the Michigan Zoning Enabling Act, 2006 PA 110, effective July 1, 2006, so two homes a mile apart can face different restrictions.
- Dimensional rules, not lot size, decide what you can build: A Michigan ordinance can regulate a structure’s location, height, bulk, number of stories, use and size, six levers under MCL 125.3201(4), so a large parcel doesn’t guarantee room for an addition.
- The two escape hatches carry different standards: A dimensional variance needs “practical difficulties” and a simple majority of the zoning board of appeals; a use variance needs “unnecessary hardship” and a 2/3 vote, and Michigan townships and counties can grant one only if their ordinance expressly authorized use variances as of February 15, 2006 or they granted one before that date.
What are zoning regulations?
Zoning regulations are the section of local law that divides a community into districts and sets what may be built and done in each one. They come from your city, village, township or county, not from Washington, though the state grants the authority. In Michigan, that grant is the Michigan Zoning Enabling Act, which defines a “local unit of government” as exactly four things: a county, a township, a city or a village.1
Zoning does three jobs: it separates uses that don’t mix well, controls the intensity of development, and makes public services plannable. So the ordinance governs both use. Whether a parcel can hold a house, a duplex, a shop or a farm, and whether home occupations, short-term rentals and accessory dwelling units are allowed, and dimension, meaning how big, how tall and how close to the property line.
Ordinances change constantly, so read the current code rather than a summary. Our Industry Updates & Rules hub tracks the rule changes that move fastest.
What do the zoning district codes mean?
The label on the zoning map (R-1, C-2, MU) tells you which rules apply: the letter is the district family and the number is usually the intensity, so R-1 is typically the lowest-density residential district and the numbers climb from there. Labels vary between municipalities, so read the district’s own section of the code.
| District family | Typically permitted | Commonly prohibited or restricted | What to check before you buy |
|---|---|---|---|
| Residential (R) | Houses; duplexes and multifamily in higher-numbered R districts; home occupations | Retail, commercial vehicle parking, often ADUs and short-term rentals | Whether an ADU, home office or rental is allowed outright, conditionally, or not at all |
| Commercial (C) | Retail, offices, restaurants, services; upper-floor apartments | Heavy manufacturing, outdoor storage, sometimes ground-floor residential | Whether a live-work unit counts as residential for financing |
| Industrial (I) | Manufacturing, warehousing, distribution, contractor yards | New dwellings almost everywhere | Whether an existing house is legal non-conforming, and could be rebuilt |
| Mixed-use (MU) | Residential and commercial in one building or block | Auto-oriented and industrial uses; sometimes single-story buildings | The share of commercial square footage, which some loan programs limit |
| Agricultural (A) | Farming, livestock, farm dwellings; large lot minimums | Subdividing below the minimum parcel size | Whether the parcel can be split, and how nearby farm operations are protected |
| Special purpose and overlays | Historic districts, planned unit developments, waterfront and floodplain overlays | Exterior alterations without review; building in regulated setbacks | Whether an overlay adds a second approval on top of the base district |
Overlays are the piece buyers miss most often. A parcel can sit in an ordinary R-1 district and still fall under a historic or shoreline overlay controlling siding, windows or how close you can build to the water.
These rules also shape what a property is worth, because they cap what any future owner could do with it, our guide to the impact of zoning laws on home value covers how classification feeds into appraised value.
Which zoning rules decide how much house fits on your lot?
Five dimensional rules do most of the work, and you have to satisfy all of them at once. That’s why acreage alone tells you almost nothing about whether an addition will fit.
- Setbacks: The minimum distance a structure must sit from front, side and rear property lines. Corner lots often carry two front setbacks.
- Lot width and area minimums: The smallest lot the district accepts. These decide whether a parcel can be split and whether an undersized lot is buildable.
- Height and stories: A feet limit and a story limit can both apply, measured from a grade point the ordinance defines.
- Lot coverage: The share of the lot structures may cover. A detached garage, covered porch and shed usually count against it.
- Density: Dwelling units allowed per acre. The rule that decides whether a second unit is possible.
- Easements: Not zoning, but they bind the same land. A utility or drainage easement can make part of the envelope unusable even when setbacks allow it.
Here’s the arithmetic buyers skip. On a 60-foot-wide lot with 10-foot side setbacks, ten feet on each side leaves a 40-foot building envelope, so a 44-foot-wide house plan doesn’t fit no matter how deep the lot is.2 The same math kills garage additions after the purchase agreement is signed.
How does zoning affect a home purchase or sale?
Zoning hits a transaction in four places: what you can legally do with the property, what a lender will finance, what the appraiser reports, and what you must disclose as a seller. Verifying it takes four steps that fit inside a normal inspection period.
- Pull the zoning map. Most planning departments publish the map and full ordinance online. Search by address or parcel number for the district label.
- Read that district’s section of the code. Don’t stop at the label. Check permitted uses, special land uses, and the dimensional table.
- Request written confirmation. Many municipalities issue a zoning verification letter for a small fee, and a letter beats a phone call you can’t produce later.
- Tell your lender what you found. If there’s a non-conforming use, an unpermitted addition or a second unit, say so before the appraisal, not after.
Renovation plans get the same treatment. Zoning approval and a building permit are different things, and the zoning question is generally settled first, our guide to home renovation permits walks through the sequence. If you’re selling and earlier work was never permitted, read how to sell a home with unpermitted work first; the fix is cheaper before an appraiser flags it.
How does zoning affect your mortgage approval?
It reaches your loan through the appraisal. Under Fannie Mae’s Selling Guide, the appraiser must report the zoning class plus a general statement of what that zoning permits, then indicate whether the property is a legal conforming use, a legal non-conforming (grandfathered) use, an illegal use, or has no local zoning. You can read the requirement in Fannie Mae Selling Guide topic B4-1.3-04.
- Legal conforming: The property complies with current zoning. This is the baseline.
- Legal non-conforming: Lawful when built, but no longer matching the district. Fannie Mae will still buy the loan, provided the appraisal reflects any adverse effect the status has on value and marketability.
- Illegal use: The use never complied. For an accessory dwelling unit zoning doesn’t allow at all, Fannie Mae adds conditions among them, at least three settled sales, two sharing the same non-compliant zoning use.
- No local zoning: No ordinance exists, as in Houston, so the analysis leans on market evidence.
One restriction catches waterfront buyers: Fannie Mae will not purchase a loan on a property subject to land-use regulations, such as coastal tideland or wetland laws, that create setback lines preventing the improvements from being rebuilt if damaged. Because most conventional loans follow Fannie Mae and Freddie Mac guidelines, those guidelines decide which zoning quirks are financeable, our explainer on how Fannie Mae and Freddie Mac stabilize the housing market covers why the two carry so much weight.
Zoning shapes the market you’re borrowing into, too. Restrictive districts limit how much new housing a metro can build, tightening supply, one of the slow structural forces behind our Mortgage Rates & Market guide. That plays out over decades, not quarters.
What are non-conforming uses, variances and rezonings?
These are the four ways a property escapes the strict letter of the code, and they aren’t interchangeable: one is inherited, two are exceptions, and one changes the law itself.
- Legal non-conforming use: A use that was lawful before the ordinance changed may continue, which Michigan codifies in MCL 125.3208(1). The catch is rebuilding: under MCL 125.3208(2), whether a non-conforming structure may be restored, reconstructed or extended depends on terms the local ordinance provides. It isn’t automatic.
- Variance: Permission to deviate from one requirement on one parcel. A dimensional variance covers setbacks and height; a use variance permits a use the district bans, and it’s a far heavier lift.
- Rezoning: A legislative change to the district classification itself, judged on planning merit rather than your personal hardship.
- Special land use approval: Also called a conditional use permit, used when the ordinance contemplates the use but requires case-by-case review.
What zoning can and can’t control
Zoning controls land use, not price, and in Michigan that line is statutory. Under MCL 123.411 (1988 PA 226, as amended by 2018 PA 585 effective March 28, 2019) a Michigan local government may not enact, maintain or enforce an ordinance controlling the amount of rent charged for leasing private residential property. Communities keep their zoning, licensing and inspection powers; they just can’t set rents. Our explainer on rent control covers how that preemption compares with other states.
Zoning also can’t override certain protected residential uses. Michigan’s zoning act treats a state licensed residential facility, and for counties and townships a family child care home, as a residential use permitted in all residential zones, and not subject to a special use permit that other dwellings of similar density wouldn’t face.
What Michigan buyers should know
Michigan gives zoning power to four types of local government at once, which is why a township ordinance can look nothing like the city’s a mile away. The Michigan Zoning Enabling Act, 2006 PA 110, took effect July 1, 2006, consolidating three older statutes that had governed counties, townships, and cities and villages separately. Four practical consequences follow.
- Four separate zoning authorities: MCL 125.3102(o) defines a local unit of government as a county, township, city or village. Each may adopt its own ordinance, so confirm which body actually zones your parcel before you call anyone.
- Dimensional variances are available everywhere: Under MCL 125.3604(8), the zoning board of appeals in every Michigan local unit may grant nonuse variances for setbacks, height and similar standards. The test is “practical difficulties,” and MCL 125.3603(2) requires a concurring majority.
- Use variances are not: MCL 125.3604(9) limits use-variance authority to cities and villages, plus townships and counties whose ordinance expressly authorized them as of February 15, 2006 or that granted one before that date. Where allowed, the test is “unnecessary hardship” and approval takes a 2/3 vote under MCL 125.3604(10). Read Section 604 of the Michigan Zoning Enabling Act at the Michigan Legislature.
- What that means for buyers: If you’re buying in a Michigan township and your plan needs a use the district bans (a second dwelling, a converted duplex) a variance may not be legally available. Rezoning, or a different property, may be the only route.
Because Align Lending is a Michigan broker, we see how these differences land in real files: a legal non-conforming duplex in one township and a clean R-1 parcel in the next underwrite very differently.
How Align keeps up with the rules
Program rules, loan limits and disclosure requirements change every year. Samantha tracks them so your file is built on the rules in force when you apply, not last year's.
One rule worth knowing: Align is paid by the lender, not by a fee you pay us, and federal rules bar a broker's pay from changing with your rate or fees. A broker earns the same on your loan whether your rate is higher or lower.
Sources: Regulation Z, 12 CFR 1026.36(d).
FAQ: Zoning regulations
Here are answers to common questions about zoning regulations.
How do I find out what a property is zoned?
Start with the local planning department, which publishes a zoning map and the full ordinance online for most municipalities. Search by parcel number or address for the district label, then read that district’s section of the code for permitted uses, setbacks and height limits. For a purchase, ask the zoning administrator for written confirmation; many issue a verification letter for a modest fee. Confirm the same details before any project, as our guide to home renovation permits covers.
What is the difference between a variance and a rezoning?
A variance is permission to break one rule on one parcel, such as building six feet from a line where the setback requires ten. A rezoning changes the district classification itself. A legislative decision that affects everything the land may be used for. Variances turn on difficulty or hardship unique to the lot; rezonings turn on planning merit. Both move what a property is worth, as our guide to the impact of zoning laws on home value explains.
Can zoning stop me from renting out my house?
Yes. Many communities restrict short-term rentals, cap unrelated occupants, or require a rental license and inspection in residential districts, and some prohibit accessory dwelling units outright. Zoning can control whether and how you rent, but in Michigan it cannot control what you charge: MCL 123.411 prohibits local rent control on private residential property. If your math depends on rental income, verify the current ordinance and any pending amendments first, and see our explainer on rent control.
Does zoning affect my mortgage approval?
It can. The appraiser must report the zoning class and state whether the property is a legal conforming use, a legal non-conforming use, an illegal use, or has no local zoning. Legal non-conforming properties stay financeable when the appraisal accounts for any effect on value and marketability, while an illegal use such as a zoning-prohibited accessory dwelling unit carries added comparable-sales requirements. Because conventional guidelines drive those calls, read our explainer on Fannie Mae and Freddie Mac before offering on an unusual property.
The bottom line on zoning regulations
Zoning regulations are local laws that decide how a parcel may be used and what may be built on it, and they touch your loan through the appraisal: every property is classified as legal conforming, legal non-conforming, an illegal use, or no local zoning. In Michigan, four kinds of government (county, township, city and village) write those rules under the Michigan Zoning Enabling Act, and dimensional variances are available everywhere while use variances are limited to cities, villages and grandfathered townships and counties. Verify the district in writing before you close, not after.
If you’re ready to buy a property with a zoning wrinkle (a non-conforming use, an extra unit or mixed-use square footage) talk to Align Lending. We’ll shop your scenario across our lender network and show you the numbers side by side. Call 248-506-5727 or start online today.
Footnotes:
1. This article is for informational purposes only and is not intended to provide legal, financial, or tax advice. Zoning ordinances are adopted and amended locally and change frequently; consult the municipality’s zoning administrator and a qualified land use attorney about your specific parcel and plans. Return to text.
2. The 60-foot lot and 10-foot setback figures are a simplified illustration of how dimensional standards compound, not a description of any specific district. Actual setbacks, measurement methods, permitted encroachments and lot coverage limits are defined by the local ordinance and can differ substantially. Return to text.
Sources: requirement that the appraisal report the zoning class and indicate legal conforming, legal non-conforming (grandfathered), illegal, or no local zoning, and the treatment of legal non-conforming use and of land-use regulations preventing reconstruction, Fannie Mae Single Family Selling Guide, B4-1.3-04, Site Section of the Appraisal Report, version dated June 4, 2025. Conditions for an accessory dwelling unit not allowed under zoning, including a minimum of three settled sales with at least two sharing the same non-compliant zoning use, Fannie Mae Single Family Selling Guide, B4-1.3-05, Improvements Section of the Appraisal Report. Statement that the City of Houston does not have zoning and regulates development through subdivision and platting codes, City of Houston Planning and Development Department, Development Regulations page, accessed August 2026. Definition of local unit of government (MCL 125.3102(o)), scope of land development regulation (MCL 125.3201(4)), continuation of nonconforming uses and ordinance-provided reconstruction terms (MCL 125.3208), residential treatment of state licensed residential facilities and family child care homes (MCL 125.3206), majority vote to grant a variance (MCL 125.3603(2)), and the practical-difficulties, unnecessary-hardship, February 15, 2006 and 2/3-vote provisions (MCL 125.3604), Michigan Zoning Enabling Act, 2006 PA 110, effective July 1, 2006, as amended, Michigan Compiled Laws. Prohibition on local rent control, MCL 123.411, 1988 PA 226 as amended by 2018 PA 585, effective March 28, 2019.
This article summarizes general zoning concepts and cited legal provisions as of August 2026 and is not legal advice. Local zoning ordinances vary by municipality and change over time; verify current requirements with the local zoning administrator. Align Lending is an independent Michigan mortgage broker, NMLS #2041154.
Related resources
12-minute read
Guide to mortgage rate buydowns: How they lower your payment
Learn how temporary 2-1 buydowns and permanent discount points cut your mortgage payment, what each costs, and how to calculate your break-even point.
12-minute read
Benefits of mortgage rate locks, and when to lock
See how a mortgage rate lock protects your rate for 30 to 60 days, what extensions cost, and when locking beats floating in a shifting rate market.
12-minute read
Urban vs. suburban housing markets: how to choose the right fit
Compare urban vs. suburban housing markets on price per square foot, commute and transportation costs, space and schools so you can choose where to buy with.
