
Manufactured Homes: Pros and Cons for Budget-Conscious Buyers
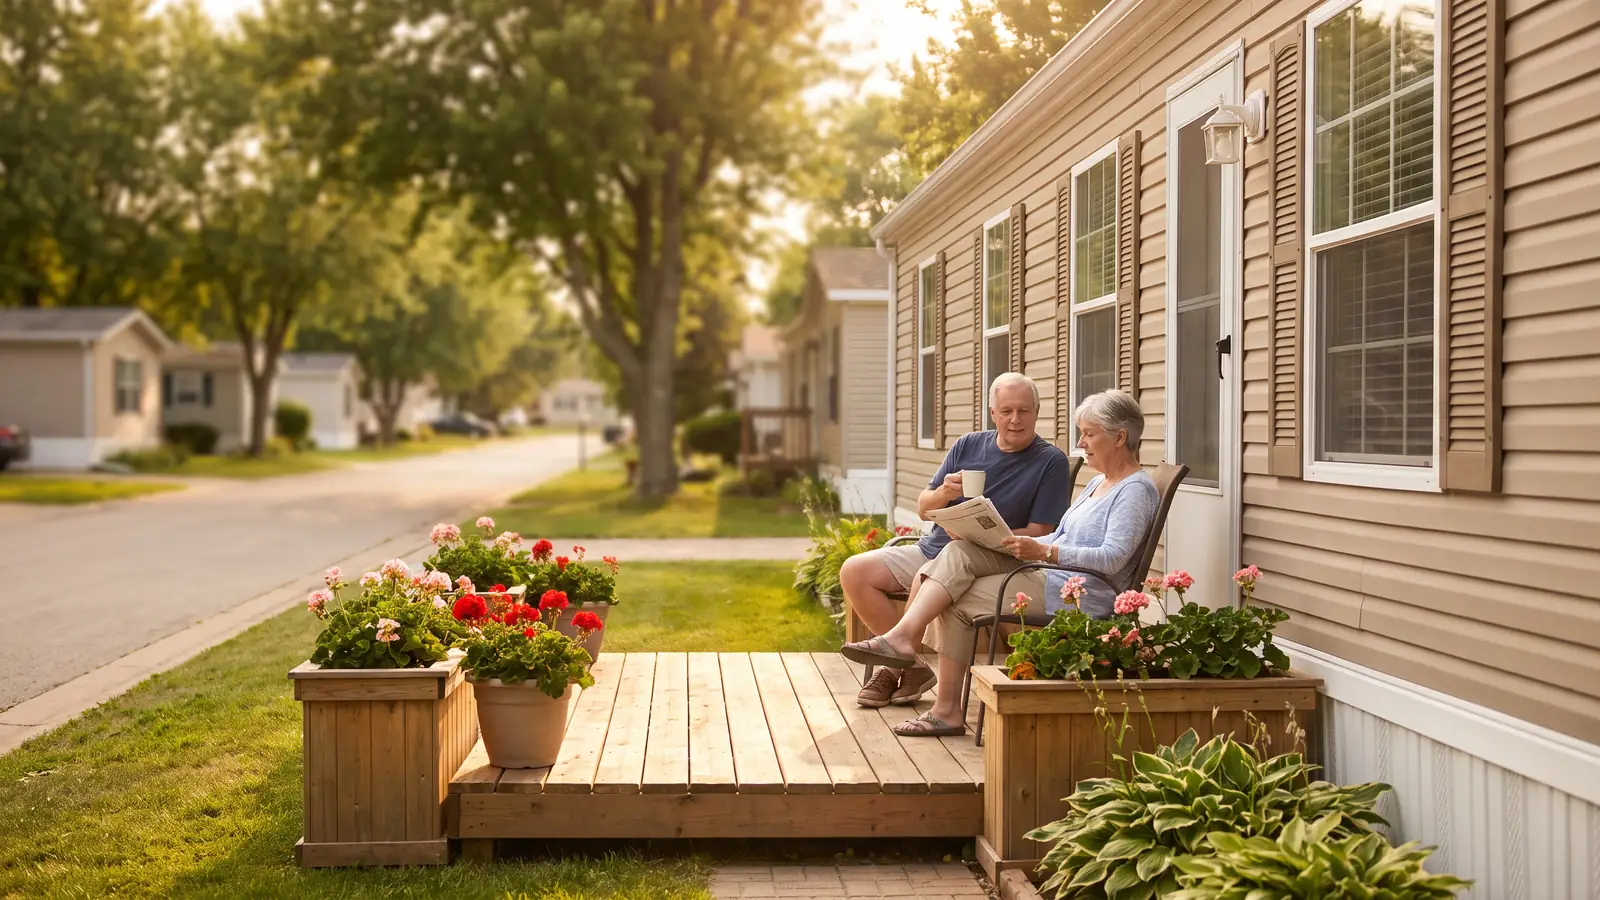
A new manufactured home sold for an average of $123,300 in 2024, against $514,500 for the average new site-built house sold the same year. Strip the land out of the site-built figure the way the Census Bureau does and the comparison gets cleaner: $84.45 per square foot for a new manufactured home versus $168.86 per square foot for the structure of a new site-built home. Roughly half the cost per foot, for a house built to a federal safety code that is enforced inside the factory.
The main trade-off isn’t construction quality. It’s ownership structure. In 2024, 78% of new manufactured homes placed for residential use were titled as personal property rather than real estate, and that single fact drives most of the drawbacks people associate with these homes: higher-rate chattel loans instead of mortgages, thinner consumer protections, and appreciation that hinges on whether you own the ground underneath.
Learn the real pros and cons of manufactured homes, including how they differ from mobile and modular homes, what one actually costs once land and setup are added, and which loan programs you can qualify for. If you’re still comparing formats, our guide to home types and living lays the alternatives out side by side.
Key takeaways:
- The price gap is real and measurable: New manufactured homes averaged $84.45 per square foot in 2024 versus $168.86 per square foot for the structure of a new site-built home about half, before you add land.
- Titling drives almost everything else: 78% of new manufactured homes placed in 2024 were titled as personal property, which routes buyers to chattel loans; the CFPB found roughly 42% of manufactured home purchase loans are chattel loans, and only 27% of manufactured home loan applications end in a loan being financed, against 74% for site-built homes.
- Owned land changes the math: On land you own, permanently affixed and titled as real estate, a manufactured home can qualify for conventional, FHA, VA, and USDA financing, Freddie Mac’s CHOICEHome reaches 97% LTV with Home Possible or HomeOne, meaning as little as 3% down.
What is a manufactured home?
A manufactured home is a house built entirely in a factory on a permanent chassis to the federal Manufactured Home Construction and Safety Standards, the HUD Code, then transported to its site in one or more sections. HUD’s definition sets the size floor: at least 8 body feet wide or 40 body feet long in the traveling mode, or 320 or more square feet once erected on site.
The date that matters is June 15, 1976. Every manufactured home built since then must be certified by its manufacturer as compliant with the HUD Code, and each transportable section carries a red certification label on the back proving it. The standards, codified at 24 CFR Part 3280, cover body and frame strength, thermal protection, plumbing, electrical, and fire safety. Unlike local building codes, which are enforced by inspectors at the jobsite, the HUD Code is enforced at the plant. Which is why factory-built quality control is a genuine selling point rather than a marketing line.
The code isn’t frozen, either. In September 2024 HUD finalized 90 new or updated standards, the most extensive HUD Code revision in more than three decades, adding provisions for open floor plans, attics, and accessibility, and permitting manufactured homes with up to four dwelling units for the first time. The rule was published September 16, 2024 and took effect March 17, 2025.
Manufactured vs. mobile vs. modular: what’s the difference?
These three words get used interchangeably, and they should not be. They describe different building codes, which means different titling and different loan eligibility.
| Feature | Mobile home | Manufactured home | Modular home |
|---|---|---|---|
| Built to | No federal standard, built before June 15, 1976 | Federal HUD Code (24 CFR Part 3280), enforced in the factory | State and local building codes, the same ones site-built homes follow |
| Permanent chassis | Yes | Yes, part of the federal definition | No. Sections are set on a conventional foundation |
| Usual titling | Personal property | Personal property unless permanently affixed and converted to real estate | Real property, like any site-built house |
| Financing | Very limited; often chattel only | Chattel loan, or a mortgage if titled as real estate on an approved foundation | Financed as a standard single-family home, Fannie Mae treats modular, prefabricated, panelized, and sectional housing the same as site-built |
| Appraisal form | Rarely appraised for lending | Manufactured-home-specific requirements apply | Standard single-family appraisal, standard comparables |
That last column is the one that changes your loan options. Because a modular home is built to local code and set on a conventional foundation, lenders underwrite it like any other house, our breakdown of the benefits of modular homes covers where that advantage is worth the higher price. If you’re weighing the two categories against each other, the direction of the modular housing market is worth reading before you commit to a format.
How much does a manufactured home actually cost?
Sticker price first: in 2024, the average new manufactured home sold for $123,300 and measured 1,460 square feet. Single-section homes averaged $85,200 and double-section homes averaged $152,000. Prices have kept climbing since, the Census Bureau’s Manufactured Housing Survey put the March 2026 national average at $137,500, with single-section homes at $90,700 and double-section homes at $164,200.
Compare that to the site-built market. The average new single-family house sold in 2024 went for $514,500, and the Census Bureau derived an average land value of $108,561 inside that number. By June 2026, the median new house sold for $398,300 and the average for $475,400, according to Census Bureau new residential sales data.
Here’s the honest version of the comparison. Manufactured home prices cover the home only. Site-built sales prices are the home and the land sold as a package. On a per-square-foot structure basis, the closest thing to apples to apples, a new manufactured home ran $84.45 per square foot in 2024 against $168.86 for a site-built structure. A 1,753-square-foot double-section home at the 2024 average cost $152,000; the same square footage at site-built structure rates would run roughly $296,000 before you bought a lot to put it on.1
What the sticker price leaves out
Budget for these before you decide the home is affordable.
- Land: Either a lot purchase or ongoing lot rent in a community. This is usually the largest number that isn’t on the price tag.
- Site prep and foundation: Grading, a footing or slab, piers, and anchoring. If you want mortgage financing, the foundation has to meet the lender’s permanent-foundation standard, not just the manufacturer’s minimum.
- Transportation and setup: Hauling the sections and joining them on site. USDA’s guaranteed loan program will let you finance the unit, transportation, and set-up costs together, which tells you how significant that line is.
- Utility connections and skirting: Water, sewer or septic, electric, and gas hookups, plus perimeter skirting.
- Insurance: Coverage for a manufactured home is priced differently than a site-built policy, and a home titled as personal property may need a specialty policy rather than a standard homeowners form. Get a quote before you sign anything.
One pro that does show up in the monthly budget: newer HUD Code homes are built to defined thermal standards, and manufacturers offer efficiency upgrade packages. If low operating cost is part of why you’re looking at this category, read up on green building certifications for homes and check what ENERGY STAR efficiency standards for homes actually require before you pay for an upgrade package. Our guide to creating a sustainable home covers which improvements pay back fastest.
Pros and cons of manufactured homes at a glance
Most of the advantages are front-loaded into the purchase, and most of the disadvantages show up later, in financing and resale. That asymmetry is the whole decision.
| Pros | Cons |
|---|---|
| Cost per square foot is about half. $84.45 versus $168.86 for a site-built structure in 2024. | Titling usually isn’t real estate. 78% of new placements in 2024 were personal property, which limits your loan options. |
| Federal code, factory-enforced. Every home since June 15, 1976 carries a HUD certification label. | Financing is harder to get. Only 27% of manufactured home loan applications end in a financed loan, versus 74% for site-built. |
| Faster to build. Factory production runs on schedule regardless of weather, with no jobsite delays. | Chattel loans cost more. Roughly 42% of purchase loans in this category are chattel, with higher rates, shorter terms, and fewer consumer protections. |
| Customizable at order time. Floor plans, finishes, and efficiency packages are chosen before the build starts. | Lot rent can rise. In a land-lease community you own the home but not the ground, and the rent is not fixed. |
| Appreciation is possible on owned land. FHFA now publishes a Manufactured House Price Index built from real-property mortgages the GSEs bought. | Placement is restricted. Local zoning, community rules, and foundation requirements narrow where a home can legally go. |
Two of those cons deserve more than a table row, because they’re the ones that decide whether this purchase works financially.
The titling problem: personal property vs. real property
A manufactured home is titled as personal property by default, legally closer to a vehicle than a house. In 2024 only 18% of new manufactured homes placed for residential use were titled as real estate. Converting to real property generally requires that you own the land, that the home is permanently affixed to a foundation meeting the lender’s standard, and that you record the conversion under your state’s process.
Why it matters: personal property means a chattel loan, and the CFPB has documented that chattel borrowers pay higher interest rates than manufactured-home mortgage borrowers and site-built borrowers, face higher denial rates, and get fewer of the protections that attach to mortgages. It also shapes value. FHFA’s Manufactured House Price Index, which tracks only real-property manufactured homes financed with conventional mortgages bought by Fannie Mae and Freddie Mac, rose 7.9% between the second quarters of 2023 and 2024, with a median price of $231,000. Homes on leased land aren’t in that index at all, and they behave differently.
If you already own a manufactured home financed as personal property, converting to real property is sometimes the single highest-value move available to you. Our guide to refinancing a manufactured home walks through what has to be true before a lender will treat it as real estate.
Lot rent: the housing cost that isn’t fixed
In 2024, 23% of new manufactured homes were placed in land-leased manufactured home communities. In that arrangement you own the structure and rent the ground, and the ground rent is a landlord’s decision, not a locked-in mortgage payment.
No federal agency publishes an official national average for manufactured home lot rent. Industry sources commonly quote a range running from around $100 to $800 a month, but the spread across markets and communities is wide enough that no single number should drive your decision.2 Price the specific community you’re considering, ask for its rent history over the last five years, and read the community rules and lease before you make an offer. A home you can afford at today’s lot rent is not automatically a home you can afford at the lot rent three renewals from now, and unlike a mortgage payment, this one can move.
How do you finance a manufactured home?
There are two financing worlds here, and which one you land in depends on the land, not the home. Own the lot and permanently affix the home as real estate, and you can access the same mortgage programs a site-built buyer uses. Keep the home on leased land as personal property, and you’re in chattel territory.
Chattel loans (personal property)
A chattel loan is secured by the home itself, not by real estate. It closes faster and involves less paperwork, and for a home in a land-lease community it may be the only option. The costs are real: the CFPB found chattel borrowers pay higher rates than manufactured-home mortgage borrowers, face higher denial rates, and receive fewer of the protections that come with a mortgage. Roughly 42% of manufactured home purchase loans are chattel loans.
Conventional mortgages on owned land
Fannie Mae requires that the manufactured home and the land it sits on be legally classified as real property, and that the home carry a HUD Data Plate or Certification Label. Fannie Mae and Freddie Mac both run enhanced programs for homes with site-built features: Fannie Mae’s MH Advantage offers financing flexibilities including higher LTV limits, standard mortgage insurance coverage, and reduced loan-level price adjustments, and Freddie Mac’s CHOICEHome reaches 95% LTV standard, or 97% LTV with Home Possible or HomeOne, as little as 3% down. Both require a factory-applied label, so the home has to be ordered that way; you can’t retrofit into the program.
FHA, VA, and USDA options
Government-backed programs all reach manufactured homes, with conditions.
- FHA Title II: The home must have at least 400 square feet of floor area, be built after June 15, 1976 to the HUD Code, sit on a permanent foundation built to FHA criteria, be classified as real estate, and never have been installed or occupied at another site. See HUD’s overview of FHA loan programs for the program family.3
- FHA Title I: This is the personal-property path. Title I can finance a manufactured home classified as personal property or as real estate. The term is the catch: the maximum is 20 years and 32 days for a single-unit manufactured housing loan, well short of a 30-year mortgage. Title I loan limits are indexed and updated annually, so confirm the current figures rather than working from a number you read somewhere.
- VA: A manufactured home must be permanently affixed and classified as real property to be eligible for VA financing.4
- USDA Section 502 guaranteed: New units must never have been installed or occupied elsewhere, must have at least 400 square feet, and must sit on a permanent foundation built to FHA guidelines. The loan can cover the unit, transportation, and set-up costs together.
Worth saying plainly, because it argues against our own convenience: if you can buy the land and put the home on a permanent foundation, do it. Nearly every disadvantage in the cons column above shrinks when the home becomes real estate. Where that isn’t possible, a chattel loan is a legitimate tool, just price it knowing what it costs relative to a mortgage. The rest of the ownership picture, from insurance to maintenance to eventual resale, is covered in our homeownership guide.
What Michigan buyers should know
Michigan’s manufactured housing rules affect both your tax bill and your loan eligibility, and they pull in opposite directions.
- The $3 specific tax: Under Michigan’s Trailer Coach Parks Act, the licensee of a trailer coach park collects and remits a specific tax of $3.00 per month per occupied trailer coach, and that specific tax is in lieu of property tax on the coach itself. It sounds like a bargain, and on the tax line it is, but it also reflects that the home is not real property, which is exactly what limits your financing. A manufactured home on land you own and permanently affixed is generally assessed as real property instead. Ask a tax professional how your specific situation is treated before you assume either outcome.
- MSHDA works with manufactured homes, with a condition: The MI 10K DPA Loan provides up to $10,000 toward down payment, closing costs, and prepaids, and its eligible property list includes a multiple-section manufactured home on its own property, alongside single-family homes and condos. It must be paired with a MSHDA MI Home Loan first mortgage, and every borrower has to finish a homebuyer education class and produce the certificate. Note the wording: multiple-section, on its own property. A single-wide on a rented lot doesn’t fit. Income, sales price, credit, and asset limits apply and change, so confirm the current terms with a MSHDA-approved lender.
- Midwest pricing runs below the national average: In March 2026, the Census Bureau put the Midwest average sales price for a new manufactured home at $115,300, versus $137,500 nationally, $82,500 for single-section homes and $160,400 for double-section homes.
Because Align Lending is a broker rather than a direct lender, we can place manufactured-home files with the wholesale lenders that actually want them, including MSHDA loans, instead of steering you into the one product a single bank happens to offer.
How Align matches the loan to the property
Lenders do not treat every property the same. Condos, including non-warrantable ones, and homes with two to four units each come with rules that vary from one lender to the next.
Because Align is a broker, Samantha can take your file to the wholesale lender whose guidelines fit the property, instead of forcing it into one bank's box. One application, multiple lenders, and one person on your file from start to finish.
FAQ: Manufactured homes
Here are answers to common questions about manufactured homes.
What is the difference between a manufactured home, a mobile home, and a modular home?
A mobile home is a factory-built home constructed before June 15, 1976, when the federal HUD Code took effect; homes built after that date to the HUD Code are manufactured homes. A modular home is different again: it’s built in factory sections but assembled on site to the same state and local codes as site-built houses, so it’s financed and appraised like a traditional home. That distinction changes your loan options more than anything else about the house, see our guide to the benefits of modular homes for the comparison.
Do manufactured homes go up in value?
Sometimes. Homes titled as personal property on leased land tend to behave more like vehicles than real estate. Homes on owned land with permanent foundations can appreciate: FHFA publishes a Manufactured House Price Index built from real-property manufactured homes financed with conventional mortgages, and that index rose 7.9% between the second quarters of 2023 and 2024. Land ownership, foundation type, location, and upkeep are the biggest drivers of which way your home moves, and broader factory-built housing market trends shape the resale pool you’ll eventually sell into.
Is it hard to get a mortgage on a manufactured home?
Harder than for a site-built home, but very doable. The CFPB found that only 27% of manufactured home loan applications end with the loan actually being financed, against 74% for site-built homes, and that 42% of manufactured home purchase applications were denied outright versus 7% of site-built applications. If the home sits on land you own and is permanently affixed to an approved foundation, conventional, FHA, VA, and USDA financing are all on the table. If it’s on leased land or titled as personal property, you’ll generally need a chattel loan with a higher rate and a shorter term. A broker can shop both paths at once, and our guide to refinancing a manufactured home covers converting from one to the other later.
What are the biggest hidden costs of buying a manufactured home?
Budget beyond the sticker price for land or lot rent, site prep and foundation work, transportation and setup, utility connections, and skirting, the Census figures cover the home only, not the ground it sits on. Insurance is priced differently than a standard homeowners policy, and a home titled as personal property may need a specialty policy. In a land-lease community, lot rent can rise over time, so review the community’s rent history and rules before you commit. Our home types and living guide compares these ongoing costs across housing formats.
The bottom line on manufactured homes
Manufactured homes are the most affordable new housing built in America, and the gap isn’t small: $84.45 per square foot in 2024 against $168.86 for a new site-built structure, or $123,300 for the average new manufactured home against $514,500 for the average new site-built house sold with its land. Every one built since June 15, 1976 meets the federal HUD Code. The catch is titling. 78% of new placements in 2024 were personal property, which means chattel financing, weaker protections, and value that tracks the home rather than the market. Put the same home on land you own with a permanent foundation and it qualifies for conventional, FHA, VA, and USDA mortgages, and starts behaving like real estate.
If you’re ready to find out which path your scenario actually qualifies for, talk to Align Lending, we’ll shop it across our lender network, including lenders that specialize in manufactured housing, and show you the numbers side by side. Call 248-506-5727 or start online today.
Footnotes:
1. The $296,000 figure is an illustrative calculation, not a quote or an estimate for any specific home: 1,753 square feet multiplied by the Census Bureau’s 2024 average price per square foot for a new site-built structure excluding land ($168.86). Example figures are hypothetical and for educational purposes only; they do not constitute an advertisement of credit terms or a rate quote under federal or state lending laws. Actual construction costs, home prices, and your rate and terms will depend on your market, your property, your application, and market conditions. Return to text.
2. The $100 to $800 per month lot rent range is a commonly cited industry range, not a federal statistic. No U.S. government agency publishes an official national average for manufactured home community lot rent, and actual rents vary substantially by state, metro area, community, and lease terms. Treat the range as a rough orientation only and verify the current rent, the rent history, and the escalation terms for any specific community in writing. Return to text.
3. Align Lending is not acting on behalf of or at the direction of FHA or HUD. FHA program requirements, loan limits, and eligibility criteria are set by HUD and are subject to change; individual wholesale lenders in Align’s network may apply additional overlays. Return to text.
4. Align Lending works with VA-approved lenders and is not endorsed or sponsored by the Dept. of Veterans Affairs or any government agency. VA eligibility, entitlement, and property requirements are determined by the VA. Return to text.
Sources: average sales price, average square feet, average cost per square foot, placement, and titling data for new manufactured homes and new single-family site-built homes, U.S. Census Bureau and U.S. Department of Housing and Urban Development, Manufactured Housing Survey and Survey of Construction, “Cost & Size Comparisons: New Manufactured Homes and New Single-Family Site-Built Homes, 2014–2024,” and MHS “Average Sales Price by Region and by Size of Home, 2014–2026.” Median and average new house sales prices for June 2026, U.S. Census Bureau and HUD, “Monthly New Residential Sales, June 2026” (release CB26-121, July 24, 2026). HUD Code effective date, certification label, definition of a manufactured home, and 24 CFR Part 3280, U.S. Department of Housing and Urban Development. The 90 new or updated standards (74 updated plus 16 new), the four-dwelling-unit provision, and the March 17, 2025 effective date, HUD Manufactured Home Construction and Safety Standards final rule (announced September 11, 2024; published in the Federal Register September 16, 2024). Chattel loan share (42%), the 27%-versus-74% share of applications that end in an originated loan, the 42%-versus-7% denial comparison, interest rate comparisons, and consumer protection findings, Consumer Financial Protection Bureau, “Manufactured Housing Finance: New Insights from the Home Mortgage Disclosure Act” (May 2021), using 2019 HMDA data. Manufactured House Price Index figures, Federal Housing Finance Agency. Real property, Data Plate, and MH Advantage requirements, Fannie Mae Selling Guide (B5-2-01, B2-3-02) and Manufactured Housing Product Matrix; modular housing treatment, Fannie Mae Selling Guide B4-1.4-02. CHOICEHome LTV and feature requirements, Freddie Mac Single-Family. FHA Title I maximum term and Title II eligibility criteria, HUD. USDA Section 502 guaranteed manufactured housing requirements, USDA Rural Development. Michigan specific tax of $3.00 per month per occupied trailer coach, MCL 125.1041 (Trailer Coach Parks, 1959 PA 243). MI 10K DPA Loan amount, eligible property types, and borrower requirements, Michigan State Housing Development Authority.
This article is for informational purposes only and is not intended to provide legal, financial, tax, or engineering advice. Consult a qualified professional about your situation. Loan program requirements, loan limits, tax treatment, zoning rules, and community lease terms change and vary by lender, locality, and property, verify current details before you buy. Align Lending is an independent mortgage broker and does not set loan terms; program eligibility and pricing are determined by the individual wholesale lenders in Align’s network and are subject to credit approval and property eligibility. Nothing here is an offer of credit or a commitment to lend. Align Lending is an independent Michigan mortgage broker, NMLS #2041154.
Related resources
12-minute read
Condo vs. Co-op: Similarities and Differences Every Urban Buyer Should Know
Compare condo vs. co-op ownership, monthly fees and board approval rules so you can choose the urban home type that fits your budget and lifestyle.
11-minute read
Guide to the Different Types of Houses by Structure and Style
Discover the different types of houses by structure and style, from ranch and colonial to craftsman and Victorian, and find which home type fits your life.
17-minute read
The 12 safest cities in the US for buying a home
See the 12 safest US cities for home buyers, ranked on violent and property crime, traffic safety, and livability, plus how each balances safety with cost.
