
How to read a home inspection report and prioritize what matters
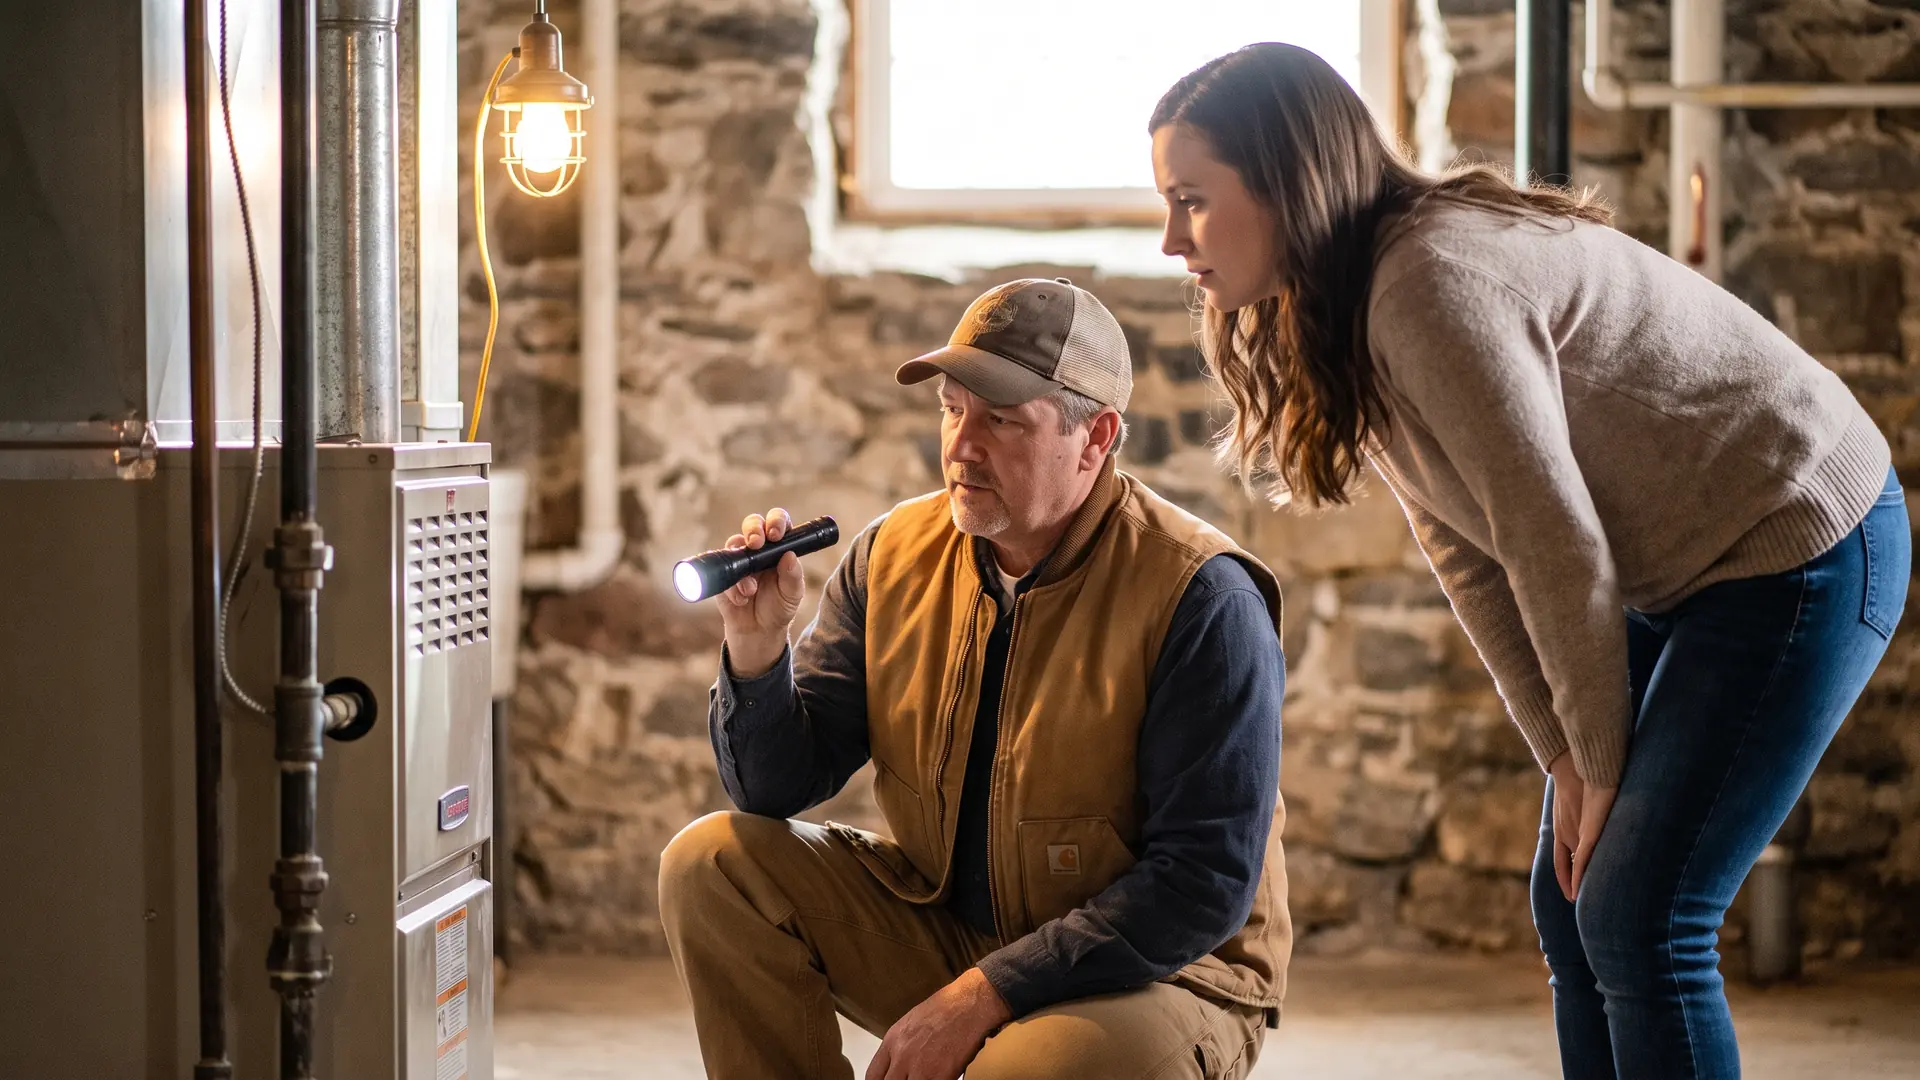
To read a home inspection report, start with the summary section, then work through the system-by-system findings using the inspector’s severity codes, most reports sort every observation into 4 tiers, commonly labeled satisfactory, minor, moderate, and major, and color-coded from green to red. Focus first on the 5 systems that drive repair costs: structure, roof, electrical, plumbing, and HVAC.
A full report commonly runs 30 to 50 pages with photographs, and that length is what makes buyers panic. Usually only a handful of findings matter enough to drive a repair negotiation, and the report tells you which ones, if you read the rating key first.
Learn how to read a home inspection report, including what the severity ratings mean, which sections deserve attention first, and how to turn findings into a repair request. Earlier in the process? Start with our Home Buying guide.
Key takeaways:
- Read the legend before the findings: Most reports sort every observation into 4 severity tiers, and the key defining them sits in the opening pages, not the summary where buyers start.
- 5 systems carry the real money: Structure, roof, electrical, plumbing, and HVAC drive the largest repair costs, so read those 5 sections first.
- “Monitor” is not “repair”: A system at the end of its useful life is not by itself a defect, but deficiencies affecting safety, soundness, or structural integrity can make a property ineligible for a conventional loan until it’s repaired to at least a C5 condition rating.
What is in a home inspection report?
Every report has three layers: an opening section defining the scope and rating key, a system-by-system body documenting what the inspector observed, and a summary pulling the most significant findings together. Start at the summary, but don’t stop there, summaries are selective.
The opening section is the part buyers skip and the part that tells you how to read everything else. It names the standard the inspector followed, lists conditions on the day (weather, whether utilities were on, attic access), and defines every severity label. InterNACHI’s guide to reading a home inspection report describes the narrative format most inspectors use: identify the condition, explain why it matters, recommend an action.
What an inspection does not cover
A home inspection is a non-invasive, visual examination of the accessible areas of a residential property. One sentence that explains most of your report’s disclaimers. The inspector doesn’t open walls or dismantle the furnace, and anything blocked, buried, or shut off gets flagged as not inspected rather than satisfactory. Those two notations mean different things.
Inspection standards define a material defect as an issue that may significantly and adversely affect the property’s value, or that poses an unreasonable risk to people. Cosmetic wear doesn’t qualify; neither does age alone. HUD’s buyer guidance tells you to request an inspector’s Standards of Practice or a sample report, the screening in our guide to how to choose a home inspector, alongside ASHI resources for finding a certified home inspector.
An appraisal is not an inspection
HUD states it plainly on the disclosure FHA buyers sign: appraisals are not home inspections. An appraisal estimates the home’s value for your lender and does not replace an inspection, and FHA does not perform home inspections. One happens only if you arrange and pay for it.1
The appraiser works for the lender and answers “what is this worth?” The inspector works for you and answers “what is wrong with it?” Our guide to the home appraisal process covers the lender’s side, and the home buying process shows where each falls.
What do the ratings in a home inspection report mean?
Most reports use a four-tier severity scale, usually color-coded, that tells you what each finding demands of you. Labels vary, “marginal,” “moderate,” “recommend repair”, but the tiers carry the same four instructions.
| Tier | Typical labels and color | What the inspector saw | What you do about it |
|---|---|---|---|
| 1 | Satisfactory / Serviceable, green | Functioning as intended, with normal wear | Nothing. Don’t spend negotiating capital here. |
| 2 | Minor / Maintenance, blue | Small homeowner items: caulking, a loose railing, a missing filter | First-year maintenance list. Rarely worth a repair request. |
| 3 | Moderate / Marginal / Monitor, yellow | Working now but aging, undersized, or showing early failure | Budget for it and re-check it. Specialist opinion on expensive systems. |
| 4 | Major / Defective / Safety hazard, red | Failed, unsafe, or actively causing damage | Get a contractor’s written estimate. These are your negotiation items. |
The legend in your report governs. And count the tier-4 items before reacting to page count: a 45-page report with three red findings describes a healthier house than an 18-page report with nine.
“Monitor” versus “repair”: what the notation is telling you
“Monitor” means the inspector saw something not failing yet and wants you watching it; “repair” means budget for action now. The difference isn’t how alarming it looks. It’s whether the condition is stable.
Age is the most misread signal in the report. Inspection standards are explicit that a system near, at, or beyond the end of its normal useful life is not, in itself, a material defect. A 22-year-old furnace that heats correctly is a budgeting fact. What you’re owed is the inspector’s estimate of remaining useful life on major systems, equipment, structure, and finishes, HUD’s buyer disclosure lists that among what a qualified inspector delivers. Use those numbers to build a replacement calendar, not a repair demand.
Which report sections matter most?
Read five sections first: structure and foundation, roof, electrical, plumbing, and HVAC. They carry the largest repair bills and the only findings likely to touch your financing.
Structure and foundation
Look for language about movement, not cracks. Hairline cracks in a poured wall are common; horizontal cracking, bowing, stair-step cracking in block, doors out of square, and sloping floors describe a wall that is moving, findings that justify a structural engineer before your contingency expires.
Roof
Read three things: estimated remaining life of the covering, evidence of active leaking, and whether the inspector could walk it. “Inspected from ground level with binoculars” is a scope limitation, not a clean bill of health.
Electrical
Safety hazards concentrate here: double-tapped breakers, ungrounded three-prong outlets, missing GFCI protection near water, aluminum branch wiring, knob-and-tube, and any panel the inspector names as a known hazard. These are cheaper to fix than buyers fear, but they’re the findings most often written up as unsafe.
Plumbing
Note supply piping material, drain material, water pressure, and active leaking under sinks or at the water heater. Galvanized supply lines and polybutylene get called out because insurers care about them. A dripping trap is a $15 fix; a whole-house repipe is not.
HVAC and water heater
You want age, condition, and remaining life for each unit. Inspectors won’t run a heat exchanger diagnostic or condemn a furnace, so when they recommend an HVAC contractor, follow it. A water heater past its expected life that still works is a tier-3 budgeting item; one leaking at the tank is a tier-4 replacement.
Give the remaining sections one focused pass:
- Grading and drainage: Read this alongside the foundation section. Negative grading and downspouts discharging at the wall cause most basement moisture findings.
- Exterior and attic: Rot at trim, siding, and sills shows where water has been entering for years, and poor attic ventilation resurfaces later as sheathing damage.
- Interior: Mostly cosmetic, with two exceptions: stains corroborating a roof or plumbing finding, and missing smoke or carbon monoxide alarms.
Our home inspection checklist for buyers lists what a standard inspection covers in each area, useful when your report seems to skip something.
Red flags and how to verify them
Six categories justify slowing down: structural movement, active water intrusion, hazardous electrical, a failing roof, mold or persistent moisture, and major systems at end of life. Each warrants a written contractor estimate first, because the gap between “recommend evaluation” and a real bill is where deals go wrong.
The photographs are your verification tool, and buyers underuse them. Work backward: pick your tier-4 items, find their photos, and note the location captions. That pairing lets a contractor quote without a second site visit, and it’s what your agent attaches to a repair request so the seller sees evidence.
Environmental findings sit outside the standard visual inspection and are ordered separately. Three are worth knowing by the numbers:
- Radon: The EPA recommends fixing a home at 4 pCi/L or higher and says to consider fixing between 2 and 4 pCi/L. Its position is that all homes should be tested, because radon is the second leading cause of lung cancer and can’t be seen or smelled. Read EPA guidance on radon testing during home purchases before skipping the test.
- Mold: No EPA or other federal limits have been set for mold or mold spores, so no lab result can tell you a house “passes.” The EPA’s guidance is that the key to mold control is moisture control, and that a moldy area under about 10 square feet, roughly a 3-foot by 3-foot patch, can usually be handled without a professional.
- Lead-based paint: The federal disclosure rule covers most housing built before 1978, and sellers of those homes must give buyers a 10-day period to conduct a paint inspection or risk assessment. That window runs on its own clock, so calendar it the day you go under contract.
Wood-destroying insects, sewer scope, well and septic, and oil tank testing follow the same pattern: separate specialist, separate timeline. Line them up against your inspection contingency deadline, see contingencies in home offers.
How to turn the report into a repair request
Ask for a short list of expensive, documented, tier-4 items, not the report. Handing a seller 45 highlighted pages invites a blanket refusal; three or four findings with estimates invite a counteroffer.
You have four instruments, and they aren’t equally good for you:
- Seller completes the repairs: Best for safety items you want fixed before you own them. Worst for control, the seller picks the contractor.
- Closing cost credit: Usually cleanest. You control the contractor and timing, and the credit cuts cash due at closing. Credits are capped by loan program and by your closing costs, so confirm the ceiling first.
- Price reduction: Lowers your loan amount and payment rather than your cash to close. Best when the repair is one you’d do later anyway, though it resets the value your appraisal must support.
- Walk away: Available while your inspection contingency is live. Read the contract’s notice and deadline language closely.
Here’s the math. On a $310,000 purchase with a failing furnace and an aging roof, estimates of $6,500 and $9,000 support asking for a $15,500 credit. If the seller counters at $8,000, your exposure is $7,500. A number you can weigh against walking away.2 Our guides to negotiating repairs after a home inspection and negotiating house prices cover the sequencing, and choosing a real estate agent who knows the submarket matters more here than anywhere else.
One caution: your earnest money deposit is protected only while a contingency is live and only if you give notice the way your contract requires. Requests after the window closes are requests, not rights.
How inspection findings can affect your loan
Your inspection report doesn’t go to your lender, but the appraiser’s independent observations do, and that’s where condition problems stall financing.
On conventional financing, Fannie Mae has appraisers assign a condition rating from C1 to C6. A C6 property has substantial damage or deferred maintenance with deficiencies severe enough to affect safety, soundness, or structural integrity, and loans on C6 properties aren’t eligible for sale to Fannie Mae. The deficiencies must be repaired and the property must reach at least a C5 rating before delivery. A leaking roof or an unsafe panel can become a condition of your loan closing whether or not you asked the seller to fix it.
FHA works the same way under a different name. HUD’s Minimum Property Requirements state that all FHA-insured homes must be safe, sound, and secure, and the appraiser must note every instance where a property fails that standard, with the repairs needed and their estimated cost.3 Because Align is a broker rather than a single lender, we can compare how different wholesale lenders treat a flagged condition instead of declining the file.
Do two things the day your report lands: send your loan officer a heads-up on any finding involving roof, structure, electrical, plumbing, or heat, and confirm your program’s maximum seller credit before naming a number. Our guides to budgeting for closing costs and preparing for a home closing show where a credit lands, and preparing to buy covers the reserves that make a post-closing repair survivable.
How Align moves your purchase to the closing table
Over the last 12 months, Samantha's loans averaged under 14 days from application to clear to close, across more than 100 loans. Your closing date is set by your purchase agreement. Her job is to have your loan ready well before it.
She handles your file herself, with a processor supporting her behind the scenes. You always know who to call, and the person who answers knows your goals.
Build your homebuyer game plan
Sources: Align Lending loan records, 12 months to October 2026.
FAQ: Reading a home inspection report
Here are answers to common questions about reading a home inspection report.
What should I look for first in a home inspection report?
Go straight to the summary page, then read every item flagged as a safety hazard or major defect. Prioritize structure and foundation, roof, electrical, plumbing, and HVAC, since these carry the biggest repair costs. On a first purchase, our first-time home buyers guide shows where the inspection sits in the timeline.
What do the colors and codes in an inspection report mean?
Most inspectors use a tiered system: green or “satisfactory” means no action needed, blue or “minor” notes small maintenance items, yellow or “moderate” flags issues to address soon, and red or “major/defective” marks problems needing prompt repair or specialist evaluation. Every report includes a legend, read it first. The same legend appears on newly built homes, which our guide to home inspections for new construction covers.
What are red flags in a home inspection report?
The serious ones are foundation movement or structural cracks, active water intrusion, hazardous electrical such as knob-and-tube or double-tapped breakers, failing roofs, mold or moisture in attics and basements, and HVAC or water heaters at end of life. Any of these warrants repair estimates before you proceed. They’re also the reason to think hard about home inspection waivers, since waiving means you never learn about them.
Can I negotiate with the seller based on the inspection report?
Yes, that’s one of the report’s main purposes. With an inspection contingency, you can request the seller complete repairs, provide a credit at closing, or reduce the price to reflect documented defects. Focus on major items backed by contractor estimates, since sellers rarely respond well to long lists of cosmetic nitpicks, a mistake covered in our guide to avoiding common home inspection pitfalls.
The bottom line on reading your inspection report
Reading a home inspection report is triage, not a reading assignment. Start with the legend defining the report’s 4 severity tiers, then the summary, then the 5 sections carrying real money: structure, roof, electrical, plumbing, and HVAC. Sort “monitor” items into a maintenance calendar and “repair” items into a short negotiation list backed by contractor estimates. A system at the end of its useful life isn’t by itself a defect. The findings that affect your financing are the ones touching safety, soundness, or structural integrity.
If you’re ready to work through inspection findings without losing your closing date, talk to Align Lending, we’ll shop your scenario across our lender network and price the repair-credit and price-reduction versions side by side. Call 248-506-5727 or start online today.
Footnotes:
1. Align Lending is not acting on behalf of or at the direction of FHA or HUD. Statements about FHA home inspection policy reflect HUD form HUD-92564-CN, “For Your Protection: Get a Home Inspection,” and are subject to change. Return to text.
2. Example figures are hypothetical and for educational purposes only; they do not constitute an advertisement of credit terms or a rate quote under federal or state lending laws. Repair costs, allowable seller credits, and your cash to close depend on your application, the property, your loan program, and market conditions. Return to text.
3. Align Lending is not acting on behalf of or at the direction of FHA or HUD. FHA Minimum Property Requirements are set by HUD in Handbook 4000.1 and are subject to change. Return to text.
Sources: home inspection defined as a non-invasive, visual examination of the accessible areas of a residential property, the definition of a material defect, and the rule that a system near, at, or beyond the end of its normal useful life is not in itself a material defect, InterNACHI Standards of Practice. Appraisals are not home inspections, FHA does not perform home inspections, and the inspector’s estimate of remaining useful life of major systems, equipment, structure, and finishes, U.S. Department of Housing and Urban Development form HUD-92564-CN, “For Your Protection: Get a Home Inspection.” FHA Minimum Property Requirements that all insured homes be safe, sound, and secure, and the appraiser’s duty to note every instance of noncompliance together with repairs and estimated cost, HUD Handbook 4000.1. Condition ratings C1 – C6, the C6 definition, ineligibility of C6 properties for sale, and the requirement to repair to at least C5, Fannie Mae Selling Guide B4-1.3-06. Radon action level of 4 pCi/L, the 2 – 4 pCi/L consider-fixing range, and the recommendation that all homes be tested, U.S. Environmental Protection Agency. Absence of federal limits for mold or mold spores, moisture control as the key to mold control, and the roughly 10-square-foot threshold for do-it-yourself cleanup, EPA, “A Brief Guide to Mold, Moisture and Your Home.” Pre-1978 housing coverage and the 10-day period for a buyer’s lead-based paint inspection or risk assessment, EPA lead-based paint disclosure rule.
This article is for informational purposes only and is not intended to provide legal, financial, or tax advice. Home inspection reports, repair requests, contingency notices, and purchase agreement language should be reviewed by a licensed real estate professional, home inspector, or attorney in your state. Consult a qualified professional about your situation. Program terms and figures shown are illustrative, are not a rate quote or an offer of credit, and are subject to change. Align Lending is an independent Michigan mortgage broker, NMLS #2041154.
Related resources
12-minute read
The Home Appraisal Process: What to Expect
Learn how the home appraisal process works, from the lender’s order to the final report, including typical costs of $300-$1,500 and what appraisers check.
12-minute read
Home inspection checklist for buyers: What to look for room by room
See the complete home inspection checklist for buyers, from foundation to attic, so you can spot costly problems before you close on your next home.
12-minute read
How to prepare for a home closing: your step-by-step checklist
Learn how to prepare for a home closing with a step-by-step timeline, documents to bring, and final walk-through tips for a smooth closing day.
4-minute read
Love & Property: The Savvy Guide to Buying a Home with Your Partner (No Ring Required)
Explore legal considerations for buying a home with a partner, including mortgage agreements. Protect your investment now!
