
How to appeal a low appraisal and keep your purchase on track
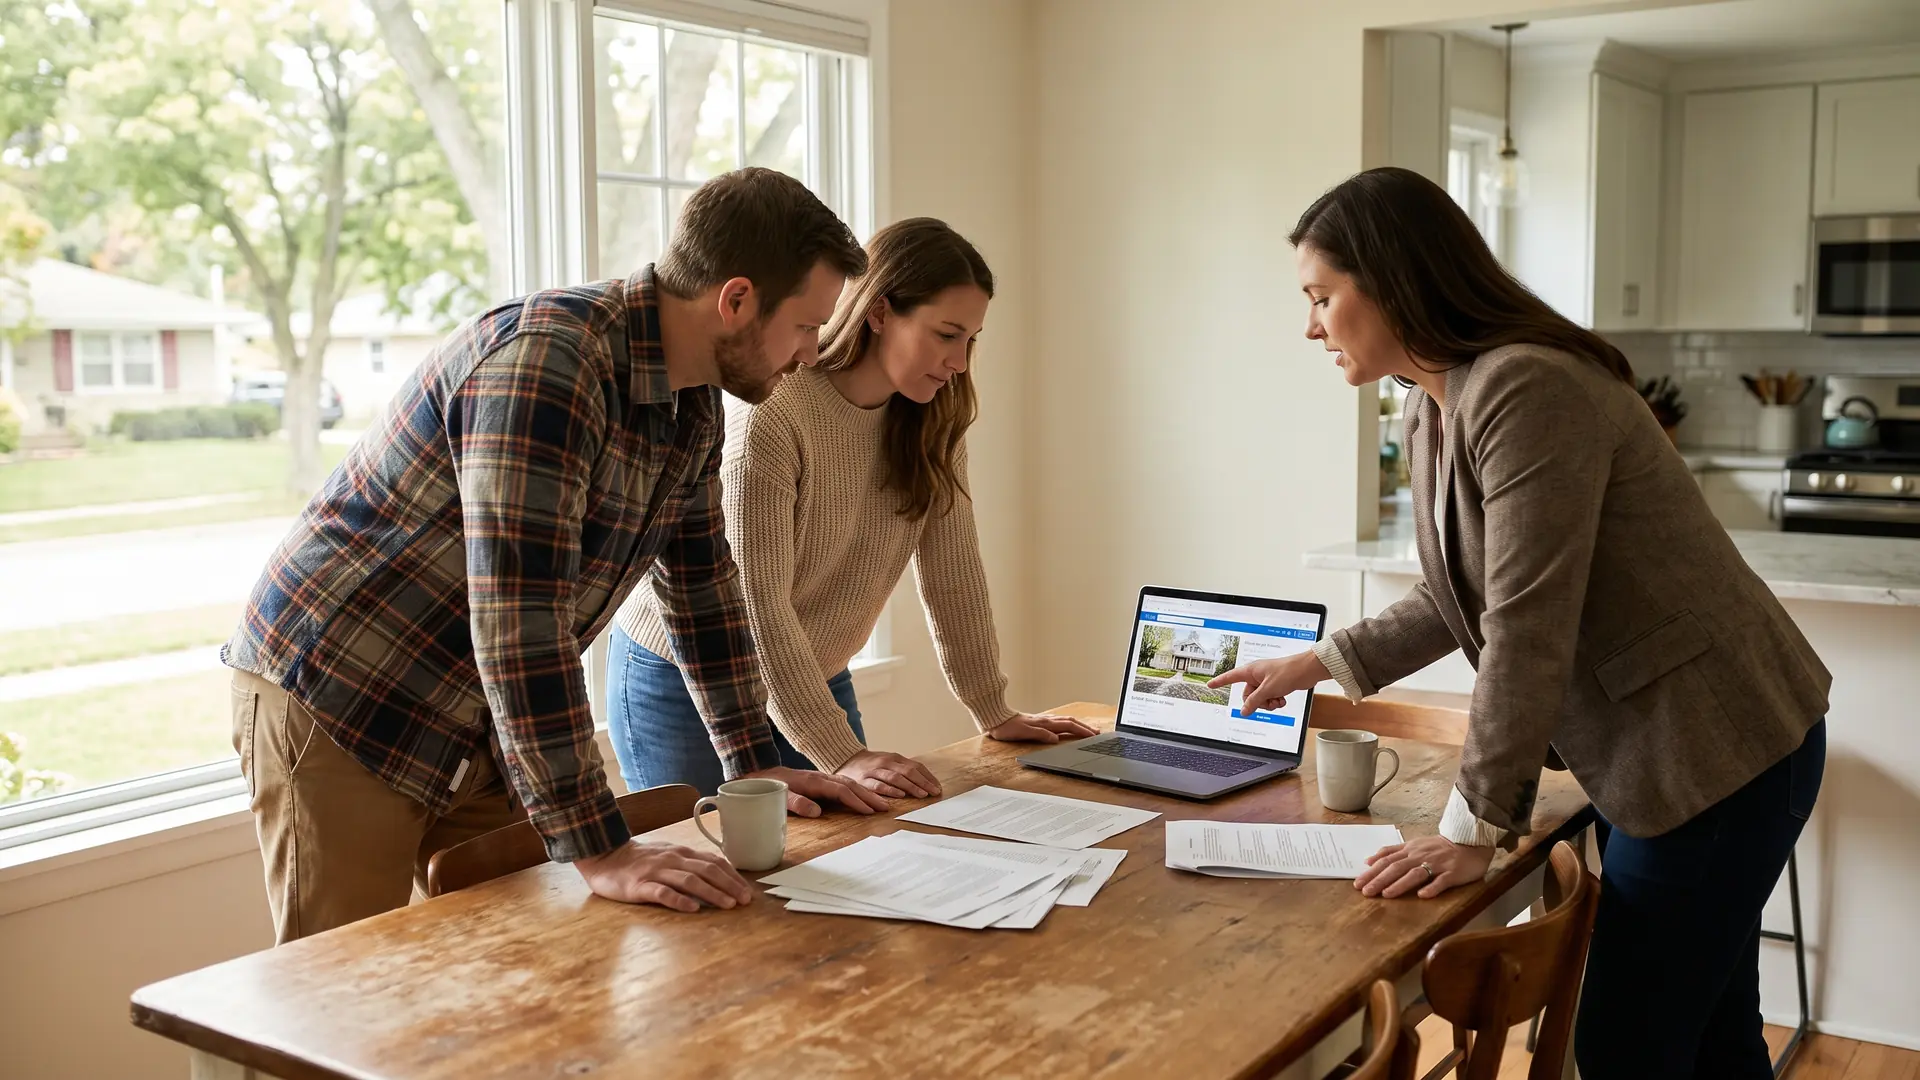
To appeal a low appraisal, you file a reconsideration of value (ROV) through your lender. A formal request that lets you submit up to 5 additional comparable sales or data points the appraiser didn’t have. Lenders must allow 1 borrower-initiated ROV per appraisal, so your evidence has to be right the first time.
What wins an appeal is a documented error, not a disagreement. Wrong square footage, a missed bathroom, a finished basement counted as unfinished, or stale comps when better sales closed nearby, those move a number. “It should be worth more” does not.
Learn how to appeal a low appraisal: how to read the report for errors, how to build a comp case an appraiser will act on, and what to do if the ROV fails. If you’re earlier in the process, start with our Home Buying guide.
Key takeaways:
- 1 appeal, 5 comps: A borrower-initiated reconsideration of value is the formal appeal. Lenders permit only 1 per appraisal, and your request may include up to 5 additional comparable properties or data points.
- Documented errors move the value, opinions don’t: Appraisers revise when shown facts they didn’t have, a wrong bed or bath count, an unreported upgrade, or comps outside the 12-month window when closer, more recent sales existed.
- 3 fallbacks if the appeal fails: Renegotiate the price, cover the gap in cash, or ask for a second appraisal, and on an FHA file where the underwriter finds the first appraisal materially deficient, the lender pays for the second one.
Why did the appraisal come in low?
A low appraisal traces to one of 4 causes, and only the first two are worth appealing. Knowing which you have saves a week of evidence-gathering for a value that will never move.
- Factual errors in the report: Square footage, bed and bath count, lot size, and basement finish are recorded by hand, and all of them get recorded wrong. One miscounted bathroom can swing thousands of dollars in adjustments.
- Weak or stale comparable sales: Fannie Mae expects comps that closed within the last 12 months and requires a minimum of 3 closed comparables. An appraiser who reached back 14 months, or across a school district line, when better sales closed nearby has handed you an argument.
- A market moving faster than closed sales: Appraisals look backward; your price reflects what buyers bid today. In a fast seller’s market the two diverge, and the fix is a market-conditions adjustment, not different comps.
- A price the neighborhood doesn’t support: Sometimes the appraisal is right. If you won a bidding war at a number no sale comes near, renegotiation is your move.
The stakes are mechanical: your lender calculates loan-to-value from the lower of the sales price or the appraised value, so every dollar below your contract price is cash you bring. Our home appraisal process guide covers how the number gets built, why home appraisals matter explains what the lender protects, and loan-to-value ratio covers the math.
Step 1: Review the appraisal report for errors
Start with the facts, not the value: your lender must give you a copy of every appraisal and written valuation developed for your application promptly upon completion, or at least 3 business days before closing, whichever comes first, and you don’t have to ask. Read it the day it lands, because an ROV must be resolved before your loan closes.
Work it against a fixed checklist, hunting for statements that are provably false.
- Gross living area: Compare the report’s square footage against your purchase agreement, the listing, and the county assessor’s record. Finished basement space is measured separately from above-grade area.
- Bed and bath count: Confirm the full and half baths, and any bedroom the appraiser declined to count. A room without a closet or egress window may legitimately not count, but confirm that’s why.
- Lot size and site features: Check acreage, frontage, and whether waterfront, wooded, or corner-lot value was recognized.
- Missed upgrades: Look for improvements the report never mentions: a new roof, a rebuilt furnace, a remodeled kitchen. If it isn’t in the report, it wasn’t in the value.
- Stale or distant comps: Check each comp’s sale date, distance, and similarity, and confirm the report adjusted for the differences it identified. Appraisers state proximity in miles with a direction. “1.75 miles NW”, so distance is easy to audit.
HUD names the worst version of this: a materially deficient appraisal includes one relying on outdated or dissimilar comparable sales when more recent or more comparable sales were available as of its effective date.
Check which product you got. If your file used a drive-by appraisal or another exterior-only valuation, the appraiser never went inside, so documented interior upgrades carry more weight.
Step 2: Build your evidence for a higher value
You get 5 slots, so choose your comparables rather than dumping them. Three excellent comps beat 5 mediocre ones, every weak comparable invites the appraiser to dismiss the package.
A comp earns its place when it’s recent, close, and genuinely similar: closed within 12 months, in the same subdivision, matching on style, age, above-grade square footage, and bed and bath count. A sale from 6 weeks ago two streets over beats one from 11 months ago across town.
- Proof of the corrections: The assessor’s record, a survey, or a floor plan showing the true square footage or lot size.
- Proof of the upgrades: Dated invoices, permits, and before-and-after photos for work the report ignored. Permits carry the most weight because they’re third-party and dated.
- Proof of market movement: Pending sales, active listings, and days-on-market data for your price band, which support a market-conditions adjustment no closed sale can.
This is where your agent earns the commission. Agents have MLS access, know which sales were arm’s-length, and can pull the remarks showing why a comp doesn’t fit. Our guide to working with a real estate agent covers what to ask for, and the Appraisal Institute maintains a directory of designated appraisers.
Step 3: File a reconsideration of value
A reconsideration of value is a formal request, routed through your lender, asking the original appraiser to re-examine the value using information they didn’t consider. You don’t contact the appraiser yourself. Your lender must keep written ROV policies and disclose the process when the appraisal is delivered, including that you get 1 per appraisal.
Fannie Mae expects a request to identify a specific set of items, so build around them:
- Identifying information: Your name, the property address, the appraisal’s effective date, the appraiser’s name, and the date.
- The areas you believe are deficient: Named findings, not a general objection.
- Your supporting data: Up to 5 comparable properties or data points, with documentation behind each.
- Your explanation: Why the new data supports a different conclusion.
From there the file moves without you. Your lender confirms the request is complete, forwards a standardized communication to the appraiser, and sets a turn-time expectation. The appraiser responds with a revised report carrying written commentary either way, read it even when you lose, because it names the comps that failed.
Government loans add a layer. For FHA case numbers assigned on or after September 2, 2024, HUD requires a plain-language ROV disclosure at application and again when the appraisal is delivered, plus written communication at 4 points: acknowledging the request, explaining how to fix an incomplete one, reporting status, and delivering the result.1 VA and USDA files follow their own agency procedures, so ask your loan officer which governs yours.2 Our home buying process guide maps where the appeal lands, and the CFPB’s home buying resources cover what your lender owes you.
If you believe the value reflects discrimination rather than bad data, that’s a separate process, not a stronger ROV. FHA requires potential fair housing violations to be reported to HUD’s Office of Fair Housing and Equal Opportunity immediately, on form HUD-903.1 or at 1-800-669-9777.
What if the appeal doesn’t work?
You have 5 moves left, and 4 of them still close the deal. Run the numbers first. The gap is rarely the figure people assume.
Say you’re under contract at $320,000 in Waterford and the appraisal lands at $305,000. Your lender lends against $305,000, so your 5% down payment drops to $15,250, but you owe the $15,000 gap in cash on top. Cash for the down payment plus gap goes from $16,000 to $30,250.3 That $14,250 swing, not the headline value, is the decision in front of you.
| Option | What it costs you | The risk |
|---|---|---|
| Renegotiate to the appraised value | Nothing out of pocket | The seller can refuse and relist, though the next buyer’s lender likely sees the same value. |
| Split the difference with the seller | Half the gap in cash, plus a slightly larger loan | Needs a seller with room in their numbers; unavailable on a thin-equity sale. |
| Cover the full gap in cash | The entire difference on top of your down payment | Drains reserves, and the extra cash buys no equity. |
| Ask the lender to order a second appraisal | A second appraisal fee on a conventional file; on FHA, where the underwriter finds the first materially deficient, the lender pays | No guarantee of a different number, and it adds time your contract may not have. |
| Walk away | Your appraisal and inspection fees, already spent | Without an appraisal contingency, your earnest money may be at risk. |
Renegotiation is the first call, and it’s stronger than buyers think: the appraisal is a third-party opinion the seller must confront with the next buyer too. See negotiating house prices, and how to sell a home with a low appraisal for what their agent is saying.
Before you walk, read your contract. Your deposit’s protection depends on your home purchase contingencies, and earnest money deposits covers when it’s at risk. For the full menu, see what to do if your home doesn’t appraise; a refinance has no seller to negotiate with, so how to refinance with a low appraisal covers it.
How to prevent a low appraisal next time
Most prevention happens in the 2 weeks before the appraiser arrives, and it costs nothing. Nobody may influence an appraiser’s opinion of value, but you can make sure they have the facts.
- Document the improvements: Ask the seller’s agent for permits, dated invoices, and a list of updates with years completed, then route that packet through your lender.
- Reconcile the details up front: Square footage and bath discrepancies among the listing, the assessor’s record, and reality should be fixed before the appraisal, not appealed after.
- Price the offer from closed comps: An offer built on the same sales the appraiser will use rarely produces a gap, see creating a competitive offer.
- Cap your gap coverage: If you waive appraisal protection to win a bidding war, decide the figure you’ll cover in advance and put that cap in writing.
Sellers have their own version, see how to prepare for a home appraisal.
How Align moves your purchase to the closing table
Over the last 12 months, Samantha's loans averaged under 14 days from application to clear to close, across more than 100 loans. Your closing date is set by your purchase agreement. Her job is to have your loan ready well before it.
She handles your file herself, with a processor supporting her behind the scenes. You always know who to call, and the person who answers knows your goals.
Build your homebuyer game plan
Sources: Align Lending loan records, 12 months to October 2026.
FAQ: Appealing a low appraisal
Here are answers to common questions about appealing a low appraisal.
Can you dispute a low home appraisal?
Yes. The formal route is a reconsideration of value, submitted through your lender rather than to the appraiser. Your dispute must document specific problems: incorrect square footage or bedroom count, missed upgrades, or stronger comps the appraiser overlooked. Vague disagreement won’t succeed, and the appeal must be resolved before your loan closes, our home closing process guide shows where the appraisal sits.
How often are appraisal appeals successful?
No agency publishes a success rate, but the rules tell you what works. Appraisers revise when shown objective information they didn’t have. Documented factual errors, or superior comps that are recent, nearby, and truly similar. Appeals built on opinion rarely change anything. Hiring a buyer’s agent who knows the submarket matters most right here.
What happens if the appraisal comes in low and the seller won’t budge?
You have 3 options: pay the difference between appraised value and purchase price in cash, negotiate a compromise where you split the gap, or walk away if your contract includes an appraisal contingency. Without that contingency, walking away can put your earnest money at risk, so read your contingencies in home offers first.
Who pays for a second appraisal?
It depends on the loan type. On an FHA file, when the underwriter finds the first appraisal materially deficient and the appraiser can’t or won’t resolve it, HUD requires the lender to pay for the second one. On a conventional file you generally pay a fee comparable to the first appraisal on your Loan Estimate, and generally only the lender can order it, budget for it using how to budget for closing costs.
The bottom line on appealing a low appraisal
Appealing a low appraisal means filing a reconsideration of value through your lender, and you get 1 per appraisal with up to 5 additional comparable properties attached. Win it with facts: wrong square footage, a miscounted bathroom, an unreported remodel, or comps outside the 12-month window when closer sales existed. If the value holds, you still have room, renegotiate, split the gap, cover it in cash, or walk away if your contract protects you. Your lender lends against the lower of sales price or appraised value, so a gap is always cash, never financing.
If you’re ready to work through a low appraisal without losing the house, talk to Align Lending, we’ll shop your scenario across our lender network and show you what the gap costs under each option, side by side. Call 248-506-5727 or start online today.
Footnotes:
1. Align Lending is not acting on behalf of or at the direction of FHA or HUD. FHA reconsideration-of-value and second-appraisal requirements are set by HUD. Return to text.
2. Align Lending works with VA-approved lenders and is not endorsed or sponsored by the Dept. of Veterans Affairs or any government agency. VA and USDA appraisal review procedures are set by those agencies. Return to text.
3. Example figures are hypothetical and for educational purposes only; they are not an advertisement of credit terms or a rate quote under federal or state lending laws. Your loan amount, cash to close, and any appraisal gap depend on your application, the property, and the appraisal. Return to text.
Sources: borrower-initiated ROV requirements, lender policies, the disclosure delivered with the appraisal, one ROV per appraisal, the five-comparable limit, request contents, and the appraiser’s revised report with commentary, Fannie Mae Selling Guide B4-1.3-12. Twelve-month comparable window and three-comparable minimum, Fannie Mae Selling Guide B4-1.3-08. Loan-to-value from the lower of sales price or appraised value, Fannie Mae Selling Guide B2-1.2-01. Appraisal copies delivered promptly upon completion or at least three business days before consummation, whichever is earlier, ECOA Valuations Rule, 12 CFR § 1002.14(a)(1). FHA ROV disclosure timing, the four required written borrower communications, material appraisal deficiencies, the mortgagee’s obligation to pay for a second appraisal ordered after one, fair housing reporting on form HUD-903.1 or at 1-800-669-9777, and the September 2, 2024 implementation date, HUD Mortgagee Letter 2024-07.
This article is for informational purposes only and is not legal, financial, or tax advice. Purchase agreements, appraisal contingencies, and earnest money terms should be reviewed by a licensed real estate professional or attorney in your state. Figures shown are illustrative, not a rate quote. Align Lending is an independent Michigan mortgage broker, NMLS #2041154.
Related resources
12-minute read
The Home Appraisal Process: What to Expect
Learn how the home appraisal process works, from the lender’s order to the final report, including typical costs of $300-$1,500 and what appraisers check.
12-minute read
Home inspection checklist for buyers: What to look for room by room
See the complete home inspection checklist for buyers, from foundation to attic, so you can spot costly problems before you close on your next home.
12-minute read
How to prepare for a home closing: your step-by-step checklist
Learn how to prepare for a home closing with a step-by-step timeline, documents to bring, and final walk-through tips for a smooth closing day.
3-minute read
The Art of Finding Home: A Modern Hunter’s Guide to Securing Your Perfect Space in 2025
Discover tips for finding your dream home and securing the right mortgage. Start your home search today!
