
How to research a city before you move
Start with the exact address, then go to the official source for each question: the police agency and the state police for crime, FEMA’s flood maps for flood risk, the Census Bureau for commute times and housing costs, and the local assessor and treasurer for property taxes. Then turn what you find into numbers, because taxes, insurance and association dues become part of your monthly payment.
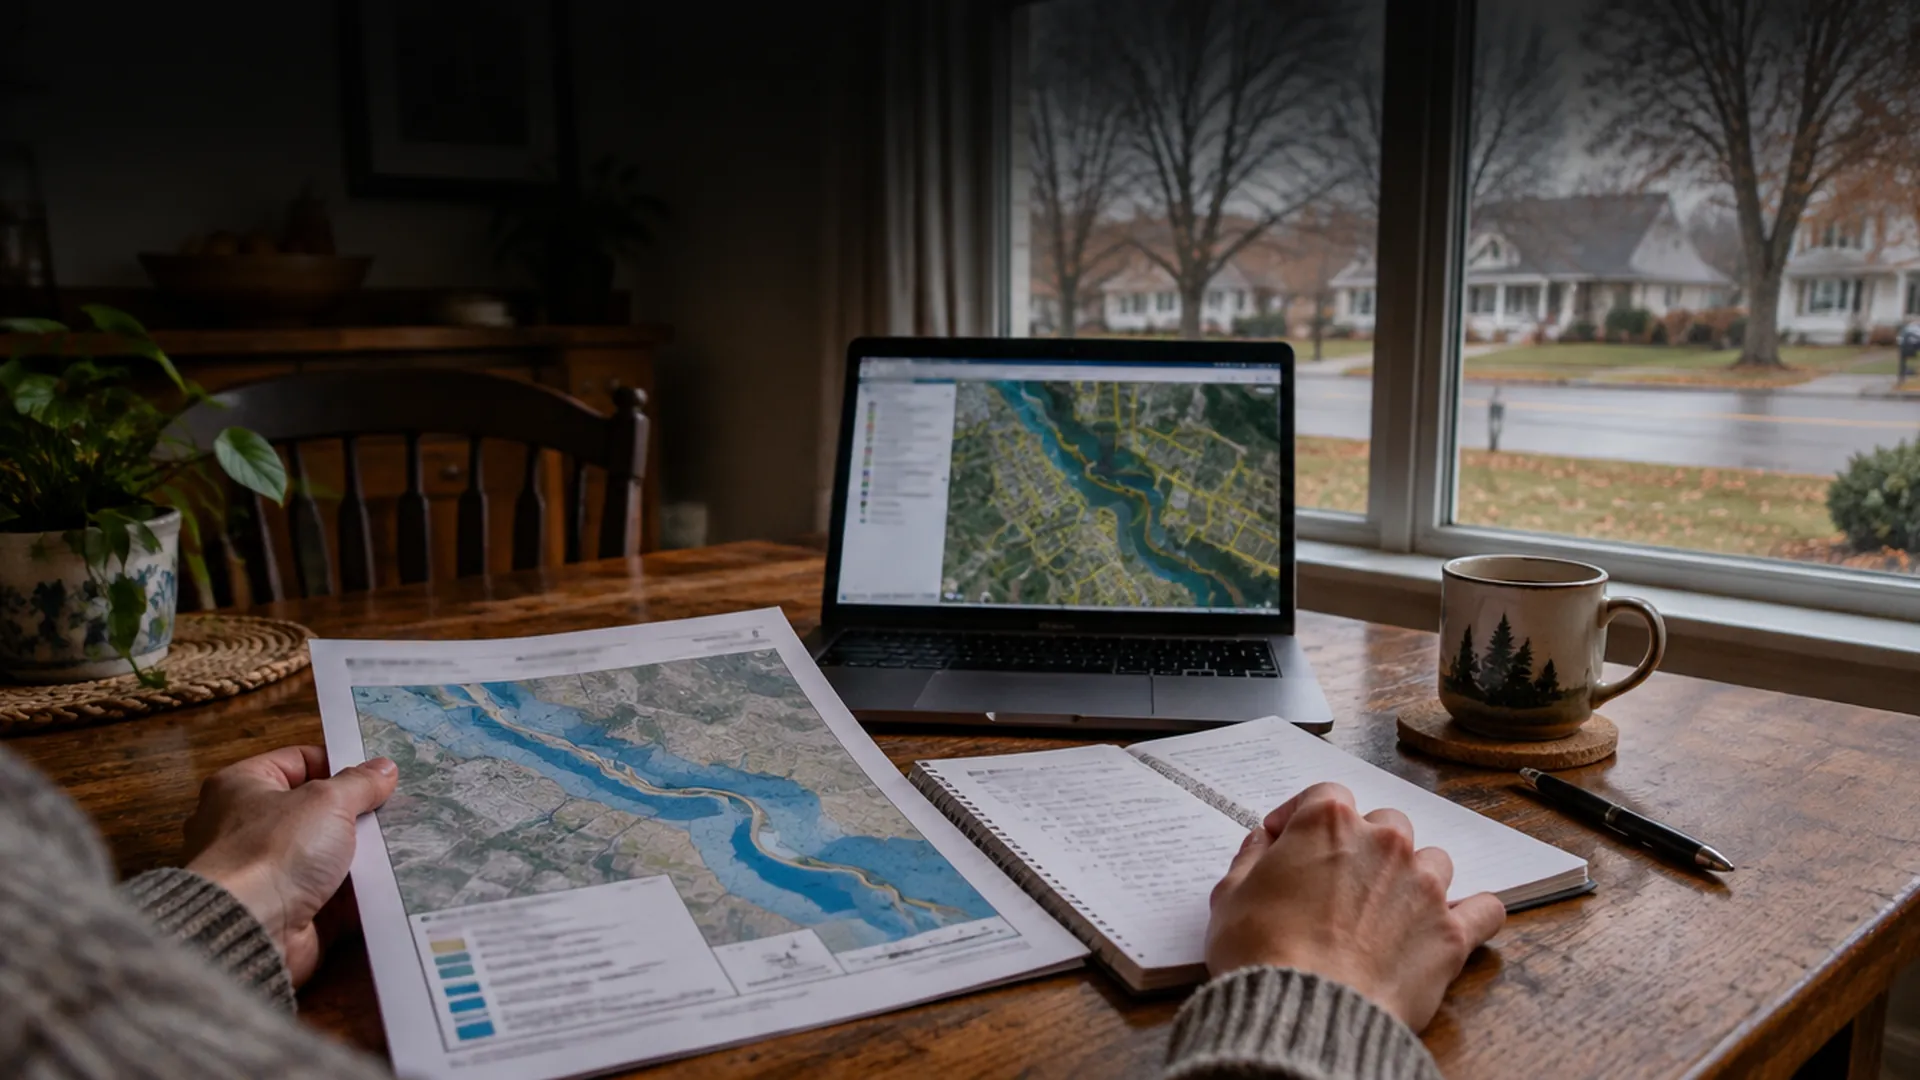
This guide does not rank places or tell anyone where to live. It shows where the public records are, so you can decide what matters to you.
Why start with the address instead of the city name?
In Michigan, a home can carry one city’s name in its mailing address and sit in a neighboring township. The property taxes, the police agency, the school district and sometimes the utility follow the boundary the home sits inside, not the name on the envelope.
The Census Bureau’s free Census Geocoder returns the county and the city or township for an address. Align’s Michigan property tax calculator uses the same Census lookup and also names the school district. Write those names down; every step below uses them.
Earlier in your search? See Align’s guide to finding a home, and the mortgage glossary for terms like millage and escrow.
Where can I find official crime data for an area?
Go to the agencies that collect the reports, not to a website that turns them into a score.
- The local police department or county sheriff. Many post a crime map or an annual report. Some Michigan townships are patrolled by the sheriff or the Michigan State Police, so first find out which agency covers the address.
- The Michigan State Police. Its Michigan Incident Crime Reporting program collects reports from agencies statewide. Since 2023 the yearly figures are in the Crime in Michigan dashboard; earlier years are in its annual reports.
- The FBI’s Crime Data Explorer. National data, searchable by state and agency.
Read any of them with care:
- Sources count differently. The FBI credits a crime to the agency that reported it. The Michigan State Police also counts by the city or township where each crime happened, so totals for one place can differ.
- The data lags and changes. Reports close months after the year ends, and corrections arrive later. A year with missing reports can look like a drop.
- Rates mislead in small places. A rate divides incidents by residents, so in a small community a handful of incidents, or a busy shopping center, moves it a lot.
- Look at several years and each type of offense, not one total for one year.
The FBI has long cautioned against ranking places by crime figures alone. That is why this guide quotes no figures and names no places.
How do I check whether a home is in a flood zone?
Search the address on FEMA’s Flood Map Service Center. According to FloodSmart, the National Flood Insurance Program’s site, zones beginning with A or V are high-risk, and zones B, C and X carry moderate or lower risk, though not none.
- A high-risk zone can require flood insurance. FloodSmart says it is a condition of a federally backed mortgage in a high-risk zone. Your lender checks the flood zone, and the premium becomes part of the monthly payment.
- Timing matters. A flood policy normally takes effect 30 days after purchase, with no wait when it is bought while making a mortgage.
- Lower risk is not no risk. FloodSmart notes that most homeowners insurance does not cover flood damage, and almost a third of flood claims come from outside high-risk areas.
For other natural hazards, FEMA’s National Risk Index now sits inside its Resilience Analysis and Planning Tool. In Michigan, the seller disclosure statement required for most sales of one to four unit homes asks about past flooding, drainage problems and flood insurance. Read it with the map in hand.
How do I look up commute times and housing costs?
The Census Bureau’s data.census.gov holds the American Community Survey. Search the city, township or county you wrote down, then open table S0801 (Commuting Characteristics by Sex) for travel time to work, and table DP04 (Selected Housing Characteristics) for home values, owner costs, rents and the age of the housing. For small places, use the five-year estimates and read the margin of error beside each number.
Then drive to work at your real commute hour on a weekday. MDOT’s Mi Drive map shows current and future lane closures on state roads. Moving from another state? The Bureau of Economic Analysis publishes Regional Price Parities, which compare price levels by state and metro area.
How do I find the real property tax on a home?
In Michigan, set the seller’s tax bill aside. The year after a Michigan home sells, its taxable value resets to half of the assessor’s market value, so the seller’s tax bill is not your tax bill. Align’s guide to Michigan taxable value walks through it, and Treasury explains the rule on its transfer of ownership page.
To plan with your own number:
- Find the property record. The city or township assessor and treasurer hold the taxable value, the exemption status and any special assessments.
- Find the millage for that address. A mill is one dollar of tax per $1,000 of taxable value, and rates differ between neighboring communities and school districts. Treasury publishes millage rates and an estimator, and Align’s property tax calculator applies the published rate for the address.
- Plan to file the exemption. For a home you live in as your principal residence, the principal residence exemption removes local school operating millage, up to 18 mills. You file it with the local assessor.
- Ask about assessments. Ask the treasurer whether any special assessments sit on the parcel.
Other states have their own rules. Florida, for example, reassesses a home at just value on January 1 after it changes hands (Florida Department of Revenue).
What should I check about homeowners insurance before I make an offer?
Get a quote on the actual address before you write the offer, or at the latest during your inspection period. Michigan law does not require homeowners insurance, but DIFS notes a lender is likely to require it on a financed home, and can buy a policy and charge your escrow if you do not show proof of coverage.
When you compare quotes, ask about the deductible and whether water or sewer backup is covered. Flood is a separate policy. The Michigan Department of Insurance and Financial Services (DIFS) publishes a homeowners insurance guide with comparison worksheets.
How do I find out what could change nearby?
- Master plan and zoning map. Many Michigan cities and townships post both. The zoning map shows what can be built on the empty lot behind a house; the master plan shows what the community intends.
- Planning commission and board agendas. Proposed developments and rezonings appear there first.
- Road work. MDOT posts its projects and studies; the county road agency or city handles local roads.
- Local news, for millage votes, bond proposals and large projects.
What should I know about utilities, internet and association costs?
- Utilities. The Michigan Public Service Commission’s electric service area map shows which utility serves an address. Ask the seller for a year of bills. For a private well or septic system, ask the county health department about records.
- Internet. The FCC’s National Broadband Map shows which providers report service at an address. Confirm with the provider.
- Association or condo costs. Ask for the master deed, bylaws, budget, reserve study, recent minutes and any special assessments, voted or proposed. Monthly dues count toward the payment a lender qualifies you on. For an FHA loan on a condo, check HUD’s list of FHA-approved condominium projects.
Where do I find information about schools?
First confirm the district, because school district lines do not follow city names. The listing or tax bill names the district that levies the property’s school taxes, and the district’s enrollment office can confirm which school serves the address.
Then read what the district publishes. MI School Data is Michigan’s official education data portal, and every Michigan district and school posts an Annual Education Report each year, including how students are assigned to schools. Align does not rate or rank schools; read the district’s own reports and decide what matters to you.
Where is the same data in Ohio, North Carolina, Florida, Louisiana and Texas?
The federal tools above cover every state. Crime reporting and insurance regulation are state programs:
| State | State crime data | Insurance regulator |
|---|---|---|
| Michigan | Crime in Michigan dashboard | Department of Insurance and Financial Services |
| Ohio | Office of Criminal Justice Services | Ohio Department of Insurance |
| North Carolina | State Bureau of Investigation | North Carolina Department of Insurance |
| Florida | Florida Department of Law Enforcement | Office of Insurance Regulation |
| Louisiana | FBI Crime Data Explorer, by agency | Louisiana Department of Insurance |
| Texas | Crime in Texas report | Texas Department of Insurance |
The National Association of Insurance Commissioners keeps a directory of state insurance departments.
Why does this research matter before you make an offer?
- Taxes and insurance are part of the payment. Many mortgage payments include property taxes and homeowners insurance, collected through an escrow account. A tax estimate built on the seller’s capped bill understates the payment.
- A flood zone can add a required policy, and its premium is part of the payment from the first month.
- Association dues count in qualifying. Lenders add monthly dues to the housing payment when they figure your debt-to-income ratio, so higher dues leave less room for the loan itself.
Research done before the offer lets your price rest on real numbers. A homebuying budget review works out the payment you are comfortable with, which is a different number from the largest loan a lender might offer.
Your checklist: what to look up, and where
- City or township, county, school district: Census Geocoder, the listing or tax bill, the district office
- Which police agency covers the address: the city, township or county website
- Several years of crime reports: that agency, the Crime in Michigan dashboard, the FBI Crime Data Explorer
- Flood zone and other hazards: FEMA’s flood maps, FloodSmart, the seller disclosure
- Commute and housing costs: data.census.gov tables S0801 and DP04, a weekday drive, Mi Drive
- Taxable value, exemption and special assessments: the city or township assessor and treasurer
- Millage and a planning tax figure: Treasury’s estimator, Align’s Michigan property tax calculator
- Insurance quotes on the address, flood included if needed: two or more insurers, the DIFS guide, FloodSmart
- Master plan, zoning, agendas: the city or township website
- Utilities, internet, a year of bills: the MPSC map, the FCC map, the seller
- Association documents and dues: the seller or association, HUD’s FHA condo list
- District reports: MI School Data and the Annual Education Report
How Align moves your purchase to the closing table
Over the last 12 months, Samantha's loans averaged under 14 days from application to clear to close, across more than 100 loans. Your closing date is set by your purchase agreement. Her job is to have your loan ready well before it.
She handles your file herself, with a processor supporting her behind the scenes. You always know who to call, and the person who answers knows your goals.
Build your homebuyer game plan
Sources: Align Lending loan records, 12 months to October 2026.
FAQ: Researching a city before you move
Why won’t a mortgage broker tell me which neighborhood to choose?
Because where to live is your decision. Fair housing law bars lenders, brokers and agents from steering buyers toward or away from areas based on who they are, and the Fair Housing Act explains the rules. Align points you to the public records and helps with the numbers. Samantha can show what taxes, insurance and dues add to the payment on any address you choose.
Is the seller’s property tax bill what I would pay in Michigan?
Usually not. A Michigan home’s taxable value is capped while one owner holds it. The year after it sells, taxable value resets to half of the assessor’s market value, so the bill often rises. Plan with the property’s millage and your own purchase, not the seller’s bill. Align’s Michigan property tax calculator does that math from the address.
Do I need flood insurance if the home is not in a high-risk flood zone?
The federal requirement for a federally backed mortgage applies in high-risk zones, though a lender can ask for coverage elsewhere. FloodSmart notes that most homeowners insurance does not cover flood damage and that almost a third of flood insurance claims come from outside high-risk areas. A policy normally starts 30 days after purchase.
Why do crime numbers for the same place differ between sources?
Sources count differently. The FBI credits each crime to the agency that reported it, while the Michigan State Police also publishes counts by the city or township where the crime happened. Reports arrive late and get corrected, and some agencies miss a year. Compare the same source across several years rather than mixing sources.
How early should I do this research?
Before you write an offer, and ideally before you tour. Taxes, insurance, flood coverage and association dues all change the monthly payment, and some answers, like an insurance quote or association documents, take days to arrive. Starting early lets you set your price range on real numbers instead of learning them at the closing table.
The bottom line on researching a city
Found a home you want to look at closely? Samantha Shelton can walk through the monthly payment on that specific address, with its real taxes, insurance and any association dues, before you write the offer. Call or text 248-506-5727, or start with a homebuyer game plan.
Sources: Census Geocoder (U.S. Census Bureau); Crime in Michigan dashboard (Michigan State Police); MICR annual reports (Michigan State Police); Crime counts, jurisdiction and city/township code usage (Michigan State Police); Crime Data Explorer (FBI); Flood Map Service Center (FEMA); What is my flood zone? (FloodSmart, National Flood Insurance Program); Buy a policy, waiting period (FloodSmart); FloodSmart home page (NFIP); Resilience Analysis and Planning Tool, home of the National Risk Index (FEMA); Seller Disclosure Act, Act 92 of 1993 (Michigan Legislature); data.census.gov, American Community Survey tables S0801 and DP04 (U.S. Census Bureau); Mi Drive map (Michigan Department of Transportation); Projects and studies (Michigan Department of Transportation); Regional Price Parities by State and Metro Area (Bureau of Economic Analysis); Transfer of ownership (Michigan Department of Treasury); Property Tax Estimator and millage rates (Michigan Department of Treasury); Principal Residence Exemption (Michigan Department of Treasury); Save Our Homes assessment limitation (Florida Department of Revenue); Purchasing home insurance FAQ (Michigan DIFS); Department of Insurance and Financial Services (Michigan); Electric utility service area map (Michigan Public Service Commission); National Broadband Map (Federal Communications Commission); FHA-approved condominium search (HUD); MI School Data (State of Michigan); Annual Education Report (Michigan Department of Education); Data, reports and dashboards (Ohio Office of Criminal Justice Services); Ohio Department of Insurance; Crime statistics (North Carolina State Bureau of Investigation); North Carolina Department of Insurance; UCR offense data (Florida Department of Law Enforcement); Florida Office of Insurance Regulation; Louisiana Department of Insurance; Crime in Texas (Texas DPS); Texas Department of Insurance; State insurance departments directory (National Association of Insurance Commissioners); What is an escrow or impound account? (Consumer Financial Protection Bureau); Housing discrimination under the Fair Housing Act (HUD).
This article is for informational purposes only and is not intended to provide legal, financial, insurance or tax advice. Public data sources change their methods and update their figures; check each source for the address you are considering. Align Lending does not rate or rank places, neighborhoods or schools. Align Lending is an independent Michigan mortgage broker, NMLS #2041154.
Related resources
12-minute read
The home appraisal process: What to expect
Learn how the home appraisal process works, from the lender’s order to the final report, including typical costs of $300 to $1,500 and what appraisers check.
12-minute read
Home inspection checklist for buyers: What to look for room by room
See the complete home inspection checklist for buyers, from foundation to attic, so you can spot costly problems before you close on your next home.
12-minute read
How to prepare for a home closing: your step-by-step checklist
Learn how to prepare for a home closing with a step-by-step timeline, documents to bring, and final walk-through tips for a smooth closing day.
