
Homeowners insurance deductibles: How they work and how to choose one
A homeowners insurance deductible is the amount you pay out of pocket on a covered claim before your insurer pays anything, and it applies to each claim rather than once a policy year. Most homeowners and renters insurers offer a minimum deductible of $500 or $1,000, with higher options widely available. The per-claim detail is what surprises people: if hail damages your roof in May and a pipe bursts in November, a $1,000 deductible costs you $2,000 across the two claims, not $1,000.
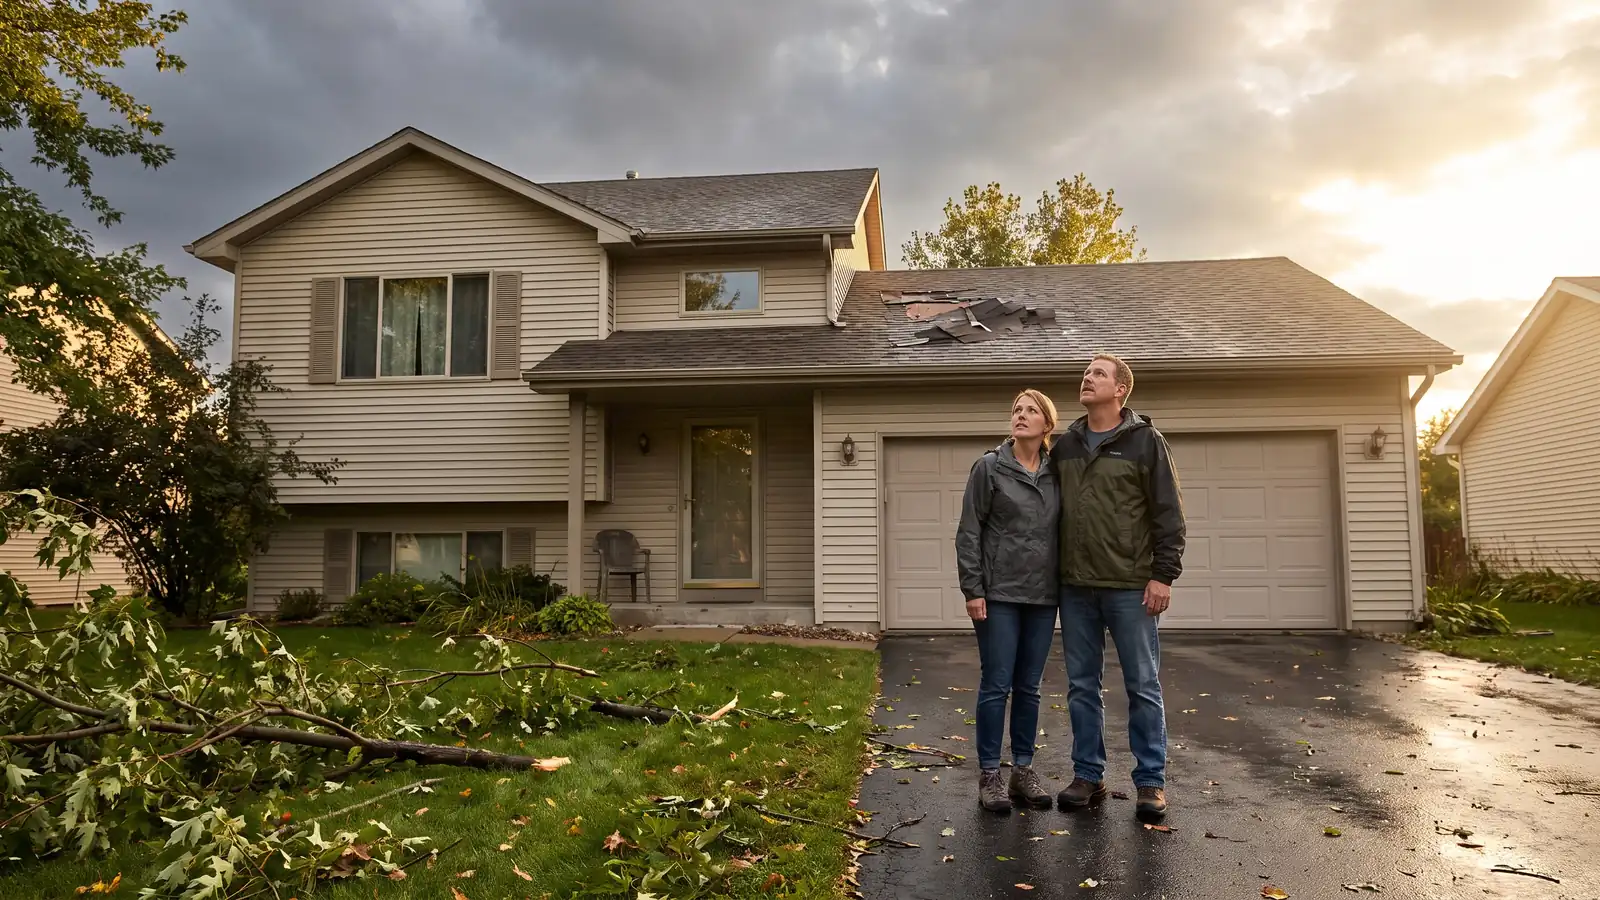
Wind, hail and named-storm losses often work differently. Those perils frequently carry a separate percentage deductible, typically 1% to 5% of the home’s insured value, and higher in some high-wind coastal areas, instead of the flat dollar amount that applies to fire or theft.
Learn how homeowners insurance deductibles work, including flat dollar versus percentage deductibles, what raising yours does to your premium, and how to land on a number you could write a check for tomorrow. Our Insurance & Protection guide covers the decisions that sit next to this one.
Key takeaways:
- Per claim, not per year: The deductible comes out of every covered claim payment, so two covered losses in the same year with a $1,000 deductible cost you $2,000 out of pocket, not $1,000.
- Two kinds, two very different bills: Flat deductibles start at a $500 or $1,000 minimum at most insurers, while percentage deductibles for wind, hail and named storms typically run 1% to 5% of the home’s insured value. 2% on a home insured for $300,000 is $6,000.
- Raising it lowers your premium, up to a ceiling your lender sets: The Texas Department of Insurance reports the $500 to $1,000 step can cut a premium by as much as 20%, while Fannie Mae caps the deductible on a one- to four-unit property at 5% of the coverage amount.
How does a homeowners insurance deductible work?
Your deductible is subtracted from the claim payment every single time you file, which is the rule that separates home insurance from health insurance in most people’s minds. The Texas Department of Insurance puts it plainly: for home and auto policies, the deductible is applied to each claim. There is no running annual total and no point at which the year’s claims are “paid up.”
The mechanics are arithmetic. On a covered $6,500 roof repair with a $500 deductible, the insurer pays $6,000. On a covered $900 loss with a $1,000 deductible, the insurer pays nothing. Which is why filing a claim at or barely above your deductible rarely makes sense.
Your exact deductible is printed on the declarations page, the front page of your policy, alongside each coverage limit. Our guide to evaluating home insurance options walks through that page line by line.
Which coverages does the deductible apply to?
The Insurance Information Institute guidance on homeowners coverage states the rule directly: deductibles generally apply to property damage, not to the liability portion of a homeowners or auto policy.
- Dwelling coverage: The house itself, including attached structures and the plumbing, heating and electrical inside it. Your deductible applies.
- Other structures: Detached garages, sheds and fences. Your deductible applies.
- Personal property: Furniture, clothing, electronics and the rest of the contents. Your deductible applies, sometimes in a different amount than the dwelling.
- Personal liability: Costs tied to injuries or damage you’re legally responsible for. No deductible generally applies.
- Medical payments: Bills for someone hurt on your property, paid without a liability claim. No deductible generally applies.
Flat dollar vs. percentage deductibles: what’s the difference?
A flat dollar deductible is a fixed number that applies to most covered losses, while a percentage deductible is a share of your dwelling coverage reserved for specific perils like wind, hail or a named storm. The Insurance Information Institute describes them as two separate things: the traditional dollar deductible handles losses such as fire damage and theft, while insurers use percentage deductibles for storm damage, so one policy can carry both.
| Feature | Standard (flat dollar) deductible | Percentage deductible |
|---|---|---|
| Typical amount | Most insurers offer a minimum of $500 or $1,000, with higher options widely available | Typically 1% to 5% of the home’s insured value for wind/hail; higher in some high-wind coastal areas |
| Perils it applies to | Most covered losses, fire, theft, burst pipes, falling trees, vandalism | Only the scheduled perils, usually wind, hail or a named storm |
| Out of pocket on a home insured for $300,000 | Whatever you selected. A $1,000 deductible is $1,000 | 2% is $6,000; 5% is $15,000 |
| Does it grow as your coverage grows? | No, it stays the number on your declarations page | Yes, the dollar figure rises with the insured value |
| Who sets it | You choose from the carrier’s menu | The insurer decides the level and where it applies, subject to state rules |
Standard flat dollar deductibles
This is the deductible most people mean when they say “my deductible,” and $500 and $1,000 are the common starting points because that’s where most carriers set their minimum. It covers everyday claims, a kitchen fire, a stolen laptop, a tree through the roof, and it doesn’t move when your dwelling limit is updated at renewal. That’s what makes it easy to plan around: if your deductible is $2,500, then $2,500 is the number your emergency fund has to cover, this year and next.
Percentage deductibles for wind, hail and named storms
A percentage deductible is calculated as a specified percentage of the insured value of the property, so the higher your dwelling coverage climbs, the more you pay before coverage starts. On a home insured for $300,000, a 2% deductible means you absorb the first $6,000 of a covered wind or hail loss; at 5%, the same home carries a $15,000 deductible.1
Keep two distinctions straight. A hurricane or named-storm deductible applies only to damage from a named storm. A windstorm or wind/hail deductible applies to any kind of wind damage, a far broader trigger. The Insurance Information Institute notes those wind/hail deductibles are most common where severe windstorms and hail are routine, including Midwestern states and Tornado Alley, and that they are most commonly paid in percentages, typically from 1% to 5% of insured value.
Because coverage amounts drift upward with rebuilding costs, a percentage deductible you accepted five years ago can be a much larger number today even though the percentage never changed, one reason to re-read your policy annually, alongside the changes tracked in our overview of updates to homeowners insurance regulations.
How your deductible changes your premium
Raising your deductible lowers your premium, and the first step is usually the biggest: the Texas Department of Insurance reports that switching from a $500 deductible to a $1,000 deductible can save as much as 20% of your premium. The rule behind it is the one the National Association of Insurance Commissioners states plainly: higher policy deductibles mean lower policy premiums, because you are absorbing the losses the insurer would otherwise pay first.
What the savings are worth depends on how long you go without a claim. Divide the extra money you’d owe on a claim by the premium you save each year, and that’s roughly the number of claim-free years the higher deductible needs to pay for itself.
| Deductible | Direction of your premium | Added out of pocket vs. $500 | Claim-free years to break even |
|---|---|---|---|
| $500 | Highest of the four | n/a | n/a |
| $1,000 | Lower up to 20% off, per the Texas Department of Insurance | $500 | $500 divided by your annual savings |
| $2,500 | Lower still, though each added dollar of risk buys less savings | $2,000 | $2,000 divided by your annual savings |
| $5,000 | Lowest premium, largest cash requirement | $4,500 | $4,500 divided by your annual savings |
Run it with your own quote. Say a carrier prices the move from $500 to $1,000 at $150 a year less. You’ve taken on $500 of extra exposure to save $150 annually, so you’re ahead after roughly three and a half claim-free years, and behind if you file in year one. Ask your agent to quote every tier at once; the savings between tiers are rarely proportional, and the sweet spot is often the middle option.
How to choose the right deductible
Pick the largest deductible you could pay tomorrow without borrowing, that one test resolves the decision faster than any premium comparison. Michigan’s Department of Insurance and Financial Services frames the same point from the claim side: know the deductible you’ll be responsible to cover before your insurance company pays the claim.
- What is actually liquid? Not retirement savings and not a credit line. Cash you could move in 48 hours. If that figure is $1,500, a $5,000 deductible is a discount you can’t afford to collect.
- Is there a separate wind/hail deductible? Check the declarations page. A low flat deductible does nothing about a 2% wind deductible behind it, and that’s the one most likely to be triggered by the storm that finally hits your roof.
- What is your lender’s ceiling? Fannie Mae’s Selling Guide caps the deductible for all required property insurance perils on a one- to four-unit property at 5% of the property insurance coverage amount, and where separate deductibles apply to perils such as windstorm or wildfire, each must independently stay within that cap.2
One piece of housekeeping: if your taxes and insurance are escrowed, changing your deductible changes your premium, and that changes your monthly payment. The CFPB explains how escrow accounts handle insurance premiums: when premiums change year to year, the escrow payment and your total payment change accordingly. Tell your servicer so the account is re-analyzed instead of running short, our guide to mortgage escrow accounts covers shortages and surpluses.
Three myths about homeowners insurance deductibles
Three beliefs cause most deductible mistakes, and each one costs money in a different way.
Myth: you always pay the same deductible
Reality: one policy can carry more than one. Your flat deductible may apply to fire and theft while a separate percentage deductible applies to wind and hail, and personal property sometimes carries a different amount than the dwelling. Each amount is established by the terms of your coverage and appears on the declarations page. Read all of them, not the first one you find.
Myth: a lower deductible is always better
Reality: a low deductible is a purchase, and you pay for it every year whether or not you file. Higher deductibles mean lower premiums, and the first step up is proportionally the largest, the gap between a $500 and a $1,000 deductible runs up to 20% of the premium, per the Texas Department of Insurance. A household with a funded emergency account is usually better off buying the higher deductible and keeping the difference.
Myth: your deductible is all that stands between you and any damage
Reality: some losses aren’t covered at any deductible. Flood is the big one. Most homeowners and renters insurance does not cover flood damage, that comes from FEMA’s National Flood Insurance Program or a private flood insurer, on a separate policy with its own deductible. NFIP coverage normally takes effect 30 days after purchase, though there’s no waiting period when you buy it in connection with making, increasing, extending or renewing a mortgage. Earthquake is typically excluded too. Our guide to flood insurance: when and why you need it covers who needs a policy and when to buy, and none of it touches title insurance, a separate one-time policy protecting your ownership rather than the building.
What Michigan homeowners should know
Michigan’s deductible exposure is a wind, hail and ice story rather than a hurricane story, and that changes which line on your declarations page matters most.
- No hurricane deductible, but check for a wind/hail one: Michigan is not among the 19 states and the District of Columbia the Insurance Information Institute lists as having hurricane deductibles, so your policy shouldn’t carry one. A windstorm or wind/hail deductible is a different product, can still be scheduled by your carrier, and applies to any wind damage.
- Winter losses are covered, and each carries its own deductible: Michigan DIFS advises that standard homeowners policies cover a wide range of winter-related disasters including burst pipes, ice dams, wind damage, leaky roofs and a building collapse caused by the weight of ice or snow. A January ice dam and a June hailstorm are two deductibles in one year.
- Roof claims are paid by the damaged section: DIFS is direct here. If hail and high winds lift shingles off your roof, the policy covers only the portion of the roof that has been damaged, and the insurance company is not required to replace the entire roof. On a partial roof claim, a $2,500 or 2% deductible can consume most of the payout.
DIFS runs a consumer help line at 877-999-6442 for Michigan policy questions. The practical takeaway is the one its claims guidance keeps returning to: know what your deductible is, and have a plan for paying it, before you need to. The wider ownership costs this fits into are covered in our Homeownership guide.
How Align handles insurance and taxes in your payment
Insurance is part of your monthly cost whether it is escrowed or not, so Samantha prices the full payment before you commit, not just principal and interest.
She also builds in Michigan's tax uncapping. The year after a Michigan home sells, its taxable value resets to half of the assessor's market value, so the seller's tax bill is not your tax bill. She quotes your number, not theirs.
Get a homebuying budget review
Sources: Michigan Treasury, transfer of ownership and uncapping.
FAQ: Homeowners insurance deductibles
Here are answers to common questions about homeowners insurance deductibles.
What is the average homeowners insurance deductible?
Most insurers set their minimum at $500 or $1,000, and those two amounts are where the majority of homeowners land, with higher options widely offered. The average is a starting point, not a recommendation. The right number is the amount you could write a check for tomorrow without borrowing, because you pay it every time you file a covered claim. Comparing tiers side by side is part of evaluating home insurance options.
Does a homeowners insurance deductible apply per claim or per year?
Per claim. Unlike health insurance, homeowners policies don’t track a running annual total, and state regulators describe the deductible as applied to each claim. If a storm damages your roof in April and a pipe bursts in November, you pay the deductible twice. That’s one reason filing small claims below or barely above your deductible rarely makes financial sense.
Will raising my homeowners insurance deductible lower my premium?
Yes. The Texas Department of Insurance reports that moving from a $500 to a $1,000 deductible can save as much as 20% of the premium, and larger jumps generally save more. The trade-off is real: you absorb more of every claim. Raising the deductible works best when you already hold that amount in accessible emergency savings, one of the reserves questions we walk through in our Homeownership guide.
Can I change my homeowners insurance deductible after buying the policy?
Yes. Most insurers let you adjust your deductible mid-term or at renewal, and your premium is recalculated accordingly. Two follow-ups matter. If your mortgage escrows your insurance, tell your loan servicer so the account is re-analyzed, as explained in our guide to mortgage escrow accounts. And confirm the new deductible still satisfies your lender’s requirements, since agency guidelines cap it as a percentage of your coverage amount.
The bottom line on homeowners insurance deductibles
A homeowners insurance deductible is subtracted from every covered claim payment, and it applies per claim rather than once a year. Most insurers start at a $500 or $1,000 minimum, while wind, hail and named-storm losses often carry a separate percentage deductible, typically 1% to 5% of the home’s insured value. 2% on a home insured for $300,000 is $6,000 out of pocket. Raising the deductible lowers the premium, with the $500 to $1,000 step worth as much as 20%, and Fannie Mae caps it on a one- to four-unit property at 5% of the coverage amount.
If you’re ready to see how insurance and escrow fit into the whole monthly payment, on a purchase, a refinance, or a payment that just jumped, talk to Align Lending. We’ll shop your scenario across our lender network and show you the numbers side by side. Call 248-506-5727 or start online.
Footnotes:
1. Every worked dollar example in this article is hypothetical and shown for educational purposes only. Including the $300,000 dwelling coverage figure, the 2% and 5% percentage-deductible results, the claim-payment illustrations, and the $150-per-year premium savings used in the breakeven example. They are not an advertisement of insurance or credit terms, an insurance quote, or a rate quote under federal or state lending laws. Your actual deductible options, premium and savings depend on your carrier, coverage amounts, location, claims history and the terms of your specific policy. Return to text.
2. Align Lending is an independent mortgage broker and does not sell insurance, set insurance terms, or set loan terms. The 5% maximum deductible cited is Fannie Mae’s published Selling Guide requirement for conventional loans on one- to four-unit properties; other investors, government loan programs, and the individual wholesale lenders in Align’s network may apply different or additional insurance requirements, and all guidelines are subject to change. Confirm your own lender’s requirement before changing a deductible. Nothing here is an offer of credit or a commitment to lend. Return to text.
Sources: deductible definition, per-claim application, “in general, the higher the deductible, the lower the cost for the policy,” and the finding that switching from a $500 to a $1,000 deductible can save as much as 20% of the premium, Texas Department of Insurance. Minimum $500 or $1,000 deductible offerings, wind/hail percentage deductibles typically of 1% to 5% of insured value, the regions where wind/hail deductibles are most common, percentage deductibles as a share of the home’s insured value and their separateness from the traditional dollar deductible, the 19 states and District of Columbia with hurricane deductibles, the rule that deductibles apply to property damage and not the liability portion, and declarations-page placement, Insurance Information Institute. “Higher policy deductibles mean lower policy premiums,” the standard coverage parts and typical limits, and the flood and earthquake exclusions, National Association of Insurance Commissioners, “A Consumer’s Guide to Home Insurance.” Michigan coverage of burst pipes, ice dams, wind damage, leaky roofs and collapse from the weight of ice or snow, the partial-roof claim rule, knowing your deductible before the claim is paid, and the 877-999-6442 help line, Michigan Department of Insurance and Financial Services. Maximum allowable deductible of 5% of the property insurance coverage amount, Fannie Mae Selling Guide B7-3-02. Flood not covered by most homeowners and renters insurance, the 30-day NFIP waiting period and the mortgage-transaction exception, FEMA National Flood Insurance Program. Escrow mechanics and annual payment changes, Consumer Financial Protection Bureau.
This article is for informational purposes only and is not intended to provide legal, financial, tax, or insurance advice. Align Lending is a mortgage broker and does not sell, place, or underwrite homeowners insurance. Policy terms, deductible options, exclusions, premiums and lender insurance requirements vary by carrier, state, investor and property, read your own policy and confirm current requirements with your insurer, your agent and your loan servicer before making a change. Align Lending is an independent Michigan mortgage broker, NMLS #2041154.
Related resources
12-minute read
How to evaluate home insurance options: Coverage, limits and quotes
Learn how to evaluate home insurance options by comparing dwelling limits, deductibles, exclusions and discounts so your coverage truly rebuilds your home.
12-minute read
Home insurance and renovations: What to tell your insurer
Learn how renovations change your home insurance, which upgrades raise or lower premiums, and why calling your insurer before demolition protects you.
12-minute read
Fire safety tips for homeowners: What actually prevents home fires
Learn fire safety tips for homeowners that actually reduce risk, from smoke alarm placement and kitchen habits to escape plans and electrical checks.
