
Flood insurance: When it’s required, what it covers and what it costs
Flood insurance is a separate policy that pays for flood damage your homeowners policy won’t, because every standard homeowners policy excludes flood entirely. It’s legally required when a home inside a FEMA-designated Special Flood Hazard Area secures a federally backed mortgage, and worth pricing everywhere else, because FEMA reports that 29% of National Flood Insurance Program claims filed from 2014 through 2024, nearly 1 in 3, came from properties outside mapped high-risk areas.
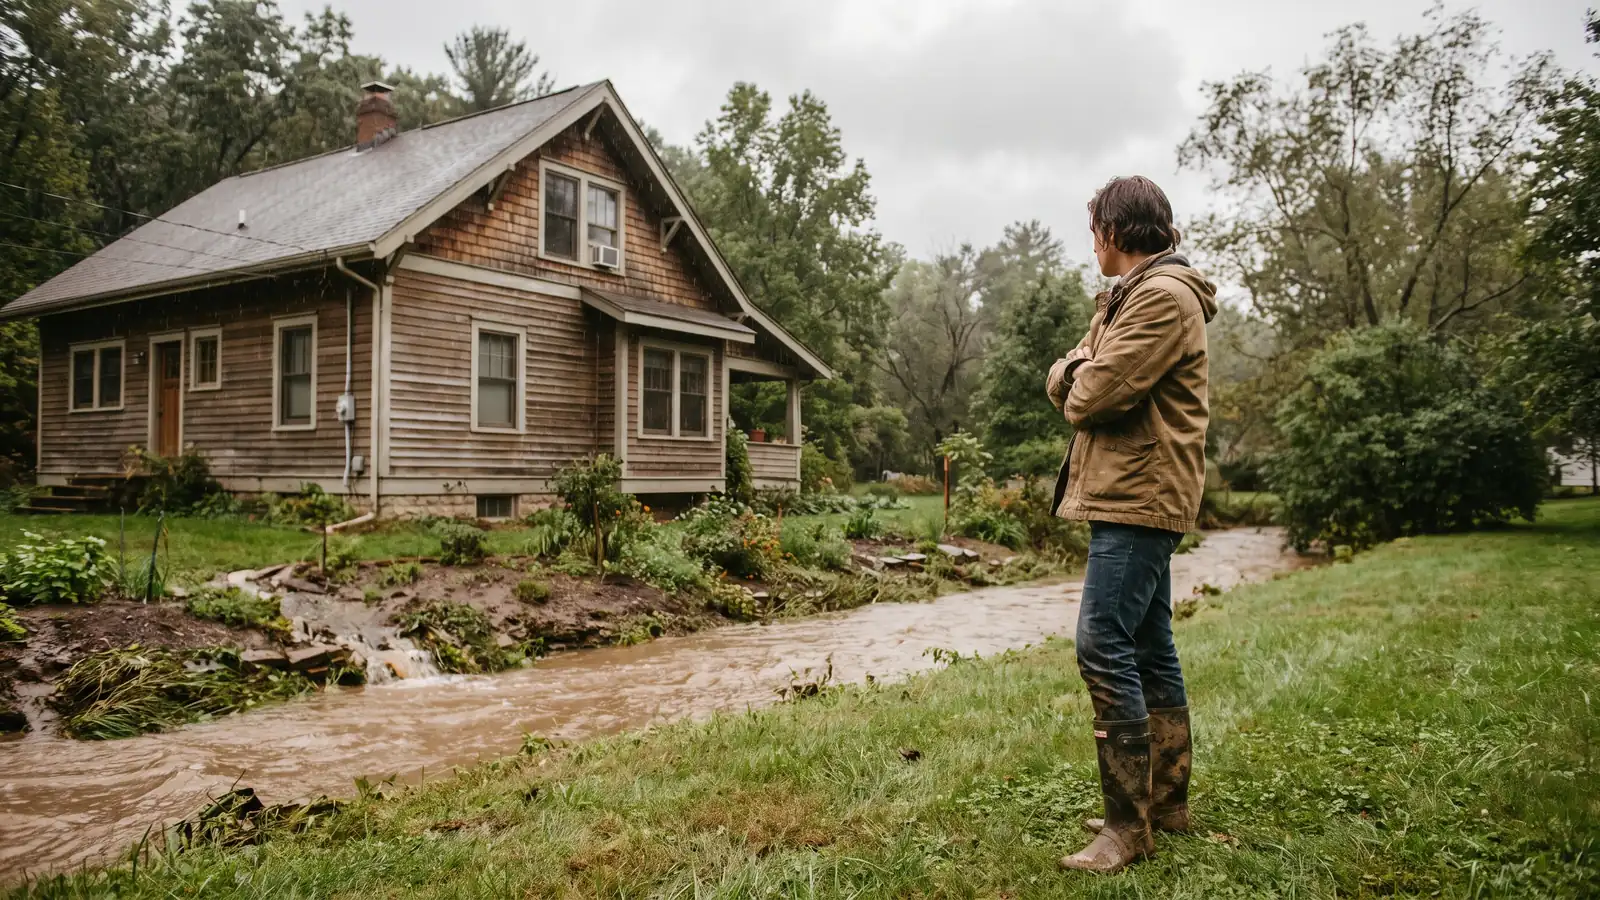
The detail that catches buyers off guard is timing. Most new NFIP policies don’t take effect for 30 days, so you can’t buy coverage when the forecast turns. The exception that matters most is built for closings: there’s no waiting period when you buy flood insurance in connection with making, increasing, extending or renewing a mortgage.
Learn how flood insurance works, including when it’s required, what it covers, what it costs, and how the waiting period affects your closing date, one piece of the broader Insurance & Protection guide.
Key takeaways:
- Homeowners insurance excludes flood, period: Flood damage takes a second policy. An NFIP residential policy caps building coverage at $250,000 and contents at $100,000, bought separately with separate deductibles.
- Lenders enforce it inside the flood zone: Federal law requires flood insurance on a federally backed mortgage when the building sits in a FEMA Special Flood Hazard Area, the requirement runs for the life of the loan, and a servicer must force-place coverage within 45 days of notifying you if it lapses.
- Nearly 1 in 3 claims come from outside high-risk zones: FEMA puts that share at 29% for claims filed between 2014 and 2024, and 37% of single-family NFIP policies nationally cost less than $1,000 a year.
What is flood insurance?
Flood insurance is a standalone property policy covering direct physical loss caused by flooding, a peril standard homeowners and renters policies exclude. You buy it either from the National Flood Insurance Program, which FEMA runs through participating private insurers, or from a private flood carrier.
The word “flood” is narrower in a policy than in conversation. The NFIP defines it as a general and temporary condition of partial or complete inundation of two or more acres of normally dry land, or of two or more properties, at least one of which is yours, caused by overflowing inland or tidal water, unusual and rapid runoff of surface water, mudflow, or shoreline collapse from wave erosion. That threshold does real work: water that ruins your basement because a supply line burst, a sump pump quit or a sewer backed up isn’t a flood here. Our guide to addressing water damage in your home covers which policy picks up which kind of water.
The gap is expensive. Between 2016 and 2022 the average FEMA disaster assistance grant was $3,000, while the NFIP paid an average claim of more than $66,000, and grants require a presidential disaster declaration that most floods never get. FEMA’s planning estimate is that just one inch of water in a home can cause more than $25,000 in damage.1
When is flood insurance required?
Flood insurance is federally required when a building in a Special Flood Hazard Area secures a loan from a federally regulated or insured lender, the mandatory purchase requirement created by the Flood Disaster Protection Act of 1973. That covers most mortgages, including conventional loans sold to Fannie Mae or Freddie Mac and government-backed FHA, VA and USDA loans.
Three mechanics surprise borrowers most often.
- The amount is set by formula: Your lender must require at least the lesser of the outstanding principal balance or the NFIP maximum, $250,000 for a residential building. Insuring only to the loan balance protects the lender, not necessarily you.
- It lasts the life of the loan: The obligation ends when the loan is paid off, or when a map revision moves your building out of the Special Flood Hazard Area and your lender accepts it.
- Lapses get expensive fast: If you never buy the required policy or let it lapse, your servicer must force-place coverage within 45 days of notifying you and bill you. Typically well above what you’d have paid on your own.
Outside the Special Flood Hazard Area no law requires coverage, though a lender can still condition a loan on it. The flood zone determination is ordered during underwriting, and if it comes back showing an SFHA, the policy has to be in place before closing. If you’re shopping in or near a mapped zone, read our guide to buying a home in a flood zone before you write an offer. The premium belongs in your payment math from the start.
What does flood insurance cover?
An NFIP policy covers the building and its contents, but only if you buy both, capped at $250,000 for a residential building and $100,000 for contents. They’re separate purchases with separate deductibles, and skipping contents is the most common under-insurance mistake.
- Building coverage: The structure and its permanent systems, foundation, electrical, plumbing, central air, furnace, water heater, built-in appliances, permanently installed cabinets, and debris removal.
- Contents coverage: Personal belongings, clothing, furniture, electronics, portable air conditioners, washers and dryers, food freezers and their contents, and valuables such as artwork, furs and jewelry up to $2,500.
- Increased Cost of Compliance, up to $30,000: Included in most policies, it helps elevate, demolish, relocate or floodproof a building your community declares substantially damaged, repairs costing 50% or more of pre-damage market value.
How a claim is paid matters as much as what’s covered. If your building coverage equals at least 80% of the home’s replacement cost and the home is your principal residence, a building claim settles at replacement cost. Contents claims always settle at actual cash value, replacement cost minus depreciation.
Excluded outright: most self-propelled vehicles; everything outside the building, including trees, wells, septic systems, decks, patios, fences, seawalls and pools; additional living expenses such as temporary housing; preventable mold or mildew; water moving beneath the earth’s surface, including seepage; and sewer backup, unless a flood caused it.
The basement limitation, in plain terms. NFIP basement coverage is narrow, and it’s the exclusion homeowners discover at the worst moment. FEMA counts any area with a floor below ground level on all sides as a basement including sunken rooms, crawlspaces and the lower level of a split-level home.
Covered: furnaces, water heaters, central air conditioners, heat pumps, sump pumps, well tanks and pumps, fuel tanks, outlets, switches and breaker boxes, elevators, attached stairways, unfinished drywall, foundation elements, and floodwater cleanup.
Not covered: personal property such as couches, computers and televisions; basement improvements including finished flooring, finished walls, bathroom fixtures and built-ins; generators; and dehumidifiers not integral to the HVAC system. Even with contents coverage, only washers and dryers, portable or window air conditioners, and food freezers with their contents qualify, and only if connected to a power source. A finished basement is largely on you.
NFIP vs. private flood insurance: how they compare
Both markets are real options. Since July 1, 2019, federal regulators have required lenders to accept a private flood policy that meets the regulatory definition of private flood insurance in place of an NFIP policy. Which is why quoting both is worth your time.
| Feature | NFIP policy | Private flood policy |
|---|---|---|
| Building coverage limit | $250,000 maximum for a residential building | Set by the carrier; higher limits are commonly available for homes worth more than the NFIP cap |
| Contents coverage | Up to $100,000, purchased separately, always paid at actual cash value | Varies by carrier; confirm limits and whether contents are actual cash value or replacement cost |
| Waiting period | 30 days, with exceptions including no wait at a mortgage closing | Set by the carrier; get the effective date in writing |
| Basement treatment | A defined list of building items, cleanup, and a short list of powered contents | Varies by policy form; read the basement and enclosure language line by line |
| Availability | Only in communities that participate in the NFIP | Depends on carrier appetite for your property; not offered everywhere |
One quirk worth knowing: FEMA sells NFIP policies through more than 50 private insurers, and the price is identical at every one given the same rating information. Shopping the NFIP itself won’t lower your premium; shopping the private market against it might. The Insurance Information Institute explains how flood coverage differs from a homeowners policy.
How much does flood insurance cost?
Nationally, most single-family flood policies land in a narrow band: 37% cost less than $1,000 a year and 32% cost between $1,000 and $2,000, based on FEMA data for policies in force as of August 31, 2023.2 Your number depends on the building’s elevation and construction, distance to flooding sources, rebuild cost, and the coverage and deductibles you pick, not just the zone letter on the map.
Two levers move the premium in your favor.
- Community Rating System discounts of 5% to 45%: If your community participates in FEMA’s voluntary Community Rating System, every NFIP policy there earns a discount tied to the community’s class, in 5% increments, 5% for a Class 9 community up to 45% for a Class 1. Class 10 communities don’t participate. Ask your agent for your class.
- Deductible selection: Building and contents carry separate deductibles, and raising them lowers the premium while raising what you’d pay out of pocket. Our guide to homeowners insurance deductibles covers sizing that trade.
Price flood against your whole protection budget, not in isolation. Comparing carriers across every policy you hold, covered in our guide to evaluating home insurance options, usually finds more savings than fixating on one line, and the cheap-prevention-beats-expensive-claim logic behind preventing home burglaries applies here too.
How does the 30-day waiting period work?
An NFIP policy normally takes effect 30 days after you buy it. That’s deliberate: it stops people from buying coverage once a storm is already on the radar, which is why a flood policy has to be a planning decision rather than a reaction.
Four exceptions shorten or eliminate the wait.
- Mortgage transactions, no wait: Coverage bought in connection with making, increasing, extending or renewing a loan takes effect without the 30-day delay. This is the exception that protects your closing date.
- Policy renewal changes, no wait: Changing coverage at renewal doesn’t restart the clock.
- Newly mapped into a high-risk zone, one day: The wait drops to one day if a map update puts your property in a newly designated high-risk zone and you buy within 12 months.
- Post-wildfire flooding, one day: The same one-day wait applies when flooding is caused or worsened by a wildfire on federal land and you buy within 60 days of containment.
Two practical consequences. In a Special Flood Hazard Area, the mortgage exception applies and the policy can be bound in time for closing. If you’re buying voluntarily, start 30 days ahead of when you want coverage. FEMA lays out its case for coverage outside mapped zones in its explanation of why flood coverage matters outside high-risk zones, and you can price a policy through the FEMA National Flood Insurance Program overview.
What Michigan homeowners should know
Michigan isn’t a coastal-hurricane state, which is exactly why flood exposure here gets underestimated. The state’s own numbers tell a different story.
- About 6% of Michigan’s land is flood-prone: That’s the estimate from Michigan’s Department of Environment, Great Lakes, and Energy. The regulatory floodplain is the 100-year floodplain, a 1% chance of flooding in any given year, which compounds to roughly a 26% chance over a 30-year mortgage.3
- Not every community is mapped: EGLE reports about 1,004 of Michigan’s 1,776 cities, villages and townships have FEMA-developed floodplain maps. No map doesn’t mean no risk. It often means no study has been done.
- Great Lakes levels move in cycles: Every Great Lake set record high water levels at some point between 2017 and 2020 before receding, per NOAA’s Great Lakes Environmental Research Laboratory. Shoreline erosion and coastal flooding track those swings, and lake-driven erosion is one of the four causes in the NFIP’s flood definition.
- Finished basements are the Michigan-specific gap: Michigan homes are full of them, and NFIP basement coverage excludes finished flooring, finished walls, bathroom fixtures, built-ins and personal property. Michigan’s Department of Insurance and Financial Services also notes that water and sewer backup coverage is a separate homeowners endorsement that generally doesn’t cover flood, so a failed sump pump and a river over its banks are two different claims under two different policies.
Buying near the Grand, Saginaw, Huron or Clinton rivers, or along the lakeshore? Treat flood risk as part of the affordability math, our Homeownership guide covers the rest of the ongoing-cost picture.
What happens when the flood zone determination comes back in a Special Flood Hazard Area?
The FDIC’s flood rule for the banks it supervises, 12 CFR Part 339 (eCFR text up to date as of October 23, 2026), requires the lender to use the standard flood hazard determination form developed by FEMA and to keep a copy for as long as it owns the loan. According to the same rule, the lender may charge you a reasonable determination fee when the determination is made because you applied for the loan, and that fee may include life-of-loan monitoring. It can appear among your closing costs.
When the building is in a Special Flood Hazard Area, Part 339 requires a written notice to you “within a reasonable time before the completion of the transaction,” and the lender must keep a record that you received it. The regulators’ sample notice tells the borrower that federal law allows a lender and borrower jointly to ask FEMA to review the determination, and that the area has a one percent (1%) chance of a flood equal to or exceeding the base flood elevation in any given year. Read it the day it arrives; the closing process keeps moving around it.
FEMA’s Flood Map Service Center describes itself as the official public source for flood hazard information and searches the official map by address. Samantha Shelton’s habit here: “I’d rather say, ‘Let’s check,’ than tell somebody something that doesn’t apply to them.” Near a river, drain or lakeshore, look up the map before you choose your contingencies.
Who holds the flood premium, and what happens after a lapse?
For a bank loan, escrow is the default for required flood premiums. Under section 339.5 of the FDIC’s flood rule, a lender or its servicer must escrow all premiums and fees for required flood insurance on a residential loan made, increased, extended or renewed on or after January 1, 2016, payable with the same frequency as your loan payments for the life of the loan. Per section 339.5(a)(2), the exceptions include home equity lines of credit, a second lien when the first already carries qualifying coverage, a condominium or homeowners association policy paid as a common expense, business purpose loans and loans 90 or more days past due. Under section 339.5(c), a bank with total assets under $1 billion that did not require escrow on or before July 6, 2012 can be exempt unless state law requires it.
Escrow does not freeze the bill. The Consumer Financial Protection Bureau’s escrow explainer says property taxes and insurance premiums “can change from year to year,” and the escrow payment and total monthly payment change with them. See mortgage escrow accounts and payments, escrow and servicing for the yearly analysis.
Section 339.7 lets the servicer charge you for premiums and fees on force-placed coverage starting from the date your own coverage lapsed, not only from the date it bought the policy. Once you send proof of your own coverage, the servicer has 30 days to cancel the force-placed policy and refund the premiums and fees for any period when both were in effect. The CFPB’s servicing rule, 12 CFR 1024.37, excludes insurance required by the Flood Disaster Protection Act of 1973 from its definition of force-placed insurance, so the flood rule governs a flood lapse.
Do FHA, VA, USDA and conventional loans follow the same flood rules?
According to HUD’s final rule in the Federal Register of November 21, 2022 (87 FR 70733), the Flood Disaster Protection Act requires the owner of a property mapped in a Special Flood Hazard Area, in a community participating in the NFIP, to buy flood insurance as a condition of a mortgage backed by Fannie Mae or Freddie Mac, VA, USDA or FHA. That rule, effective December 21, 2022, lets borrowers with FHA loans satisfy the requirement with private flood insurance. The same mandatory purchase rule follows VA loans and USDA loans.
For private policies, Part 339 lets a lender accept one without further review if it states: “This policy meets the definition of private flood insurance contained in 42 U.S.C. 4012a(b)(7) and the corresponding regulation.” Ask a private carrier whether that sentence is in the policy or an endorsement.
Conventional loans sold to Fannie Mae add their own terms. Per the Fannie Mae Selling Guide, B7-3-06 (published October 7, 2026), every flood zone beginning with the letter A or V is a Special Flood Hazard Area, and the minimum coverage on a first mortgage is the lesser of the replacement cost of the improvements, the maximum NFIP coverage or the unpaid principal balance. The deductible may not exceed the maximum NFIP offers. Fannie Mae also requires flood insurance in a Coastal Barrier Resources System unit or Otherwise Protected Area regardless of whether the property is in a Special Flood Hazard Area, and the U.S. Fish and Wildlife Service says that system covers 3.8 million acres, including areas along the Great Lakes coasts. Ask early on waterfront property.
For example, picture a home with a $280,000 loan balance whose building would cost $230,000 to replace. The bank rule’s floor is the lesser of $280,000 and the $250,000 NFIP building maximum, so $250,000; Fannie Mae’s three-way test adds replacement cost, so its minimum on that loan would be $230,000. Hypothetical example, not an offer.
What goes into an NFIP premium besides the flood zone?
FEMA’s FloodSmart premium page groups the rating into where the building is, how it is built and what coverage you choose. Beyond the factors listed earlier, its list includes ground elevation relative to surrounding land, foundation type, first-floor height, flood openings and the elevation of machinery and equipment.
An Elevation Certificate is optional for pricing now. According to a May 2022 FloodSmart article for agents, “an EC is no longer required to purchase coverage,” FEMA determines first-floor height itself as one rating factor, and an owner may still give an EC to the agent to see whether it lowers the cost.
Several charges sit on top of the premium itself:
| Charge | Amount per FloodSmart |
|---|---|
| Increased Cost of Compliance coverage | 1.9% of the building and contents premiums, not to exceed $75 |
| HFIAA surcharge | $25 for primary residences; $250 for all other occupancies |
| Federal Policy Fee | $47 for most policies |
| Yearly increase limit | 18% to 25% per year for most policyholders; usually not applied to new policies |
Source: FEMA, FloodSmart, Premium costs, read October 27, 2026.
FEMA reported that floods caused more than $8 billion in damage to homes and businesses in 2024, and $3.8 billion of it occurred in communities that are not considered high-risk, according to FloodSmart’s cost of flooding page. Count the premium and fees among the hidden costs of a purchase and in your first-home budget.
How can Michigan buyers check a home’s flood history before closing?
Michigan’s Seller Disclosure Act gives you questions in writing. The statutory form in MCL 565.957 asks whether there has been evidence of water in the basement or crawl space, whether the seller is aware of “Settling, flooding, drainage, structural, or grading problems,” whether there has been “Major damage to the property from fire, wind, floods, or landslides,” and, under item 11, “Do you have flood insurance on the property?” A yes there is a reason to ask for the declarations page and premium. Our guide to handling seller disclosures covers how to follow up.
Timing is set by MCL 565.954: the seller must deliver the statement before signing a binding purchase agreement. If it arrives after, the buyer may terminate by written notice within 72 hours of delivery in person or 120 hours of delivery by registered mail, a right that ends at the transfer by deed.
FEMA’s FloodSmart eligibility page says that after federal disaster assistance a property must carry flood insurance to qualify for future aid, and that this requirement is tied to the property, not the owner, so a buyer of such a home is required to have flood insurance. In Michigan, FEMA’s DR-4607 disaster page for the Michigan Severe Storms, Flooding, and Tornadoes of June 25 to 26, 2021, declared July 15, 2021, shows 56,531 approved Individual Assistance applications and $196,961,378.26 approved in total. If the disclosure mentions flood damage, ask whether federal aid was received. Michigan DIFS adds in FIS-PUB 0215 that federal disaster assistance is customarily offered as a low interest loan, and only if the President declares a major disaster.
Per EGLE’s floodplain mapping page, Water Resources Division staff provide an estimated 100-year floodplain elevation in state-regulated floodplains or where the division has usable data, through a MiEnviro request with a map of the property and an estimate of its height above the water and distance from it. EGLE says there is no charge and it may take 8 to 16 weeks, so request it during your due diligence, not the week of closing. Pair it with the grading and basement items on our home inspection checklist and the questions in evaluating a property’s location.
How Align handles insurance and taxes in your payment
Insurance is part of your monthly cost whether it is escrowed or not, so Samantha prices the full payment before you commit, not just principal and interest.
She also builds in Michigan's tax uncapping. The year after a Michigan home sells, its taxable value resets to half of the assessor's market value, so the seller's tax bill is not your tax bill. She quotes your number, not theirs.
Get a homebuying budget review
Sources: Michigan Treasury, transfer of ownership and uncapping.
FAQ: Flood insurance
Here are answers to common questions about flood insurance.
Is flood insurance required by law?
Federal law requires it when a property in a FEMA-designated Special Flood Hazard Area secures a federally backed mortgage. Outside those zones it’s optional. Lenders enforce the requirement at closing and monitor it for the life of the loan; if coverage lapses, the servicer must force-place a policy and bill you, typically above what you’d pay yourself. Our guide to buying a home in a flood zone covers how the determination is ordered.
How long does it take for flood insurance to take effect?
Most new NFIP policies have a 30-day waiting period, so you can’t buy coverage as a storm approaches. The exceptions: policies bought in connection with a mortgage take effect without the wait, and a one-day wait applies if you’re newly mapped into a high-risk zone and buy within 12 months, or after wildfire-related flooding on federal land within 60 days of containment. Price it early, alongside our guide to evaluating home insurance options.
Do I need flood insurance if I’m not in a flood zone?
It’s worth pricing. FEMA reports 29% of NFIP claims filed between 2014 and 2024 came from outside high-risk areas, and premiums outside Special Flood Hazard Areas are generally lower. The factors that matter most often aren’t on the map: sitting downhill from neighbors, a finished basement, a nearby creek or storm sewer outfall, upstream development that changed drainage. Weigh the premium against the deductible you could absorb, see homeowners insurance deductibles.
What does flood insurance actually cover?
NFIP building coverage pays for the structure, foundation, electrical and plumbing, furnace, water heater, built-in appliances and permanently installed cabinetry. Contents coverage is bought separately and pays for belongings at actual cash value. Basement coverage is sharply limited: finished walls, finished flooring, built-ins and most personal property are excluded, as are vehicles, outdoor property and temporary living expenses. For the water losses flood insurance doesn’t touch, see how to address water damage in your home.
How do I get my house removed from a flood zone?
Ask FEMA for a Letter of Map Amendment, which officially removes a property or structure from the Special Flood Hazard Area. FEMA’s LOMA page says requests go through the Online LOMC application or the MT-EZ form; in most cases a licensed land surveyor or registered professional engineer prepares an Elevation Certificate. FEMA charges no review fee and normally decides within 60 days; the lender may still require coverage.
Do I need flood insurance on a detached garage or pole barn?
Usually not for the loan. Section 339.4 of 12 CFR Part 339 exempts a structure that is part of a residential property, detached from the house with no structural connection, and not used as a residence, which generally means no sleeping, bathroom or kitchen facilities. A barn used mainly for farming or business is not exempt. The same section exempts loans of $5,000 or less with a repayment term of one year or less.
Can I get flood insurance if my town doesn’t participate in the NFIP?
Not from the NFIP. The regulators’ sample borrower notice in Appendix A to 12 CFR Part 22 says NFIP coverage is not available when the community does not participate, and that once such a community has been identified for at least one year as having a flood hazard area, its properties lose federal disaster relief after a declared flood. FEMA’s flood insurance page, updated October 20, 2026, counts 22,600 participating communities. A private carrier may still offer a policy.
Does water backup coverage pay to replace a broken sump pump?
Typically not. Michigan DIFS’s water and sewer backup guide (FIS-PUB 6380) lists repair or replacement of a broken sump pump and pump wear and tear among what backup coverage usually excludes. Insurers sell it up to a set limit or as a percentage of dwelling coverage, and DIFS suggests considering it if you have a finished basement or belongings stored there.
The bottom line on flood insurance
Flood insurance is a separate policy because homeowners insurance excludes flood entirely. It’s federally required when a building in a FEMA Special Flood Hazard Area secures a federally backed mortgage, and worth pricing outside those zones too, 29% of NFIP claims filed from 2014 through 2024 came from outside mapped high-risk areas. An NFIP residential policy caps building coverage at $250,000 and contents at $100,000, pays contents at actual cash value, and covers very little of a finished basement. Most policies take 30 days to take effect, but coverage bought in connection with a mortgage has no waiting period at all.
If you’re ready to buy or refinance where flood risk is part of the equation, talk to Align Lending. We’ll order the flood zone determination early so you see the result before closing, and shop your scenario across our lender network so you see the numbers side by side. Call 248-506-5727 or start online.
Footnotes:
1. The figure of more than $25,000 in damage from one inch of water in a home is FEMA’s planning estimate as published in its “Everyone Needs Flood Insurance” fact sheet (May 2023). It describes one inch of water in total, not a per-inch multiplier that scales with depth. It is an illustrative estimate, not a claim average and not a prediction for any particular property; actual damage depends on the size and construction of the building, what’s in the flooded area, and how quickly the water is removed. FEMA has published different flood-damage estimates in different documents and years. Return to text.
2. The premium distribution reflects FEMA’s published data for existing single-family NFIP policies in force as of August 31, 2023, under the Risk Rating 2.0 pricing methodology, and describes policies nationally rather than in Michigan. It is not a rate quote. Your premium is determined by the insurer using your property’s specific rating characteristics and the coverage and deductibles you select, and it changes over time. Return to text.
3. The roughly 26% figure is our own arithmetic from the stated 1% annual chance of a 100-year flood, compounded over 30 years, and assumes that annual probability stays constant. It is presented for illustration only. Actual flood probability at a given property changes with mapping updates, upstream development, drainage changes and long-term hydrologic conditions. Return to text.
Sources: NFIP definition of a flood, residential building and contents coverage limits of $250,000 and $100,000, separate purchase and separate deductibles for building and contents, covered building and contents items, coverage exclusions, replacement cost value settlement when building coverage equals at least 80% of replacement cost on a principal residence, actual cash value settlement for contents, and Increased Cost of Compliance coverage up to $30,000, FEMA, National Flood Insurance Program Summary of Coverage (P-2144, December 2023). Basement classification, covered and excluded basement building items, and the limited list of powered contents covered in a basement. FEMA fact sheet, “What Does Flood Insurance Cover in a Basement?” (January 2022). Share of NFIP claims from outside high-risk flood areas, 29% for 2014 through 2024. FEMA, FloodSmart.gov (“What Is My Flood Risk”). Average FEMA disaster assistance grant of $3,000 and average NFIP claim of more than $66,000 for 2016 through 2022, the estimate that just one inch of water in a home can cause more than $25,000 in damage, the typical 30-day waiting period, and the statement that NFIP pricing is identical across the more than 50 participating insurance companies given identical rating information. FEMA fact sheet, “Everyone Needs Flood Insurance” (May 2023). The 30-day waiting period and its exceptions for mortgage transactions, policy renewal, newly designated high-risk zones within 12 months, and post-wildfire flooding within 60 days of containment, FEMA, FloodSmart.gov (“Buy a Flood Insurance Policy”). Mandatory purchase requirement for federally backed loans in Special Flood Hazard Areas, coverage equal to the lesser of the outstanding principal balance or the maximum NFIP amount, and force placement within 45 days of borrower notice, Flood Disaster Protection Act of 1973 as described by FEMA and the FDIC Consumer Compliance Examination Manual (V-6). Mandatory lender acceptance of qualifying private flood insurance effective July 1, 2019, interagency final rule, “Loans in Areas Having Special Flood Hazards, Private Flood Insurance” (FDIC FIL-8-2019; OCC Bulletin 2019-8). Community Rating System discounts of 5% to 45% in 5% increments by community class, FEMA, Community Rating System. Premium distribution for single-family policies in force as of August 31, 2023. FEMA, “Cost of Flood Insurance for Single-Family Homes under NFIP’s Pricing Approach.” Estimate that about 6% of Michigan’s land is flood-prone, the 100-year floodplain definition, and roughly 1,004 of Michigan’s 1,776 communities having FEMA floodplain maps, Michigan Department of Environment, Great Lakes, and Energy (floodplain management pages). Record high Great Lakes water levels between 2017 and 2020 and their subsequent decline, NOAA Great Lakes Environmental Research Laboratory. Flood damage not covered under standard homeowners policies, and water and sewer backup coverage as a separate endorsement that generally does not cover flood, Michigan Department of Insurance and Financial Services.
This article is for informational purposes only and is not intended to provide legal, financial, tax, or insurance advice. Align Lending is a mortgage broker, not an insurance agency, and does not sell, place, or bind flood insurance. Coverage terms, exclusions, limits, waiting periods and premiums vary by policy, carrier, community and property, read your policy and confirm details with a licensed insurance agent before you rely on them. Federal flood insurance requirements and FEMA flood maps change over time; verify your property’s current flood zone designation. Align Lending is an independent Michigan mortgage broker, NMLS #2041154.
Sources
Every outside source this guide links to, in the order it appears. How we choose and check sources
- How flood coverage differs from a homeowners policyInsurance Information Institute
- Explanation of why flood coverage matters outside high-risk zonesFederal Emergency Management Agency
- FEMA National Flood Insurance Program overviewFEMA, National Flood Insurance Program
- Michigan’s Department of Environment, Great Lakes, and EnergyState of Michigan
- EGLE reports about 1,004 of Michigan’s 1,776 cities, villages and townships have FEMA-developed floodplain mapsState of Michigan
- Michigan’s Department of Insurance and Financial ServicesState of Michigan
- 12 CFR Part 339Electronic Code of Federal Regulations
- Flood Map Service CenterFEMA Flood Map Service Center
- Escrow explainerConsumer Financial Protection Bureau
- 12 CFR 1024.37Electronic Code of Federal Regulations
- Federal Register of November 21, 2022govinfo.gov
- Fannie Mae Selling Guide, B7-3-06Fannie Mae Selling Guide
- U.S. Fish and Wildlife Servicefws.gov
- $250,000 NFIP building maximumFEMA, National Flood Insurance Program
- FloodSmart premium pageFEMA, National Flood Insurance Program
- FloodSmart article for agentsFEMA, National Flood Insurance Program
- Cost of flooding pageFEMA, National Flood Insurance Program
- MCL 565.957Michigan Legislature
- MCL 565.954Michigan Legislature
- FloodSmart eligibility pageFEMA, National Flood Insurance Program
- DR-4607 disaster pageFederal Emergency Management Agency
- FIS-PUB 0215State of Michigan
- LOMA pageFederal Emergency Management Agency
- Appendix A to 12 CFR Part 22law.cornell.edu
- National Flood Insurance Program Summary of CoverageFEMA, National Flood Insurance Program
- “What Does Flood Insurance Cover in a Basement?”FEMA, National Flood Insurance Program
- FDIC FIL-8-2019Federal Deposit Insurance Corporation
- OCC Bulletin 2019-8occ.gov
Related resources
20-minute read
How to evaluate home insurance options: Coverage, limits and quotes
Learn how to evaluate home insurance options by comparing dwelling limits, deductibles, exclusions and discounts so your coverage truly rebuilds your home.
20-minute read
Homeowners insurance deductibles: How they work and how to choose one
Learn how homeowners insurance deductibles work, why percentage deductibles can cost thousands more, and how to pick an amount that fits your savings.
20-minute read
Home insurance and renovations: What to tell your insurer
Learn how renovations change your home insurance, which upgrades raise or lower premiums, and why calling your insurer before demolition protects you.
