What is a mansion? Size, features and what qualifies a house
A mansion is a very large, luxury single-family home that generally starts at 5,000 square feet, more than double the 2,142-square-foot median new single-family home in the U.S. Many luxury brokerages now use 8,000 square feet instead, because houses in general have grown.
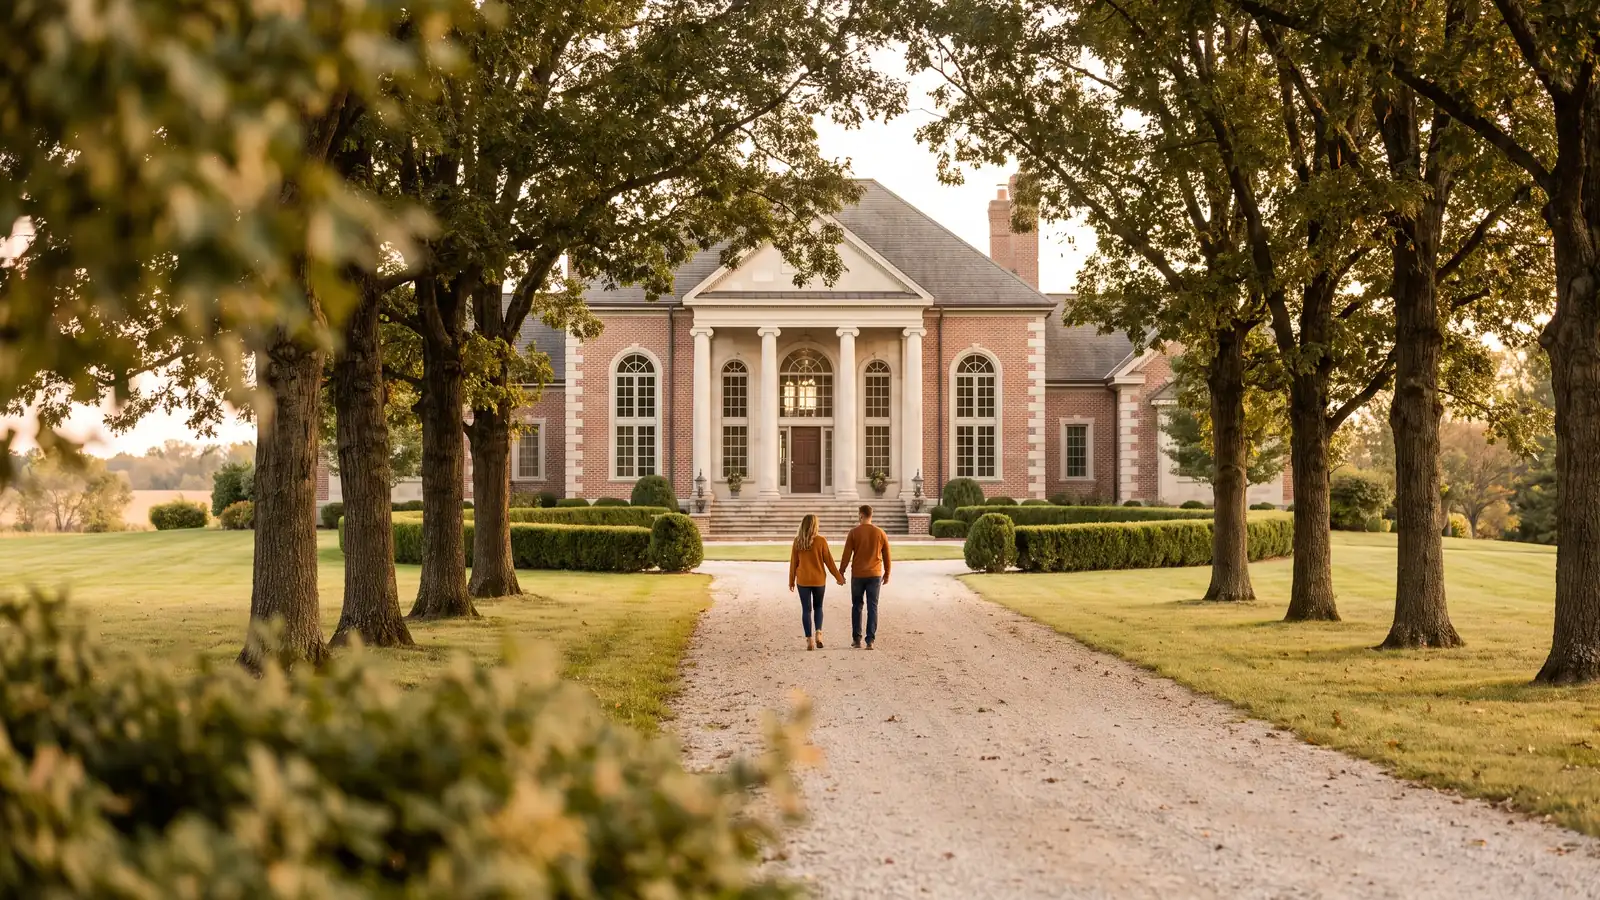
Square footage alone doesn’t settle it. A mansion also carries grand architectural detailing, 5 or more bedrooms, premium materials, and specialized rooms like a home theater or wine cellar. Location matters too: mansions sit on large grounds and price near the top of their local market.
Learn what counts as a mansion, including the size thresholds, the features that separate one from a merely big house, and what financing it takes. Our Homeownership guide covers what comes after the purchase.
Key takeaways:
- Size threshold: A mansion generally starts at 5,000 square feet, and many U.S. luxury brokerages now treat 8,000 square feet as the modern line.
- Features weigh as much as square feet: Expect 5 or more bedrooms, custom architectural detailing, premium finish materials, and at least 1 or 2 specialized rooms such as a theater or wine cellar.
- Location sets the final line: A home priced in the top 3% of its local market often gets called a mansion even when it falls under the size benchmark.
What counts as a mansion?
A mansion is a house of roughly 5,000 square feet or more that pairs that scale with luxury materials, distinctive architecture, and rooms an ordinary house doesn’t have. Cited ranges run from 5,000 to about 20,000 square feet, and several luxury brokerages have moved their floor to 8,000.1
There is no legal, code, or appraisal definition of the word. Every threshold you’ll read is a market convention, which is why how architects and designers define a mansion often reads differently from how a listing agent uses the term.
The number keeps drifting upward because the baseline moved. The median new single-family home completed in the U.S. measured 2,142 square feet in the most recent Census Bureau reporting, after decades of growth that NAR research on home size and buyer preferences tracks from the buyer’s side. A 5,000-square-foot house was extraordinary in 1960; today it’s about 2.3 times the median new build.
Where the word “mansion” comes from
“Mansion” traces to the Latin mansio, a dwelling or stopping place, by way of the Old French maison. In medieval England it attached to the principal residence of a manor, the lord’s house, distinct from the tenant cottages around it. The word travels badly: in Japan, manshon means a mid-rise apartment building.
What features define a mansion?
Six characteristics do most of the work, and a house usually needs several at once. Here’s the mansion standard against what a large, well-built suburban home offers.
| Feature | Typical mansion standard | Typical large home |
|---|---|---|
| Total living space | 5,000 to 20,000+ square feet | 3,000 to 4,500 square feet |
| Bedrooms and baths | 5 or more bedrooms, often multiple primary suites and en suite baths throughout | 4 to 5 bedrooms, 1 primary suite |
| Architecture | A named style with custom detail, Georgian, Victorian, French Château, bespoke contemporary, and millwork drawn for the house | A builder elevation from a standard plan set |
| Materials | Marble, exotic hardwoods, cut stone, custom cabinetry | Engineered flooring, quartz counters, stock trim |
| Specialized rooms | Home theater, wine cellar, library, gym, spa bath, guest or staff quarters | Finished basement, bonus room, home office |
| Grounds | Large landscaped lot with a pool, sport court, formal gardens or guest house | Fenced yard, patio, sometimes a pool |
Layout separates the two categories as much as the raw numbers. Mansions are organized into wings, with a grand foyer, more than one staircase, and circulation that keeps service out of the entertaining spaces, our guide to the different types of houses by structure and style covers the architectural families these homes draw from. The opposite pole uses the same design thinking: in small space living, every square foot has to earn its place.
How rare is a house of 4,000 square feet or more?
Rare enough that the Census Bureau’s top size bracket stops at 4,000 square feet. According to the Census Bureau’s Survey of Construction table of floor area in new single-family houses, 70,000 of the 1,005,000 single-family homes completed in the U.S. in 2025 had 4,000 square feet or more, about 7%. Every 5,000-square-foot house finished that year sits inside that 7%, so the share at mansion scale is smaller still.
The Midwest, the Census region that includes Michigan, builds smaller. Of the 131,000 single-family homes completed there in 2025, 6,000 had 4,000 square feet or more, about 5%, and the regional median was 1,969 square feet against 2,142 nationally, per the same Census floor area table.
| Year completed | Median size of a new U.S. single-family home |
|---|---|
| 1973 | 1,525 square feet |
| 2000 | 2,057 square feet |
| 2015 | 2,467 square feet |
| 2025 | 2,142 square feet |
Source: U.S. Census Bureau, Survey of Construction, square feet of floor area in new single-family houses completed (annual table, file updated May 14, 2026).
Homes sold tell the same story at a slightly larger size. The Census Bureau’s Highlights of 2025 Characteristics of New Housing reports a median of 2,194 square feet for new single-family homes sold in 2025, at a median price of $417,400 and an average price of $523,800. An average that far above the median is a sign that a smaller number of high-priced homes pull it up.
What do builders put in homes of 5,000 square feet or more?
The two-story foyer is the clearest measured example. In an October 2026 analysis of Census Survey of Construction data, the National Association of Home Builders reported that 65.5% of new homes with 5,000 square feet or more had a two-story foyer in 2025, the highest level since 2017. The share was 40.4% for homes of 3,000 to 4,999 square feet and between 9.9% and 24.5% for homes under 3,000 square feet.
NAHB defines a two-story foyer as the entranceway inside the front door with a ceiling at the level of the second-floor ceiling. Across all new homes, the share with one rose from 24.6% to 25.6% in 2025, per the same NAHB analysis, so at 5,000 square feet and up the feature is more than twice as common as in new homes overall.
Grand entries are not what every buyer wants. The same post cites NAHB’s What Home Buyers Really Want survey, in which 32% of buyers said they would likely reject a home with a two-story entry foyer (NAHB, October 5, 2026). A feature that marks a house as a mansion can also narrow the pool of buyers who want it; our guide to what a buyer’s market looks like explains how a thin pool plays out.
Mansion vs. estate: what’s the difference?
A mansion describes the house; an estate describes the house plus the land and outbuildings around it. Listings use the words interchangeably, but the distinction shows up in the tax bill, the insurance, and the upkeep.
| Feature | Mansion | Estate |
|---|---|---|
| What the word describes | The structure itself | The property as a whole, house, land, outbuildings |
| Land | Can sit on a half-acre suburban lot | Typically several to dozens of acres |
| Secondary structures | Not required | Common, guest house, carriage house, stables, caretaker’s cottage |
| Working use | Purely residential | May include farmland, vineyards, orchards or equestrian facilities |
| Upkeep | Interior systems and a landscaped lot | All of that plus acreage, private roads, wells, and secondary buildings |
Most estates contain a mansion, but a mansion on a suburban lot is not an estate. If a listing says estate, look for the acreage before you accept the label.
How location changes what counts as a mansion
Some brokerages skip square footage and use a market-relative rule instead: a home priced in the top 3% of its local market gets treated as a mansion regardless of size. That rule catches what the size threshold gets wrong.
In a neighborhood of 1,500-square-foot ranches, a 4,500-square-foot house with a circular drive is unmistakably the mansion on the street. In an affluent suburb where 5,000 square feet is the going rate, the same house is simply a large house. Buyers at this level also pay for privacy, lot size, and a quiet address.
How to tell whether a house is really a mansion
Five checks settle it faster than the listing copy will. Run them in this order, because the first one eliminates most candidates.
- Verify the square footage: Pull the number from public records or the appraisal, not the marketing sheet, and confirm whether finished basement space is counted. Under 5,000 square feet above grade is a large home, not a mansion.
- Look at how the space is organized: Wings, a foyer with a ceiling above 15 feet, more than one staircase, and separated service circulation are structural signals. Square footage delivered as oversized bedrooms is not.
- Count the specialized rooms: A theater, wine cellar, library, gym, or staff quarters each signal a house built for more than daily living. One is a nice extra; 3 or more is a pattern.
- Read the finish schedule, not the adjectives: Ask what the counters, floors, millwork, and windows actually are. “Luxury” in a listing is free; book-matched marble is not.
- Compare the price to the block, not the metro: If the house sits in the top few percent of its immediate neighborhood, the market already treats it as a trophy property. Which is how it will price when you sell.
One honest caution: homes at the top of a local market generally take longer to sell and draw fewer qualified buyers than mid-market houses. The pros and cons of investing in luxury housing markets lays out both sides, and our Home Types & Living guide puts mansions in context against every other housing format.
How buyers finance a mansion
Most mansion price points clear the 2026 baseline conforming loan limit of $832,750, which puts the financing into jumbo territory.2 The limit is set annually by the Federal Housing Finance Agency and rises in designated high-cost counties, check the current conforming loan limits from FHFA for the county you’re buying in.
Jumbo loans are non-conforming, meaning they fall outside Fannie Mae and Freddie Mac guidelines, so each lender writes its own rules. Which is why the same borrower gets materially different answers on the same file. Lenders in Align’s network commonly look for:
- Stronger credit: Minimum scores generally start around 700 to 720, with the best pricing reserved for higher tiers.
- Larger reserves: Many jumbo programs ask for 6 to 12 months of mortgage payments in liquid assets after closing.
- A bigger down payment: Requirements are usually larger than on a conforming loan and climb with the loan amount; Samantha can tell you what her lenders are asking for on your file.
- Deeper documentation: Expect extra review when a meaningful share of your income is variable, self-employed, or investment-based.
Appraisal is the step that surprises people. Unique high-end homes have few genuine comparable sales, so an appraiser may reach across a wider geography and time window, which lengthens the timeline and adds valuation risk. Our walkthrough of the home appraisal process covers what happens if the number comes in low, and our jumbo loan tips cover preparing the file first. Because Align is a broker, we can place a jumbo file with whichever wholesale lender treats your scenario best. Reserves, income documentation, or property type is usually where the spread shows up.
Why does the conforming limit decide how a mansion is financed?
Because federal law caps what Fannie Mae and Freddie Mac can buy. The Federal Housing Finance Agency’s conforming loan limit page explains that the two companies are restricted by law to purchasing single-family mortgages below a set amount, the conforming loan limit, and that loans above it are known as jumbo loans. The same page traces the national limit for one-unit homes from $33,000 in the early 1970s to $417,000 for 2006 through 2008.
In its November 25, 2025 announcement, FHFA set the 2026 baseline at $832,750 and the ceiling for one-unit homes in high-cost areas at $1,249,125, which is 150 percent of the baseline. An area gets a limit above the baseline when 115 percent of its local median home value exceeds the baseline. Our loan limits lookup shows the figure for each county in the states Align serves.
The Consumer Financial Protection Bureau states the trade-off in its answer to what a jumbo loan is: mortgages are allowed to exceed these limits, larger loans are called jumbo mortgages, and the cost of obtaining a jumbo mortgage may be higher than the cost of a conforming one. Cornell Law School’s Legal Information Institute defines a jumbo loan the same way, as a mortgage loan that exceeds the limit set by FHFA. Our overview of jumbo and non-QM loans covers how lenders build those programs.
How many comparable sales does an appraiser need for a one-of-a-kind house?
On a conforming loan, at least three. Fannie Mae’s Selling Guide section B4-1.3-08, Comparable Sales says a minimum of three closed comparables must be reported in the sales comparison approach, and that comparable sales closed within the last 12 months should be used, although the most appropriate comparables may not always be the most recent.
The same section allows older sales where recent ones do not exist: in a rural area with minimal sales activity, the appraiser may use older comparable sales if the report explains why. Jumbo loans sit outside Fannie Mae’s guide, so each jumbo lender sets its own appraisal requirements; ask which rules apply before the appraisal is ordered.
Square footage is measured to a standard too. Fannie Mae’s Improvements section guidance requires appraisers to follow ANSI Z765-2021 when they measure and report above- and below-grade square footage, which is why the appraisal figure can differ from a listing sheet. If the value comes in under the contract price, our guides to appealing a low appraisal and the drive-by appraisal explain your options and what an exterior-only valuation can and cannot see.
What Michigan buyers should know
Michigan’s mansion-scale housing concentrates in a few communities, Bloomfield Hills and Grosse Pointe in metro Detroit, Ada and East Grand Rapids on the west side, Harbor Springs and Petoskey up north. Four Michigan specifics change the math on a high-priced purchase.
- Every Michigan county sits at the baseline loan limit: All 83 counties use the 2026 baseline conforming limit of $832,750, and none carries a high-cost designation. Above that figure you’re in jumbo territory anywhere in the state.
- Your tax bill resets the year after you buy: Under Proposal A, annual growth in taxable value is capped at the lesser of 5% or inflation, but a transfer of ownership uncaps it, and taxable value resets to the state equalized value the year after the sale, which is half of the assessor’s estimate of market value, not automatically half of what you paid. On a house the seller has held for 20 years, your first full-year bill can be dramatically higher than theirs. Budget from the uncapped number.
- Transfer tax is real money here: Michigan charges $8.60 per $1,000 of sale price, $7.50 state plus $1.10 county, and the seller pays it by default. On a $2 million sale that’s $17,200, which becomes a negotiating item.
- File the principal residence exemption: A principal residence exemption removes up to 18 mills of local school operating tax from your primary home. Second homes and northern Michigan cottages don’t qualify.
Millage rates and assessment practices vary by township, so confirm the uncapped figure with the local assessor and a tax professional before you write an offer.
How should you insure a mansion in Michigan?
Insure it for what it would cost to rebuild, not what it sold for. The Michigan Department of Insurance and Financial Services’ homeowners insurance guide for Michigan consumers defines replacement cost as the cost to replace, repair or rebuild your home to its original condition with materials of the same kind and quality. Ask the insurer how it priced the marble, cut stone and custom millwork in the features table above.
The same DIFS guide describes guaranteed replacement cost coverage, an additional coverage under which the company protects you for the full replacement cost of the house even if that amount is higher than the policy limit. It also notes that a regular homeowners policy does not cover flood damage to the home and contents, so a lakefront property needs that question answered separately; our guide to buying waterfront property covers the steps.
DIFS has also warned that coverage can fall behind building costs. In a June 28, 2022 release, the department said rising home values and building supply prices mean the coverage a homeowners policy provides may not be enough to replace or rebuild a home if it is damaged or destroyed. Our guides to evaluating home insurance options and homeowners insurance deductibles walk through the policy choices.
Which Michigan mansions are National Historic Landmarks?
Several of Michigan’s historic mansions carry the federal National Historic Landmark designation. The National Park Service’s list of National Historic Landmarks by state includes these four:
| Landmark | Location | Designated |
|---|---|---|
| Fair Lane (Henry Ford Estate) | Dearborn, Wayne County | November 13, 1966 |
| Cranbrook | Bloomfield Hills, Oakland County | June 29, 1989 |
| Meadow Brook Hall | Rochester, Oakland County | March 2, 2012 |
| Gaukler Pointe (Edsel and Eleanor Ford House) | Macomb County | October 31, 2016 |
Source: National Park Service, National Historic Landmarks by State.
Meadow Brook Hall shows the far end of the size range. The house’s own guide to Meadow Brook Hall lists 110 rooms, 25 bedrooms, 23 bathrooms, 24 fireplaces and 2 elevators across 88,000 square feet, built from 1926 to 1929 at a cost of $4 million. Oakland University’s 2012 announcement of the landmark designation gave the size as 80,000 square feet. Published figures differ, but either one is more than 35 times the 2,142-square-foot median new home of 2025.
Ford House is the estate example. Ford House describes itself as the lakeside estate of Eleanor and Edsel Ford in Grosse Pointe Shores on Lake St. Clair, built in 1928, with 87 acres that include the main residence, historic outbuildings and gardens. The residence is the mansion; the acreage, outbuildings and gardens make it an estate. An older house at this scale deserves a full inspection; our home inspection checklist for buyers lists what to look at.
What do home values look like in Michigan’s high-end communities?
Census figures put numbers on the communities named above. Census Reporter, a Knight Foundation project that publishes U.S. Census Bureau American Community Survey data, reports these median values of owner-occupied homes in the 2024 ACS 5-year estimates:
| Community | Median home value | Comparison area |
|---|---|---|
| Bloomfield Hills | $947,900 | Michigan: $231,600 |
| Village of Grosse Pointe Shores | $733,500 | |
| Ada Township, Kent County | $544,700 | Kent County: $289,900 |
| East Grand Rapids | $521,300 | |
| Harbor Springs | $415,700 | Petoskey micro area: $315,700 |
Source: Census Reporter profiles, ACS 2024 5-year: Bloomfield Hills, Grosse Pointe Shores, Ada Township, East Grand Rapids, Harbor Springs.
Even in these places the median is a typical home, not a mansion. Bloomfield Hills is the only one of the five with a median value above the 2026 baseline conforming limit of $832,750 that FHFA set for every Michigan county, so whether a purchase there needs a jumbo loan depends on the loan amount for the specific house, not the community. These are survey estimates: Census Reporter shows a margin of plus or minus $98,767 on the Bloomfield Hills figure.
What do Michigan’s tax statutes say about buying a high-value home?
MCL 207.525 levies the state transfer tax at $3.75 for each $500 or fraction of $500 of the total value transferred, and MCL 207.504 sets the county tax at 55 cents per $500 in a county with a population under 2,000,000. Michigan Treasury’s State Real Estate Transfer Tax page puts the state tax on the seller and collects it through the county when the deed is recorded. A purchase agreement can still move part or all of that cost to the buyer. At this price the tax is large (the example below shows how large), so check who pays in the agreement before you count your cash to close.
“Or fraction of $500” means the tax rounds up. Hypothetical example, not an offer: on a $1,250,250 sale, the value covers 2,500 full steps of $500 plus a $250 fraction, so the tax is figured on 2,501 steps. At the rates in the state statute and the county statute, that is $9,378.75 state tax plus $1,375.55 county tax, $10,754.30 in all. Our Michigan transfer tax calculator runs the same math for any price, and our guide to closing costs covers the other charges at the closing table.
On property tax, MCL 211.27a says that after a transfer of ownership, the property’s taxable value for the following year is its state equalized valuation for that year. Michigan Treasury’s page on changes in ownership and uncapping ties the rule to Proposal A of 1994. Our Michigan property tax calculator turns that into a planning number, and our guide to how property tax assessments work explains the steps behind the bill. As Samantha Shelton tells buyers, “Don’t build your budget around somebody else’s tax bill.”
For the principal residence exemption, MCL 211.7cc sets the filing deadlines: on or before June 1 for the summer tax levy that follows, or on or before November 1 for the winter levy. Treasury’s principal residence exemption page quotes the definition in MCL 211.7dd(c): the one place where an owner has a true, fixed, and permanent home to which, whenever absent, the owner intends to return.
How Align matches the loan to the property
Lenders do not treat every property the same. Condos, including non-warrantable ones, and homes with two to four units each come with rules that vary from one lender to the next.
Because Align is a broker, Samantha can take your file to the wholesale lender whose guidelines fit the property, instead of forcing it into one bank's box. One application, multiple lenders, and one person on your file from start to finish.
FAQ: What makes a house a mansion
Here are answers to common questions about what qualifies a house as a mansion.
What is the minimum square footage for a mansion?
There is no legal minimum. The most commonly cited floor is 5,000 square feet, and many U.S. luxury brokerages now use 8,000 square feet because average new-home size has grown. Local context shifts the line: in a market of 1,500-square-foot homes, a 4,500-square-foot house reads as a mansion, while the same house in an affluent suburb may simply be a large home. An agent who works that specific market knows where the line sits.
What is the difference between a mansion and an estate?
A mansion describes the house itself, while an estate describes the house plus substantial surrounding land and often secondary structures. An estate might include a guest house, stables, a caretaker’s cottage, gardens, or acreage measured in dozens of acres. Many estates contain a mansion, but a mansion on a half-acre suburban lot is not an estate. Older American estates often began as working farms, a background covered in our guide to buying a historic home.
Is a luxury home the same thing as a mansion?
No. A luxury home is defined by price, finish level, and location, and it can be a 2,500-square-foot condominium or a waterfront cottage. A mansion is defined primarily by scale, then by grandeur. All mansions are luxury homes, but plenty of luxury homes are far too small to qualify as mansions. A distinction that matters most in dense urban markets, where our comparison of condos and co-ops covers the high-end attached formats.
Do you need a jumbo loan to buy a mansion?
Usually yes. Most mansion price points exceed the conforming loan limit set each year by the Federal Housing Finance Agency, which puts the financing into jumbo territory. Jumbo loans typically ask for stronger credit, larger reserves, and a bigger down payment than conforming loans, and terms vary widely between lenders, so it pays to compare options. Our guide to how to qualify for a jumbo loan walks through the documentation.
What is the average size of a new house in 2026?
About 2,185 square feet at the median and 2,426 square feet on average for new single-family homes in the second quarter of 2026, according to an August 2026 NAHB analysis of Census quarterly data. NAHB says new-home size had been falling since 2015 as affordability worsened, but has trended higher since 2024 because the upper end of the market has fared better than the entry level.
How many homes in the U.S. have five or more bedrooms?
About 6.16 million of the 123.53 million U.S. housing units, or 4.99%, had five or more bedrooms in the 2020 Residential Energy Consumption Survey from the U.S. Energy Information Administration (data released March 2023). Those homes held 9.64% of all residential square footage, nearly double their share of homes, which shows how much larger five-bedroom houses run than the rest.
Does a finished basement count toward a mansion’s square footage?
Not in the above-grade figure an appraiser reports. Fannie Mae’s Selling Guide section B4-1.3-05 treats a level as below-grade if any portion of it is below grade, regardless of finish or window area, so even a finished walk-out lower level is left out of above-grade square footage and room count. The appraiser reports that space separately and adjusts for it, because finished lower levels can still add substantially to value.
Is mortgage interest on a mansion fully tax deductible?
Not above the federal cap. IRS Publication 936 (2025) says you can deduct home mortgage interest on the first $750,000 of home acquisition debt, or $375,000 if married filing separately. Debt incurred before December 16, 2017 keeps the older $1 million limit ($500,000 married filing separately). The limits apply to the combined mortgages on your main home and second home, so confirm your own figures with a tax professional.
The bottom line on what makes a house a mansion
A mansion is a very large luxury home that generally starts at 5,000 square feet, more than double the 2,142-square-foot median new single-family home, with many luxury brokerages now using 8,000 square feet as the modern threshold. No code or agency defines the word. Size gets a house into the conversation; 5 or more bedrooms, custom architecture, premium materials, specialized rooms, and large grounds finish the case. A home in the top 3% of its local market often earns the label even below the size benchmark, and buying one almost always means financing above the 2026 conforming limit of $832,750.
If you’re ready to buy at that price point, talk to Align Lending. We’ll shop your scenario across our wholesale lender network and show you the jumbo and high-balance options side by side. Call 248-506-5727 or start online.
Footnotes:
1. The 5,000- and 8,000-square-foot figures are market conventions used by real estate and architecture publications, not legal, code, or appraisal definitions. No building code, tax authority, or licensing body classifies a house as a mansion, and ranges vary by source and region. Return to text.
2. Align Lending is an independent mortgage broker and does not set loan terms. The conforming loan limit is published annually by the Federal Housing Finance Agency and can change each year. Jumbo credit score minimums, reserve, down payment, and documentation standards are set by the individual wholesale lenders in Align’s network and are subject to change, credit approval, and property eligibility. Nothing here is an offer of credit or a commitment to lend. Return to text.
Sources: 5,000 to 20,000 square foot range, Architecture Lab; 8,000-square-foot modern benchmark, Forbes Global Properties; top-3%-of-local-market rule, eXp Realty; median size of new single-family homes completed, U.S. Census Bureau, Characteristics of New Housing; 2026 conforming loan limits, Federal Housing Finance Agency; Proposal A uncapping, principal residence exemption, and transfer tax rates, Michigan Department of Treasury.
This article is for informational purposes only and is not intended to provide legal, financial, tax, or appraisal advice. Property tax treatment, loan limits, and lender guidelines change and vary by location, confirm current details with your local assessor, a qualified tax professional, and a licensed loan originator. Align Lending is an independent Michigan mortgage broker, NMLS #2041154.
Sources
Every outside source this guide links to, in the order it appears. How we choose and check sources
- How architects and designers define a mansionarchitecturaldigest.com
- Census Bureau reportingU.S. Census Bureau
- NAR research on home size and buyer preferencesNational Association of Realtors
- Survey of Construction table of floor area in new single-family housesU.S. Census Bureau
- National Association of Home Builders reportedeyeonhousing.org
- Current conforming loan limits from FHFAFederal Housing Finance Agency
- November 25, 2025 announcementFederal Housing Finance Agency
- Answer to what a jumbo loan isConsumer Financial Protection Bureau
- Defines a jumbo loanlaw.cornell.edu
- B4-1.3-08, Comparable SalesFannie Mae Selling Guide
- Improvements section guidanceFannie Mae Selling Guide
- Under Proposal AState of Michigan
- Homeowners insurance guide for Michigan consumersState of Michigan
- June 28, 2022 releaseState of Michigan
- List of National Historic Landmarks by statenps.gov
- Guide to Meadow Brook Hallmeadowbrookhall.org
- Announcement of the landmark designationucmapps.oakland.edu
- Ford Housefordhouse.org
- Bloomfield Hillscensusreporter.org
- Grosse Pointe Shorescensusreporter.org
- Ada Townshipcensusreporter.org
- East Grand Rapidscensusreporter.org
- Harbor Springscensusreporter.org
- MCL 207.525Michigan Legislature
- MCL 207.504Michigan Legislature
- State Real Estate Transfer Tax pageState of Michigan
- MCL 211.27aMichigan Legislature
- MCL 211.7ccMichigan Legislature
- Principal residence exemption pageState of Michigan
- An August 2026 NAHB analysiseyeonhousing.org
- 2020 Residential Energy Consumption Surveyeia.gov
- IRS Publication 936 (2025)Internal Revenue Service
Related resources
20-minute read
Condo vs. Co-op: Similarities and Differences Every Urban Buyer Should Know
Compare condo vs. co-op ownership, monthly fees and board approval rules so you can choose the urban home type that fits your budget and lifestyle.
20-minute read
The pros and cons of buying a condo: Is it right for you?
Compare the pros and cons of buying a condo, from lower prices and low-maintenance living to HOA fees and rules, so you can decide if condo life fits you.
20-minute read
Benefits of modular homes: Cost savings, faster builds and sustainability
See how modular homes are built and financed, what the advertised 10% to 20% savings leave out, and what McKinsey found about build times.