
Economic impacts of housing shortages on prices, affordability and buyers
A housing shortage means fewer homes exist than the number of households that want to buy or rent one, and the economic effect is that competition, not new construction, closes the gap in the short run. That competition is why the median price of an existing home reached a record $440,600 in June 2026, and why 22.6 million renter households now spend more than 30% of their income on housing.
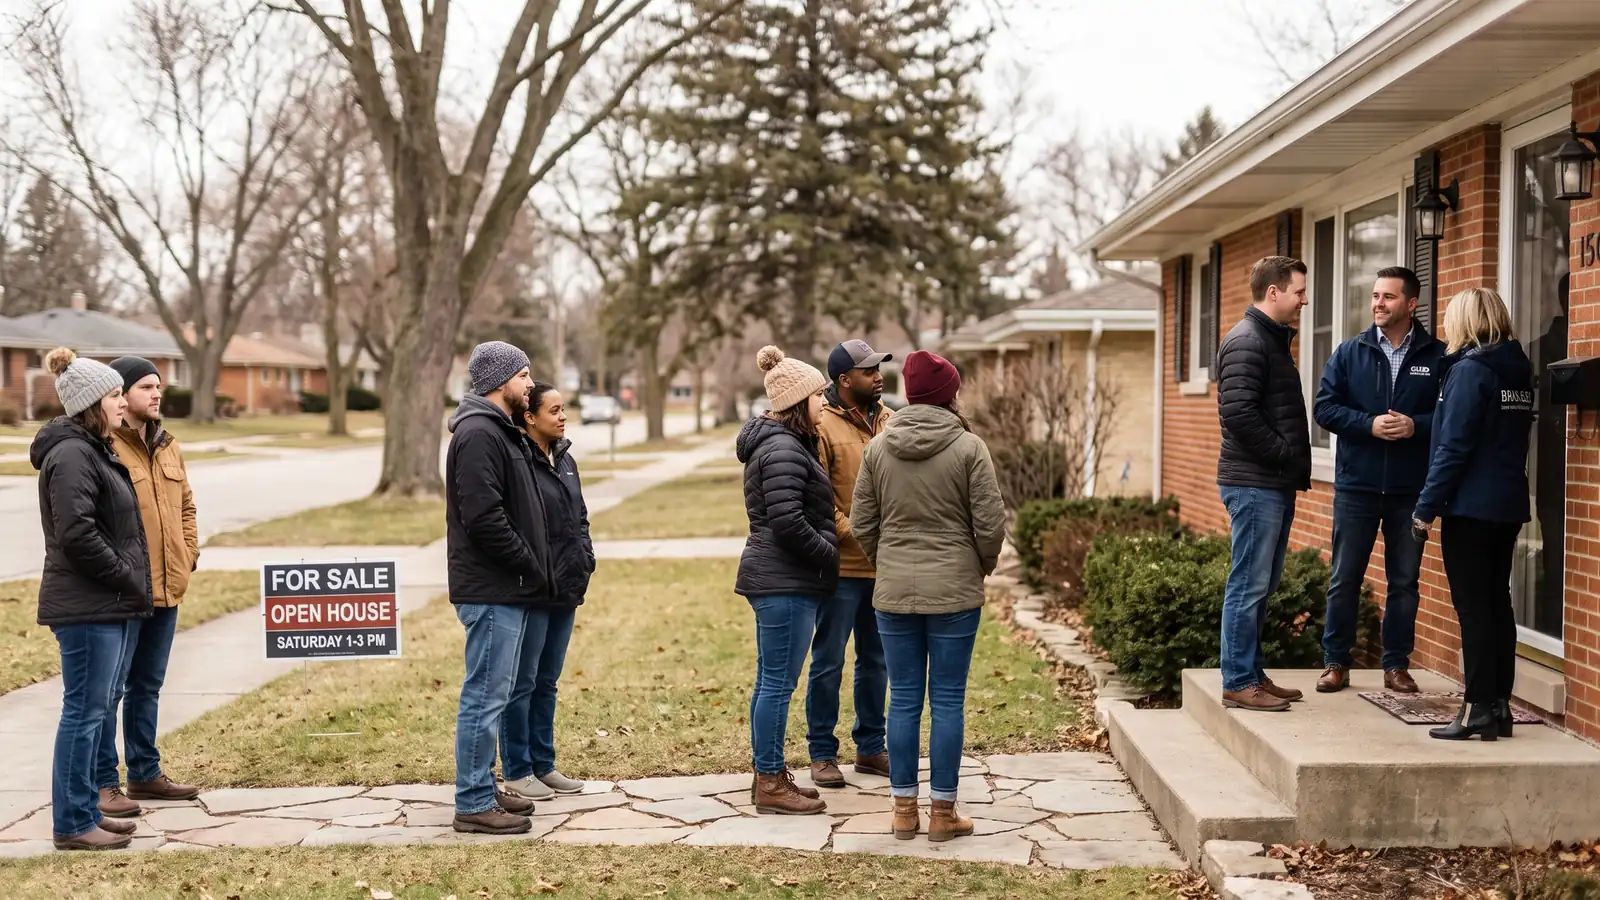
Supply is constrained on several fronts at once. A shortage of skilled construction labor alone costs an estimated $10.8 billion in annual economic output and left roughly 19,000 single-family homes unbuilt in 2024, on top of zoning limits, slow permitting, high land and materials costs, and homeowners who won’t give up a low mortgage rate to sell.
For buyers, the practical effect is fewer affordable listings, longer searches and more competition on the homes that do come up for sale. Learn what causes housing shortages, how they affect prices and affordability, and what buyers can do to compete in a tight market.
Key takeaways:
- Shortages resolve through price, not supply: With the national housing supply gap near 4.03 million homes in 2025, competition bids prices up and rents higher instead of producing more inventory in the short run.
- Construction labor is a major bottleneck: Skilled-trade shortages cost an estimated $10.8 billion in annual economic output and delayed home building by nearly two months on average in 2024.
- Cost burden is the measurable human impact: 22.6 million renter households spend more than 30% of income on housing, and 12.1 million of them exceed the 50% severe-burden line.
Which constraints combine to create a housing shortage?
A housing shortage forms when several supply-side constraints stack at once, rather than from any single cause: zoning and permitting limits, a shortage of skilled labor, high land and materials costs, and a mortgage rate lock-in effect that keeps existing owners from listing.
| Constraint | How it limits supply | Rough time to unwind |
|---|---|---|
| Zoning and land-use rules | Restrict where and how densely homes can be built, often pushing builders toward larger, higher-priced lots instead of starter homes. | Years. Rezoning and comprehensive-plan updates typically span multiple local budget cycles. |
| Permitting and approval timelines | Add months of review before a shovel breaks ground, and every added month is carrying cost a builder prices into the home. | Months to more than a year, depending on the municipality. |
| Skilled labor shortage | Fewer framers, electricians and plumbers means slower build schedules and higher wages, both of which land in the final price. | Years. Training a new construction workforce doesn’t happen in a single building cycle. |
| Land and materials costs | High input costs push builders toward higher-margin, higher-priced homes instead of the entry-level product buyers need most. | Tied to broader commodity and land markets, with no fixed timeline. |
| Mortgage rate lock-in effect | Owners holding a low fixed rate avoid selling and losing it, which shrinks resale inventory independent of new construction. | Eases gradually as rates fall or life events force a move. |
The mortgage rate lock-in effect deserves its own explanation, because it’s the newest constraint and, in dollar terms, one of the largest. Homeowners who bought or refinanced when rates were low have little incentive to sell and trade that payment for a new one at today’s rate. Federal Housing Finance Agency research found that for every percentage point market rates exceed a borrower’s original rate, the probability that borrower lists a home for sale drops by 18.1%, and the effect is estimated to have kept 1.33 million home sales from happening between the second quarter of 2022 and the fourth quarter of 2023.
Picture a homeowner carrying a $280,000 mortgage balance at a fixed rate several points below today’s typical new loan.1 Trading it for a similarly priced home means a meaningfully higher payment before even counting a larger loan amount, exactly the math keeping many would-be sellers out of the market.
How many homes is the U.S. short, and why do the estimates differ?
The national gap figure earlier in this guide is one estimate among several, and the published numbers differ because each researcher defines a healthy market differently. The Congressional Research Service lined up the major estimates in a December 15, 2025 Insight on housing shortage estimates: Freddie Mac put the shortage at 3.7 million units as of the third quarter of 2024, Zillow at 4.7 million for 2023, and Brookings at 4.9 million for the fourth quarter of 2023. CRS also noted that Up for Growth’s 2025 report would show a shortfall of 3.78 million units.
| Estimate by | Shortage | Period measured |
|---|---|---|
| Freddie Mac | 3.7 million units | Third quarter of 2024 |
| Zillow | 4.7 million units | 2023 |
| Brookings | 4.9 million units | Fourth quarter of 2023 |
| Up for Growth (2025 report) | 3.78 million units | As announced to CRS |
Source: Congressional Research Service, Estimates of a “Housing Shortage” (IN12628), December 15, 2025.
Building more has narrowed the gap only slowly. Freddie Mac reported in its November 26, 2024 housing supply update that the shortage declined slightly, from 3.8 million units at the end of 2020 to 3.7 million in the third quarter of 2024, even though the housing stock grew by 5.8 million units over that stretch, an average of 2.1 million a year. Up for Growth reported in October 2024 that underproduction reached 3.85 million homes in 2022 and fell by 50,000 homes, its first decrease in more than a decade. Local land-use rules are a large part of why the gap persists; our guide to zoning regulations explains how they work.
How do housing shortages affect home prices?
Housing shortages put a floor under home prices: when buyers outnumber available homes, competition bids prices up and keeps them elevated even when sales volume falls. The median price of an existing home reached a record $440,600 in June 2026, up 1.8% from $432,700 a year earlier, the 36th consecutive month of year-over-year increases, according to the National Association of Realtors.
That persistence is the real story. NAR’s Housing Shortage Tracker, which compares new building permits to job growth across major metro areas, shows some markets narrowing their supply deficit while others fall further behind, which is why housing market trends now read differently from city to city even as the national price line keeps climbing. See the latest NAR research on home prices and inventory for how your market compares.
The pattern shows up in housing affordability indices too: prices have kept setting records through a period of historically weak transaction activity, because price relief usually requires more homes on the market, not just softer demand.
How do today’s mortgage rates and inflation interact with the shortage?
Rates shape both sides of a shortage: they decide how many buyers can qualify and how many owners are willing to sell. Freddie Mac’s Primary Mortgage Market Survey reported that the 30-year fixed-rate average was 7.32% as of October 22, 2026, compared with 6.19% a year earlier. That is a national average for borrowers with good to excellent credit buying a single-family home, and it excludes points and fees, so one buyer’s quote can differ.
The Federal Reserve raised its target range for the federal funds rate by a quarter point to 3-3/4 to 4 percent on September 16, 2026, saying in its FOMC statement that inflation remains elevated. A wider gap between market rates and existing loans deepens the lock-in effect: the FHFA working paper on lock-in notes that nearly all 50 million active U.S. mortgages have fixed rates, most of them far below prevailing market rates. Our guides to how the Federal Reserve affects mortgage rates and the impact of interest rates on home prices go deeper on that link.
Housing is also a large share of measured inflation. The Bureau of Labor Statistics’ September 2026 Consumer Price Index release reported that the all items index rose 3.7% over 12 months and the shelter index rose 3.2% over the year, with shelter up 0.4% in September alone. Our guide to the impact of inflation on home prices explains how those two forces feed each other.
When is a household considered cost burdened?
A household is cost burdened when it spends more than 30% of its gross income on housing, including rent or a mortgage payment plus utilities, and severely cost burdened once that share passes 50%, under the definition used by the U.S. Department of Housing and Urban Development.
The number that makes the shortage personal is 22.6 million: that’s how many renter households were cost burdened in 2023, a record high for the third consecutive year, according to Harvard University’s Joint Center for Housing Studies. Of those, 12.1 million were severely cost burdened, spending more than half their income just to keep a roof overhead, about 27% of all renter households. The burden concentrates hardest at the bottom of the income scale: 83% of renter households earning under $30,000 a year were cost burdened in 2023, compared with 45% of those earning $45,000 to $74,999, the same report found.
Our guide to affordability challenges in today’s housing market breaks down what pushes a household past that line and what tends to bring it back under.
Passing the 30% threshold matters in practice, because it’s roughly the point where housing costs start crowding out food, healthcare, transportation and savings for a typical household.
Who carries the cost burden as the shortage continues?
Newer data show the burden has not eased. The Congressional Research Service’s May 13, 2026 report on housing cost burdens in 2024 counted 22.7 million renter households (49.4%) and 20.7 million owner households (23.9%) as cost burdened, and 26.2% of renter households as severely cost burdened. The same report found that every year from 2006 to 2024, between 46.3% and 50.7% of all renters faced a housing cost burden, so the renter share has stayed near half for nearly two decades.
The National Low Income Housing Coalition summary of the 2026 State of the Nation’s Housing report from Harvard’s Joint Center for Housing Studies described the 22.7 million figure as a record and said the growth in cost-burdened renters appears driven by rising rents and a shrinking supply of low-cost rental units. The report’s June 17, 2026 release coverage added that residential mobility reached a record low and that market forces alone are unlikely to meet the need for deeply affordable homes. For a household weighing whether to keep renting, our renting vs. buying comparison and the guide to rental market trends walk through the math.
How do labor shortages limit new construction?
A shortage of skilled construction labor is one of the biggest and most measurable drags on new supply, costing an estimated $10.8 billion in annual economic output. A June 2025 study from the Home Builders Institute, conducted with the National Association of Home Builders and researchers at the University of Denver, found that scarce skilled labor added an average of 1.98 months, nearly two months, to construction timelines and kept roughly 19,000 single-family homes from being built in 2024 alone.
That splits into two costs builders pass along: about $2.7 billion in extra carrying costs on longer builds (interest, insurance and overhead), and $8.1 billion in homes that simply never got built because crews weren’t available, lost production that shows up later as a buyer who can’t find a home to bid on.
Underlying Census new residential construction and sales data shows the same story from the builder’s side: starts have consistently trailed the pace needed to keep up with household formation. Our guide to economic factors driving housing demand covers the other half of the equation, why demand keeps outpacing this constrained supply.
Nationally, the gap between households formed and homes built widened to an estimated 4.03 million homes in 2025, up from 3.8 million in 2024, according to Realtor.com research on housing inventory. Closing that gap takes years of sustained building at a pace the industry hasn’t hit in nearly two decades, not a single strong construction season.
What do the latest construction numbers show?
New construction slowed into the fall of 2026. According to the Census Bureau’s September 2026 new residential construction report, released October 20, 2026, privately owned housing starts ran at a seasonally adjusted annual rate of 1,221,000, which is 7.4% below September 2025. Building permits, the pipeline for future starts, ran at 1,400,000, 3.0% below the 1,444,000 rate a year earlier.
| Measure, September 2026 | Seasonally adjusted annual rate |
|---|---|
| Building permits | 1,400,000 |
| Housing starts, all types | 1,221,000 |
| Single-family starts | 859,000 |
| Housing completions | 1,192,000 |
Source: U.S. Census Bureau and HUD, Monthly New Residential Construction, September 2026 (October 20, 2026).
The shortage is uneven between new and existing homes. The Census Bureau’s September 2026 new residential sales report counted 476,000 new houses for sale at the end of September, an 8.4-month supply at the current sales pace, with a median sales price of $400,400. Existing homes were far tighter: the National Association of Realtors reported a 4.8-month supply of existing homes in September 2026 and a median existing-home price of $417,500, up 1.3% from a year earlier. That gap is one reason a buyer who keeps losing out on resale homes may find more choice in a builder’s inventory; our guide to new home construction covers how that purchase differs.
Builders in the Midwest are feeling the pull of higher rates. The Federal Reserve’s October 2026 Beige Book report for the Chicago district, which covers lower Michigan, said homebuilding slowed slightly as higher mortgage rates and economic uncertainty weighed on demand, and that builders were leaning on sales promotions to move homes already built rather than starting more. Labor data from the Bureau of Labor Statistics construction industry page show 8,364,000 construction employees in September 2026 and average hourly earnings of $41.69, both preliminary, while construction job openings fell from 306,000 in June to 234,000 in August 2026. Buyers who decide to build can read how construction-to-permanent loans fund a home while it goes up.
What can buyers do to compete when supply is limited?
Buyers compete most effectively by removing friction the seller can see, since a tight market rewards the offer that looks most certain to close. Four moves make the biggest difference.
- Get a fully underwritten preapproval, not just a prequalification. A prequalification is a quick estimate; an underwritten preapproval means a lender has already verified your income, assets and credit, so your offer carries the weight of a buyer who’s cleared the hard part already.
- Widen your search radius. Inventory tends to be tightest in the most-searched submarkets. Adjacent neighborhoods and nearby towns often carry more listings and less competition for a comparable home.
- Consider homes that need cosmetic work. Competition thins out fast once paint, flooring or an outdated kitchen enter the picture. A renovation loan, such as an FHA 203(k) loan, can roll the cost of the work into your purchase financing so you’re not paying cash out of pocket on day one.2
- Compare more than one lender before you write an offer. Pricing and closing speed both vary by lender, and a broker who shops your scenario across multiple wholesale lenders lets you compare pricing and expected closing timelines before you write the offer, and a dependable closing timeline is something a seller’s agent is watching closely.
Rate movement also affects how many buyers you’re competing against at any given moment. Track where rates stand with our Mortgage Rates & Market guide so you know whether to expect more or less competition in the weeks ahead.
Does a tight market change how you should shop for a mortgage?
It changes the timing more than the method. The Consumer Financial Protection Bureau’s Loan Estimate explainer tells buyers to request Loan Estimates from different lenders, to compare origination charges, and notes that some lenders lock the rate as part of issuing the Loan Estimate while others do not. You can put two of them side by side with our Loan Estimate check.
Pricing differences between lenders grow when rates move fast. Freddie Mac research published in February 2023 found that average mortgage rate dispersion was less than 0.2 percentage point from 2010 to 2021 but averaged about 0.5 percentage point in October and November 2022, as the average rate climbed past 7%.
Timing matters in a competitive market, because an offer can take weeks to close. The CFPB’s rate lock explainer says rate locks are typically available for 30, 45 or 60 days, that an extension may be expensive if the transaction needs more time, and that a locked rate can still change if the loan amount, credit score or verified income changes. Our guides to mortgage rate locks, prequalification vs. preapproval, why preapproval matters and handling multiple offers cover the steps around the offer itself.
What Michigan buyers should know
Michigan’s housing shortage has a number attached to it too: the Michigan State Housing Development Authority estimates the state is still roughly 119,000 housing units short of what residents need.
- The state’s production goal has grown, not shrunk: Michigan released its first five-year Statewide Housing Plan in June 2022 with a goal of 75,000 new or rehabilitated homes. The state hit that mark ahead of schedule and raised the target 53% to 115,000 homes; MSHDA reported 83,777 new or rehabilitated units toward that target through October 2025.
- Progress is tracked regionally, not just statewide: MSHDA created 15 Regional Housing Partnerships so each part of the state can target its own gap instead of applying one statewide fix to markets that look very different from one another.
- State dollars are moving at scale: In fiscal year 2025 alone, MSHDA produced, preserved or financed 12,414 housing units, nearly 2,000 more than its annual target, backed by $2.61 billion that reached almost 45,000 Michiganders.
- New tools target attainable price points: MSHDA’s Housing and Community Development Fund and the Housing Accelerator Fund it launched in 2025 are aimed at the price range where private development has struggled to pencil out on its own.
How does the shortage show up in Michigan’s own numbers?
Michigan tracks its building pace against the state’s goal in public. MSHDA’s Building Michigan Homes tracker measures progress toward the updated target of 115,000 homes by the end of fiscal year 2026 using Census building permit data, and it applies a 5% downward adjustment because about 5% of permitted residential buildings are never finished. Because it counts permits, its totals are a different measure from the new or rehabilitated units MSHDA reports in its plan updates.
| Period | Homes counted toward the goal |
|---|---|
| 2021 (October to December) | 5,087 |
| 2022 | 19,934 |
| 2023 | 19,282 |
| 2024 | 19,967 |
| 2025 | 22,427 |
| 2026 (January to June) | 10,037 |
Source: Michigan State Housing Development Authority, Building Michigan Homes (permit-based counts, viewed October 28, 2026).
The 119,000 shortage figure comes from a specific method. MSHDA’s May 27, 2025 announcement said its analysis of Census data set a 5% vacancy rate as the model of a healthy, balanced market and found Michigan added 21,973 housing units between 2023 and 2024. The estimate has moved quickly: Bridge Michigan reported in March 2025 that MSHDA put the shortage at nearly 190,000 units at the start of 2024 before it dropped to roughly 141,000.
Prices in Michigan’s part of the country have risen faster than the national average. FHFA’s House Price Index report for August 2026, released October 27, 2026, showed prices up 4.4% over 12 months in the East North Central division, against 2.4% nationally. Michigan sits in that division under the Census Bureau map of regions and divisions, alongside Illinois, Indiana, Ohio and Wisconsin. Our guide to regional housing market differences explains why one region can run hot while another cools.
Higher prices carry into a Michigan buyer’s property tax bill. In Michigan, a home’s taxable value is capped while one owner holds it. The year after it sells, that cap comes off and taxable value resets to the state equalized value, which is half of the assessor’s estimate of market value, not automatically half of what you paid. That rule comes from MCL 211.27a, and the Michigan Department of Treasury explains it on its uncapping page. For an owner who stays put, the yearly increase is capped instead: for example, the State Tax Commission’s Bulletin 14 of 2025 set the 2026 inflation rate multiplier at 1.027, a 2.7% cap. Our guide to how property tax assessments work and the Michigan property tax calculator show how to plan for the reset.
State help for buyers has also grown. MSHDA, the state housing agency, said in a February 18, 2026 announcement that it provided over $1 billion in mortgage and down payment assistance loans to 6,193 homebuyers in 2025, the highest number in a calendar year since the agency was created in 1966. Our overview of first-time home buyer grants and programs covers how those programs fit with a purchase loan.
How Align reads the local market
National headlines rarely describe Oakland County. Samantha lives and works here, follows what homes in these neighborhoods actually sell for, and builds your loan around that, not around a national average.
Clear to close is not the same as closing: your purchase agreement sets the closing date, and her job is to have your loan ready well before it.
FAQ: Economic impacts of housing shortages
Here are answers to common questions about the economic impacts of housing shortages.
What causes a housing shortage?
Several constraints stack at once. Restrictive zoning and slow permitting limit what can be built and where. A shortage of skilled construction labor delays projects and raises costs. High land and materials costs push builders toward higher-priced homes where the margins work. And the mortgage rate lock-in effect keeps existing owners from listing, which shrinks resale inventory independent of new construction.
How does a housing shortage affect home prices?
It puts a floor under them. When buyers outnumber available homes, competition bids prices up and keeps them elevated even when sales volume falls, which is why the median existing-home price kept setting records through 2026 even as transaction activity stayed historically weak. That also means price relief usually requires more supply rather than just softer demand.
What does ‘cost burdened’ mean?
A household is cost burdened when it spends more than 30% of gross income on housing, including rent or a mortgage plus utilities, and severely cost burdened above 50%. The threshold matters because households past it cut spending on food, healthcare, transportation and savings. Roughly 22.6 million renter households currently fall into the cost-burdened category. See our guide to affordability challenges in today’s housing market for what that means for buyers as well as renters.
How can buyers compete in a market with limited supply?
Get a fully underwritten preapproval rather than a basic prequalification, so your offer carries the weight of a verified buyer. Widen your geographic search to adjacent submarkets where inventory is looser. Consider homes needing cosmetic work, where competition is thinner, and ask about renovation loan options. Working with a broker who can shop several lenders also lets you compare pricing and closing timelines side by side before you make an offer. Track current conditions with our Mortgage Rates & Market guide.
Is there really a housing shortage in the U.S.?
Most researchers say yes, but not all. The Congressional Research Service wrote in December 2025 that published estimates suggest a shortage of roughly 4 million to 5 million homes, yet there is not universal agreement that one exists at all. The answer depends on assumptions such as the vacancy rate a healthy market needs; Freddie Mac said its earlier analysis assumed a 13% target vacancy rate.
Are home prices included in the inflation rate?
Not directly. The Bureau of Labor Statistics treats spending to buy a house as investment rather than consumption, so the Consumer Price Index measures owners’ equivalent rent instead: the implicit rent owners would pay to rent their own homes. Shelter carried a 35.625% weight in the CPI as of December 2025, with owners’ equivalent rent alone at 26.204%, so housing costs still move the inflation rate.
How much do renters and homeowners pay for housing each month?
According to the Census Bureau’s 2024 American Community Survey release, published September 11, 2025, median gross rent including utilities rose 2.7% to $1,487 in 2024, and the median renter spent 31% of income on it. Median monthly costs for owners with a mortgage rose to $2,035 from $1,960, about 21.4% of income, driven mainly by higher mortgage costs and insurance.
Can home prices fall during a housing shortage?
They can, but a shortage cushions the drop. The FHFA lock-in working paper estimated that higher rates directly lowered prices by 3.3%, while the supply lost to lock-in raised them by 5.7%, so prices rose on net. Short dips still happen: FHFA’s August 2026 index report showed seasonally adjusted monthly changes ranging from a 0.8% decline in New England to a 2.1% gain in the East South Central division.
What is Michigan’s next Statewide Housing Plan?
MSHDA is writing a second version, SHP 2.0. Its Statewide Housing Plan page says public engagement runs through spring and summer 2026 and that SHP 2.0 is scheduled for completion in June 2027. The first plan set eight statewide priorities and 37 goals to address Michigan’s housing supply challenges, so the next version is the place to watch for new state targets.
The bottom line on housing shortages
A housing shortage doesn’t get solved by one strong month of sales or a single rate cut, it gets solved by more homes, and that takes years. In the meantime, competition is what closes the gap: it pushed the median existing-home price to a record $440,600 in June 2026 and left 22.6 million renter households spending more than 30% of income on housing, while a $10.8 billion construction labor shortage and a persistent mortgage rate lock-in effect keep both new and resale supply constrained. For buyers, that means the moves that matter most are the ones inside your control: a strong preapproval, a wider search, and a lender who’s actually shopping your rate.
If you’re ready to compete for a home in a tight market, talk to Align Lending. We’ll shop your scenario across our lender network and get you a verified preapproval so your offer stands out. Call 248-506-5727 or start online.
Footnotes:
1. Example figures in this article are hypothetical and for educational purposes only; they do not constitute an advertisement of credit terms or a rate quote under federal or state lending laws. Your rate and payment will depend on your application, loan program and market conditions. Return to text.
2. Align Lending is not acting on behalf of or at the direction of FHA or HUD. FHA renovation loan program terms are set by HUD and are subject to change. Return to text.
Sources: Cost-burdened renter household count of 22.6 million, including 12.1 million severely cost-burdened households, and the income breakdown of cost burden in 2023, Harvard University Joint Center for Housing Studies, The State of the Nation’s Housing 2025. Definitions of cost-burdened (more than 30% of income on housing) and severely cost-burdened (more than 50%), U.S. Department of Housing and Urban Development. Record median existing-home price of $440,600 in June 2026, up 1.8% from $432,700 a year earlier, and the Housing Shortage Tracker, National Association of Realtors. National housing supply gap of an estimated 4.03 million homes in 2025, up from 3.8 million in 2024, Realtor.com, 2026 Housing Supply Gap Report. Skilled construction labor shortage causing an estimated $10.8 billion in annual economic impact, a 1.98-month average construction delay, and roughly 19,000 fewer single-family homes built in 2024, Home Builders Institute in partnership with the National Association of Home Builders and the University of Denver, June 2025 study. Mortgage rate lock-in effect reducing sale probability by 18.1% per percentage point of rate gap and an estimated 1.33 million home sales prevented between 2022 Q2 and 2023 Q4, Federal Housing Finance Agency, Working Paper 24-03, “The Lock-In Effect of Rising Mortgage Rates” (Batzer, Coste, Doerner and Seiler, 2024). Michigan’s estimated 119,000-unit housing gap, Michigan State Housing Development Authority. Release of Michigan’s first five-year Statewide Housing Plan in June 2022, the original 75,000-unit goal raised to a 115,000-unit target, 83,777 new or rehabilitated units reported through October 2025, and the 15 Regional Housing Partnerships formed in June 2023, MSHDA Statewide Housing Plan. New residential construction data, U.S. Census Bureau.
This article is for informational purposes only and is not intended to provide legal, financial, or tax advice. Housing market data, economic estimates and program details change and vary by source, methodology, and location; confirm current figures with the sources cited and consult a qualified professional about your situation. Example figures are illustrative, are not a rate quote or an offer of credit, and are subject to change. Align Lending is an independent Michigan mortgage broker, NMLS #2041154.
Sources
Every outside source this guide links to, in the order it appears. How we choose and check sources
- Federal Housing Finance Agency researchFederal Housing Finance Agency
- December 15, 2025 Insight on housing shortage estimatescongress.gov
- November 26, 2024 housing supply updateFreddie Mac
- Up for Growth reportedupforgrowth.org
- NAR research on home prices and inventoryNational Association of Realtors
- Primary Mortgage Market SurveyFreddie Mac
- FOMC statementFederal Reserve Board
- September 2026 Consumer Price Index releasebls.gov
- May 13, 2026 report on housing cost burdens in 2024congress.gov
- National Low Income Housing Coalition summary of the 2026 State of the Nation’s Housing reportnlihc.org
- June 17, 2026 release coveragegsd.harvard.edu
- A June 2025 study from the Home Builders Institutehbi.org
- Researchers at the University of Denverdaniels.du.edu
- Census new residential construction and sales dataU.S. Census Bureau
- September 2026 new residential construction reportU.S. Census Bureau
- September 2026 new residential sales reportU.S. Census Bureau
- National Association of Realtors reportedNational Association of Realtors
- October 2026 Beige Book report for the Chicago districtFederal Reserve Board
- Bureau of Labor Statistics construction industry pagebls.gov
- Loan Estimate explainerConsumer Financial Protection Bureau
- Research published in February 2023Freddie Mac
- Rate lock explainerConsumer Financial Protection Bureau
- Michigan State Housing Development Authority estimatesState of Michigan
- Michigan released its first five-year Statewide Housing Plan in June 2022State of Michigan
- The state hit that mark ahead of scheduleState of Michigan
- Building Michigan Homes trackerState of Michigan
- May 27, 2025 announcementState of Michigan
- Bridge Michigan reportedbridgemi.com
- House Price Index report for August 2026Federal Housing Finance Agency
- Census Bureau map of regions and divisionsU.S. Census Bureau
- MCL 211.27aMichigan Legislature
- Uncapping pageState of Michigan
- Bulletin 14 of 2025State of Michigan
- Bureau of Labor Statisticsbls.gov
- 2024 American Community Survey releaseU.S. Census Bureau
Related resources
20-minute read
Urban vs. suburban housing markets: how to choose the right fit
Compare urban vs. suburban housing markets on price per square foot, commute and transportation costs, lot size and living space before you choose.
20-minute read
What is a buyer’s market in real estate, and how do you recognize one?
Learn what a buyer’s market in real estate means, why more than six months of inventory signals one, and how to turn that leverage into a better deal.
19-minute read
The impact of mortgage rate volatility on housing decisions
Learn how mortgage rate volatility affects home buying, why a half-point swing changes your payment by hundreds, and how rate locks protect your budget.
