
Construction loan guide: Types, requirements, and the draw process
A construction loan is short-term financing that pays for land, labor, materials and permits while a house is being built, releasing money in draws as an inspector verifies each completed stage. Fannie Mae’s Selling Guide caps the single-closing version at no single construction period longer than 12 months and no more than 18 months in total, which is why nearly every construction loan you’ll be quoted is written for a year or less.
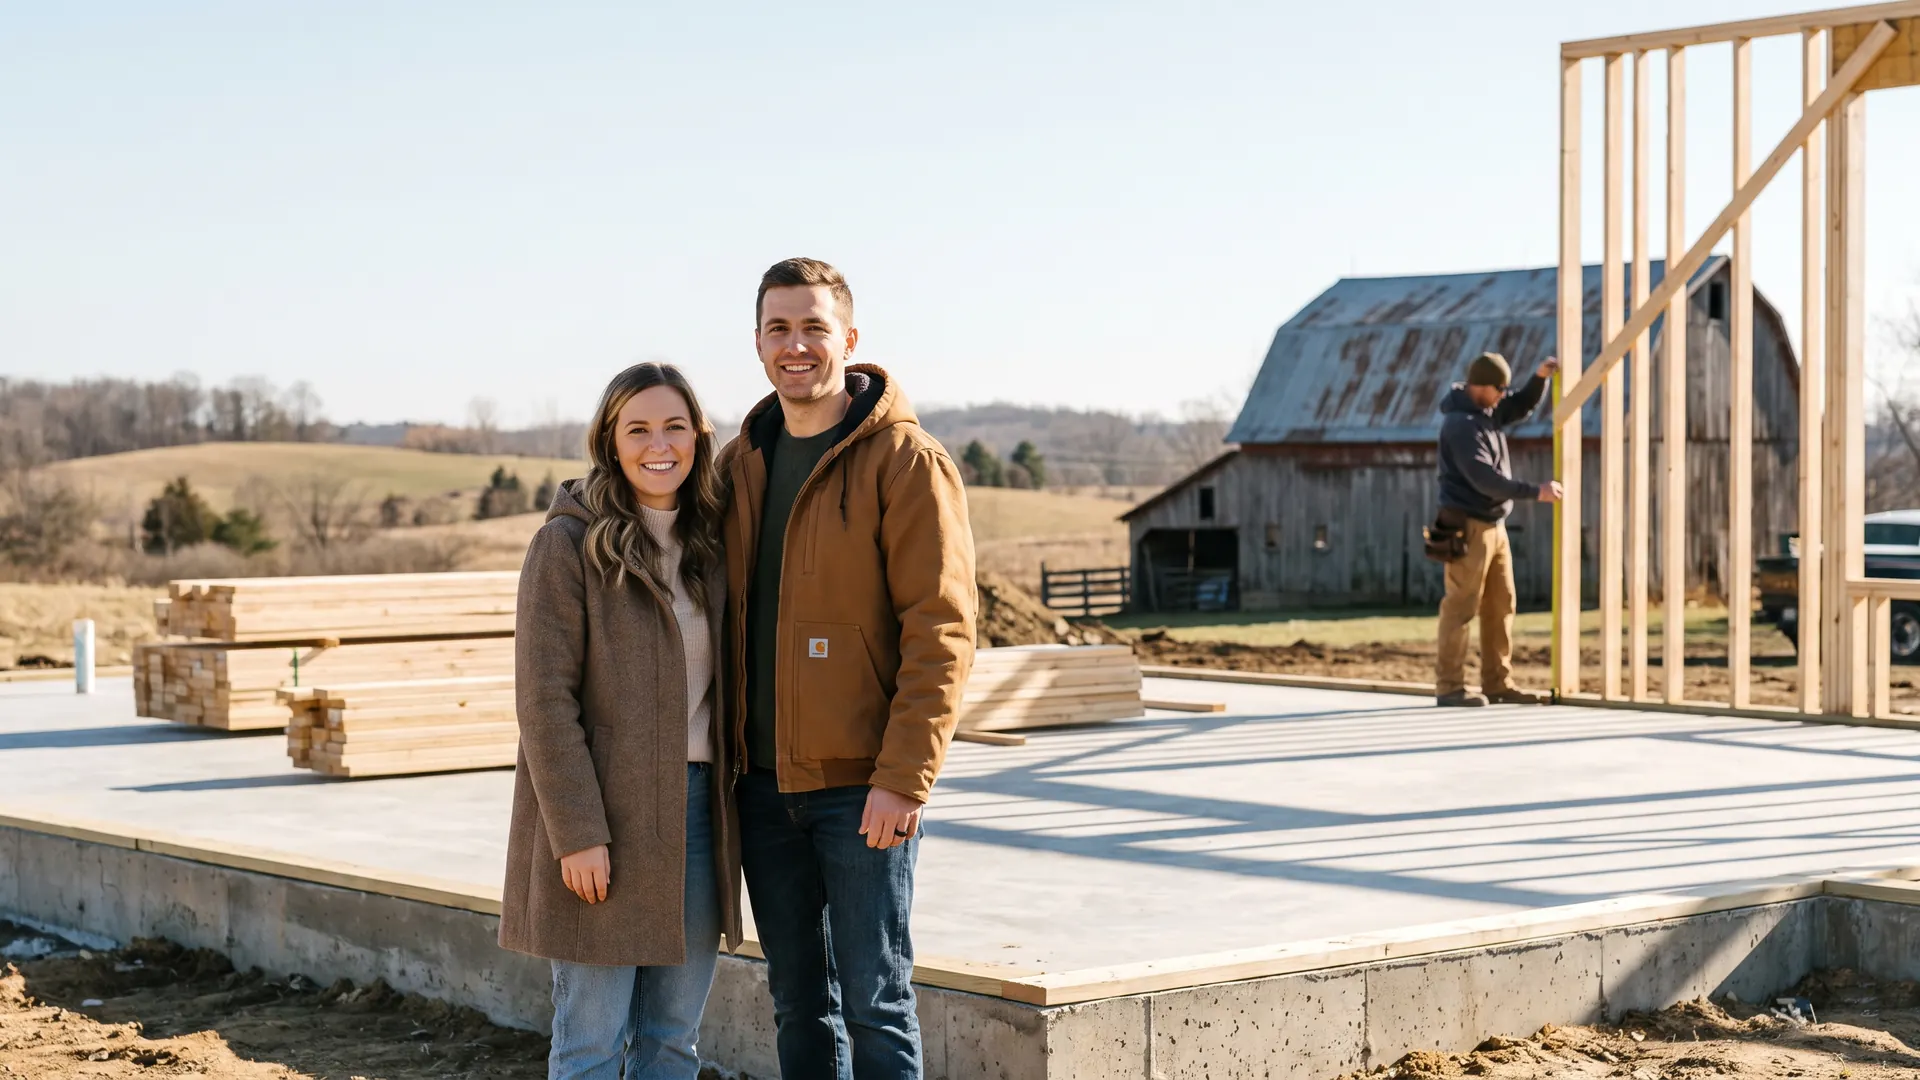
Qualifying is tougher than for a mortgage on a finished house. Lenders in Align’s network typically look for a credit score near 680, a larger down payment than a standard purchase loan, a licensed builder under a signed fixed-price contract, complete plans, a line-item budget and an “as completed” appraisal. Your builder’s file matters nearly as much as yours.
Learn how construction loans work, including the draw schedule, the one-close and two-close structures, what the money covers, and how the balance becomes a permanent mortgage. Still comparing programs? Start with our Loan Types & Programs guide or our Specialty Financing hub.
Key takeaways:
- Money arrives in draws, not one lump sum: A common five-draw schedule releases funds at foundation, framing, mechanicals, drywall and finish, each confirmed by an inspection, and you pay interest only on the balance drawn.
- The 12-month clock is an agency rule, not a lender preference: Fannie Mae allows no single construction period longer than 12 months and no more than 18 months total on a single-closing construction-to-permanent loan; exceed it and the file must be restructured as a two-closing transaction.
- Plan on roughly 680 credit and a sizable down payment: That’s what lenders in Align’s network typically want on a conventional construction loan. Government-backed options reach further: HUD’s FHA rules allow up to 96.5% financing at a 580 decision credit score.
What is a construction loan?
A construction loan is a short-term loan, usually written for 12 months or less, that funds the building of a home in installments called draws rather than handing you the full amount at closing. You pay interest only on the money actually advanced, so the payment starts small and climbs as the house goes up.
That structure exists because there’s no finished collateral yet. A traditional mortgage lends against a house an appraiser can walk through; a construction loan lends against plans, a budget and a builder’s promise. The lender protects itself by metering the money out and inspecting the work before each release. That’s why construction financing sits with bridge loans in our specialty financing category: a temporary instrument with a defined exit.
What are the types of construction loans?
There are three common structures, and the difference that costs the most money is how many times you go to a closing table.
| Structure | Closings | Rate risk | Flexibility | Typical borrower |
|---|---|---|---|---|
| Construction-to-permanent (one close) | 1 | Set before ground breaks | Lower. Terms fixed up front, modifications limited | Owner-occupant on a set timeline |
| Construction-only (two close) | 2 | Higher. Market rate at completion | Higher. Shop the permanent loan separately | Borrower expecting credit or income to improve |
| Owner-builder | 1 or 2 | Same as its underlying structure | Lowest. Few lenders offer it | Licensed or experienced builder building for themselves |
Construction-to-permanent loans
A single-closing construction-to-permanent loan closes once, before construction starts, and converts to a long-term mortgage when the home is finished. Under Freddie Mac’s guide, the note and security instrument for the permanent financing are executed at the closing of the interim construction financing, and with automatic conversion the loan flips to permanent terms on completion with no change to the note. One closing, one set of costs, one round of underwriting. See our guide to construction-to-permanent loans.
Construction-only loans
A construction-only loan finances the build and nothing else. When the house is done the balance comes due, so you pay it off or refinance: a second application, a second appraisal, a second set of closing costs and whatever rates exist that day. Fannie Mae’s period limits don’t apply to two-closing transactions, making this the route for builds that will realistically run past 18 months.
Owner-builder and renovation alternatives
Owner-builder loans let the borrower act as general contractor, and they’re the hardest to place because the lender loses the protection of a licensed third party. Improving an existing house is different territory: see what a renovation loan is, since FHA 203(k), Fannie Mae HomeStyle and Freddie Mac CHOICERenovation carry their own scopes and cost rules, separate from construction-to-permanent guidelines. Michigan’s licensing law lets an owner build a home for their own use (see building a home on a budget), but a lender’s owner-builder rules are separate, so ask about both before you buy materials.
How does the draw schedule work?
A draw schedule maps your builder’s milestones to slices of the loan, and five draws is the common shape. Your builder requests a draw when a stage is finished, the lender sends an inspector to confirm it, and the money goes to the builder, not to you. The percentages are set by your lender and your construction contract, not by any agency rule, so read them before you sign.
| Milestone | Typical share of funds released | What gets inspected |
|---|---|---|
| 1. Site work, permits and foundation | 15% to 20% | Footings and foundation, verified before backfill |
| 2. Framing, roof, windows and exterior doors | 20% to 25% | Framing inspection, structure weather-tight |
| 3. Rough plumbing, electrical and HVAC | 20% | Rough-in inspections, each trade signed off |
| 4. Insulation, drywall and interior trim | 20% | Progress inspection, drywall hung and finished |
| 5. Finishes, fixtures, final grade and cleanup | 15% to 20% | Final inspection and certificate of occupancy |
Two mechanics decide what this costs you. First, interest accrues on the drawn balance only. Hypothetical example, not an offer. Say your commitment is $400,000 and the foundation draw releases $70,000: until the next draw funds, you owe interest on $70,000, not $400,000. By the drywall draw you may be carrying $280,000, so the payment late in the build can run roughly four times the payment at the start.1 Budget for the last two months, not the first.
Second, retainage. Lenders in Align’s network commonly hold back a final portion until the certificate of occupancy issues and signed lien waivers are collected, which keeps a mechanic’s lien off a house you’ve moved into. Pace your schedule against real build times: Census Bureau Survey of Construction data for single-family homes completed in 2024 put contractor-built homes at about 12 months from permit authorization to completion and owner-built homes at 15.1 months. Track the market you’re building into with Census data on new residential sales, and buy independent inspections on top of the lender’s: home inspections for new construction covers what a municipal inspector doesn’t.
How long does a new home take to build now?
Build times shortened in 2025. The National Association of Home Builders reported on September 8, 2026, from the Census Bureau’s Survey of Construction, that homes built by hired contractors took about 11.7 months from permit to completion and owner-built homes 14.3 months, against 7.4 months for homes built for sale. An 11.7-month average sits close to Fannie Mae’s 12-month limit on a single construction period, so read the schedule in your builder’s contract before closing.
For the current pace, the Census Bureau’s New Residential Construction release of October 20, 2026 reported September 2026 single-family starts at a seasonally adjusted annual rate of 859,000, 4.6% below the revised August rate of 900,000, with single-family completions at 840,000 and permits at 845,000.
How do you qualify for a construction loan?
How do you get pre-approved for a construction loan?
Expect lenders in Align’s network to look for a credit score near 680 and a larger down payment than a standard purchase loan on a conventional construction loan, plus documented reserves and a manageable debt-to-income ratio. Get pre-approved before you buy land. Buying a lot first, then finding it fails a lender’s requirements on access, utilities, zoning or soils, is the most expensive avoidable mistake in the process.
What does the lender need from your builder?
Your builder is underwritten too. Lenders generally want the builder’s license, general liability and builder’s risk insurance, a résumé of completed projects, references, financial statements and a signed fixed-price or cost-plus-with-cap contract. Missing builder documentation is the most common source of delay, and it’s the part of the file you can’t fix yourself. New home construction: what to expect shows how production and custom timelines differ.
How does the appraisal work when there’s no house yet?
The appraiser values the home “as completed,” working from your plans, specifications and line-item budget. That number drives your loan-to-value ratio, and Fannie Mae makes the basis depend on lot ownership. If you don’t own the lot at the first advance, the deal is a purchase and LTV uses the lesser of purchase price, meaning construction costs plus lot price, or the “as completed” value. If you already own it, the deal is a limited cash-out refinance and LTV runs off the “as completed” value alone. That’s how land equity substitutes for cash down.
Construction loan options by loan type
Construction lending is a specialty, and plenty of retail banks skip it. Because Align is a broker, we place construction and construction-to-permanent loans through partner lenders that do offer them, including the programs below.
- Conventional: Fannie Mae and Freddie Mac both buy single-closing construction-to-permanent loans, and Fannie’s 12-month and 18-month period limits are the binding constraint. Exceed them and the lender must process the loan as a two-closing construction-to-permanent transaction for it to stay eligible for sale to Fannie Mae. Freddie Mac runs a parallel One-Time Close structure under its own guide.
- FHA: HUD’s Single Family Housing Policy Handbook 4000.1 provides for construction to permanent as a single closing before construction begins, with the borrower contracted to a builder who must be a licensed general contractor. FHA’s maximum loan-to-value is 96.5% at a minimum decision credit score of 580, and 90% for scores of 500 to 579.2
- VA: A VA-backed purchase loan can be used to buy, build or improve a home, and eligible borrowers with a Certificate of Eligibility may put nothing down as long as the price doesn’t exceed the appraised value. VA sets no maximum loan amount for a veteran with full entitlement and no minimum credit score; any score floor you’re quoted is a lender overlay. The funding fee is a percentage of the loan amount varying with down payment and first or subsequent use, waived for veterans receiving VA compensation for a service-connected disability. See the benefits of VA construction loans, and va.gov for the current fee table.3
- USDA: Rural Development’s single-close combination construction-to-permanent option sits inside the Single Family Housing Guaranteed Loan Program and allows up to 100% financing with one closing in eligible rural areas, with the loan note guarantee issued when the interim construction loan closes rather than at completion. The lender must have two years of construction-lending experience, which narrows the field sharply. Guaranteed is a different program from USDA’s Direct loan: Guaranteed generally uses 115% of area median income, while Direct serves low- and very-low-income households. Confirm the address and income limit on USDA’s eligibility site.
What does the VA funding fee add to a VA construction loan?
VA’s funding fee page uses one table for “VA-backed purchase and construction loans.” For Veterans, active-duty service members, and National Guard and Reserve members it lists:
| Down payment | First use | After first use |
|---|---|---|
| Less than 5% | 2.15% | 3.3% |
| 5% or more | 1.5% | 1.5% |
| 10% or more | 1.25% | 1.25% |
Source: U.S. Department of Veterans Affairs, VA funding fee and loan closing costs, viewed November 1, 2026.
On a purchase or construction/permanent loan, the same VA page says only the funding fee can be financed into the loan; all other fees and charges are paid at closing, which on a single-closing build comes before ground breaks. Hypothetical example, not an offer: under that table, a first-use borrower with less than 5% down on a $400,000 loan would owe 2.15%, or $8,600, unless exempt.
Our VA funding fee calculator runs the table on your own numbers.
Which parts of the build budget do the draws pay for?
For how a new home’s price splits between construction, lot and builder margin, see building a home on a budget.
Inside the construction share of a new home’s price, interior finishes were the largest item at 24.1%, then major system rough-ins at 19.2% and framing at 16.6%, the National Association of Home Builders reported in its survey of 2024 costs, published January 23, 2025. Those items fall in draws two through five, where an unapproved change order moves a budget most.
The Census Bureau’s 2025 characteristics of new housing say 9% of homes built for sale had an individual septic system, a reminder that a rural lot can need well and septic work paid from the first draw. Look the lot up on FEMA’s Flood Map Service Center, the official source for flood hazard maps, before you buy it.
What construction loans cover, and what they don’t
Construction loans generally cover the costs inside your approved budget: the lot purchase or payoff of existing lot financing, site work and utility hookups, permits and municipal fees, labor and materials, the builder’s fee, and a contingency reserve. Many lenders will also finance an interest reserve, so build-period interest comes out of the loan instead of your checking account.
What falls outside is mostly what you spend before there’s a loan: design fees paid up front, soil tests and surveys ordered pre-closing, landscaping past the approved scope, furnishings, and any mid-build upgrade without a signed change order. Change orders are the quiet budget killer, because an addition your lender hasn’t approved doesn’t increase your draws. Our breakdown of what it costs to build a house shows where overruns land.
One disclosure quirk matters when you shop. Under Regulation Z, a creditor may treat construction-permanent financing as one transaction or more than one, so your lender can issue a single combined Loan Estimate and Closing Disclosure, or separate sets for each phase. Two lenders can present the same deal on differently shaped paperwork, so compare the numbers, not the format. Keep the CFPB’s walkthrough of how to compare loan costs on a Loan Estimate open, and use National Association of Home Builders resources to pressure-test a builder’s budget.
How large can a construction loan be before it becomes a jumbo?
A conventional construction-to-permanent loan has to fit the conforming loan limit to be sold to Fannie Mae or Freddie Mac. The Federal Housing Finance Agency set the 2026 limit for one-unit properties at $832,750 in most of the United States, an increase of $26,250 from 2025. A larger build is a jumbo loan under each lender’s own rules. Check your county on our loan limits tool; FHA limits are covered in FHA loan limits.
Fannie Mae’s Selling Guide topic B5-3.1-02 (May 6, 2026) adds that it cannot buy the loan until construction is complete and the terms have converted, with maximum loan-to-value ratios set by its Eligibility Matrix.
How does a construction loan convert to a permanent mortgage?
On a single-closing loan, conversion is a modification, not a new loan. Fannie Mae permits changes to the interest rate, loan amount, loan term and amortization type at or before conversion, but the only amortization change allowed is adjustable-rate to fixed-rate, and a loan-amount increase is limited to documented increases in construction costs. Change any other loan term and the lender must process the file as a two-closing transaction instead. On a two-closing loan, conversion is a refinance: re-document income and assets, order a new appraisal, pay closing costs again and take the market rate that day. Useful if you expect credit or income to improve during the build, a bad trade if your file is already strong. If you’re carrying an existing home into the new one, bridge loans solve a different piece of the same timing problem.
On taxes: the IRS lets you treat a home under construction as a qualified home for up to 24 months, starting any time on or after the day construction begins, but only if it becomes your qualified home when ready for occupancy. Interest paid during the build can then qualify as deductible home mortgage interest, subject to the usual debt limits.4
When does a renovation loan fit better than a construction loan?
For a house that’s already standing. HUD’s 203(k) program page says the Limited 203(k) finances up to $75,000 of repairs into the mortgage, while the Standard 203(k) needs rehabilitation costs of at least $5,000 within the FHA limit for the area. See the benefits of FHA 203(k) loans.
Fannie Mae’s HomeStyle Renovation caps renovation costs at 75% of the lesser of purchase price plus renovation costs or the “as completed” value on a purchase, and 75% of the “as completed” value on a refinance, per Selling Guide B5-3.2-02 (December 10, 2025). Freddie Mac’s CHOICERenovation page cites Harvard research that almost 80% of the nation’s 137 million homes are at least 20 years old and 40% at least 50.
Older houses add a rule: the EPA’s Renovation, Repair and Painting Program page (updated June 17, 2026) says firms paid to disturb paint in pre-1978 homes must be lead-safe certified. Compare options in financing home renovations.
What Michigan buyers should know
Michigan’s climate and permitting calendar tighten a construction loan’s timeline in ways a national guide misses, and both cost you interest carry.
- Footings must reach 42 inches below grade: Michigan Residential Code R403.1.4 requires all exterior footings and foundation systems to extend 42 inches below actual grade, deeper than warmer states demand. That means more excavation, more concrete and a bigger first draw than the identical plan needs in the South. A building official may modify the depth on documented evidence of local conditions.
- Your permit runs on a 180-day clock: Under Michigan Residential Code R105.5, adopted under the Stille-DeRossett-Hale Single State Construction Code Act, a permit becomes invalid if the authorized work isn’t begun within 180 days of issuance, or if work is suspended or abandoned for 180 days after it starts. The building official is authorized to grant, in writing, one or more extensions of not more than 180 days each, but each one has to be requested in writing with justifiable cause demonstrated. A financing delay that idles the site can quietly cost you the permit.
- The short pour season compresses the draw calendar: Breaking ground in late fall can park a build between the foundation and framing draws all winter while interest accrues on what’s advanced. Inside Fannie Mae’s 12-month period, a lost winter is most of your cushion, so schedule backward from a spring start. Permits are administered locally, so confirm your township’s real turnaround and see what you need to know about permits.
How does Michigan law protect your construction draws?
Each draw request should come with the contractor’s sworn statement under MCL 570.1110; how that statement and lien waivers keep liens off the house is covered in building a home on a budget.
Subsection (11) of that law makes it a crime for a contractor or subcontractor to give an owner a false sworn statement with intent to defraud in order to draw money:
| Amount of the false sworn statement | Offense | Maximum penalty |
|---|---|---|
| Less than $200 | Misdemeanor | 93 days and/or a fine of $500 or 3 times the amount, whichever is greater |
| $200 to less than $1,000 | Misdemeanor | 1 year and/or a fine of $2,000 or 3 times the amount |
| $1,000 to less than $20,000 | Felony | 5 years and/or a fine of $10,000 or 3 times the amount |
| $20,000 or more | Felony | 10 years and/or a fine of $15,000 or 3 times the amount |
Source: MCL 570.1110(11); prior convictions can move a statement into a higher tier.
Licensing matters too. Under MCL 339.2412, a residential builder who was not licensed while doing the work cannot sue to collect for it or lien the property, and in an action by a prosecutor or the attorney general a court must assess a civil fine of $5,000 to $25,000 against an unlicensed person who violates section 601.
What Michigan property tax steps come with a new build?
Under MCL 211.7cc, the principal residence exemption affidavit says the home is owned and occupied as your principal residence on the date you sign it, and is filed with the local tax collecting unit by June 1 for the summer levy or November 1 for the winter levy. Treasury’s exemption page says it covers local school operating millage up to 18 mills, so a move-in after June 1 leaves that summer bill without it.
Plan the tax number from the finished house at its address, not the vacant lot’s bill. As Samantha puts it, “We need the actual property.” Our Michigan property tax calculator looks up the published millage for an address; see also how home improvements affect property taxes.
How Align handles specialty financing
Specialty loans are where a single bank's menu runs out. Align places HomeStyle and FHA 203(k) renovation loans, non-warrantable condo loans, DSCR loans and standalone HELOCs through multiple wholesale lenders.
Samantha handles these files herself, from the first conversation to the closing table, with a processor supporting her behind the scenes. Complicated and impossible are not the same thing.
FAQ: Construction loans
Here are answers to common questions about construction loans.
How does a construction loan draw schedule work?
The builder submits a draw request after finishing a defined stage: site work, foundation, framing, mechanicals, drywall, finish. The lender sends an inspector to confirm the work, then releases that portion of funds directly to the builder. You pay interest only on the amount drawn so far, so payments start small and grow as the house goes up. Our guide to new home construction shows how those stages line up with a builder’s schedule.
What is the difference between a construction-to-permanent and a construction-only loan?
A construction-to-permanent loan has one closing: it funds the build, then converts to a long-term mortgage when the home is complete. A construction-only loan covers just the build and must be paid off or refinanced at completion, which means a second closing, a second set of costs and exposure to whatever rates exist that day. See construction-to-permanent loans for how conversion works.
Do construction loans cover the cost of the land?
Usually yes, if you buy the lot as part of the project. Most lenders roll the land purchase into the loan or credit equity in land you already own toward the down payment, which is why Fannie Mae runs LTV off the “as completed” value when you’re already the lot owner. Design and architectural fees paid before closing often aren’t covered. Our breakdown of what building a house costs covers the pre-closing spend.
What documents do lenders require for a construction loan?
Plan on complete architectural plans and specifications, a line-item cost breakdown, a signed fixed-price contract, the builder’s license, insurance and financial history, permits or proof they’re pending, an “as completed” appraisal, and your standard income, asset and credit documentation. Missing builder documentation is the most common cause of delays. Line up your new-construction inspection plan too, since inspection timing drives when draws release.
Can you do a cash-out refinance with a construction-to-permanent loan?
Not on a single-closing loan sold to Fannie Mae. Selling Guide topic B5-3.1-02, dated May 6, 2026, says cash-out refinance transactions are not eligible for single-closing construction-to-permanent mortgages. Cash out has to come from a separate transaction, and once the new house is finished and converted, a later refinance is its own loan. Our guide to the cash-out refinance explains how that works.
Do construction loans have to meet the ability-to-repay rule?
Not for a short construction phase. Under 12 CFR 1026.43(a)(3), the ability-to-repay and qualified mortgage provisions in paragraphs (c) through (f) do not apply to a temporary or “bridge” loan with a term of 12 months or less, or to a construction phase of 12 months or less of a construction-to-permanent loan. The permanent phase gets no such exemption, so your debt-to-income ratio still matters.
When do you start making payments on a construction loan?
It depends on how the loan is written. The Consumer Financial Protection Bureau’s construction loan explainer, last reviewed September 11, 2024, says payments sometimes start six to 24 months after the loan is made, and that construction loan rates are generally higher than rates on the longer-term mortgages used to buy a home. Ask each lender for the first payment date in writing and how the payment changes at conversion.
The bottom line on construction loans
A construction loan is short-term financing that pays for land, labor, materials and permits in draws tied to inspected milestones, and you pay interest only on what’s been advanced. Fannie Mae allows no single construction period longer than 12 months and no more than 18 months total on a single-closing construction-to-permanent loan, and lenders in Align’s network typically want roughly 680 credit, a larger down payment than a standard purchase loan, a licensed builder and an “as completed” appraisal. One close means one set of costs and a rate set before ground breaks; two closes buy flexibility and hand you the market’s rate at completion. FHA, VA and USDA reach further down the down-payment scale.
If you’re ready to build, talk to Align Lending. We’ll shop construction and construction-to-permanent programs across our lender network and put the draw schedules, construction period limits and conversion terms side by side. Call 248-506-5727 or start online.
Footnotes:
1. Example figures in this article are hypothetical and for educational purposes only; they do not constitute an advertisement of credit terms or a rate quote under federal or state lending laws. Your draw amounts, interest carry, loan terms and payments will depend on your builder’s contract, your draw schedule, your application and market conditions. Return to text.
2. Align Lending is not acting on behalf of or at the direction of FHA or HUD. FHA construction-to-permanent requirements, loan-to-value limits and credit standards are set by HUD and are subject to change. Return to text.
3. Align Lending works with VA-approved lenders and is not endorsed or sponsored by the Dept. of Veterans Affairs or any government agency. VA loan eligibility, entitlement and funding fee amounts are set by the Department of Veterans Affairs and are subject to change; confirm current figures at va.gov. Return to text.
4. This is general information, not tax advice. Whether construction-period interest is deductible depends on your individual circumstances, on whether the property becomes your qualified home when ready for occupancy, on applicable debt limits, and on whether you itemize. Consult a qualified tax professional about your situation. Return to text.
Figures current as of August 2026; verify with the linked source before relying on them. Sources: single-closing construction-to-permanent construction period limits (no single period of more than 12 months, total not to exceed 18 months), the requirement to process the loan as a two-closing transaction if exceeded, the purchase versus limited cash-out refinance LTV bases, and permitted modifications at conversion to the interest rate, loan amount, loan term and amortization type, with the only permitted amortization change being adjustable-rate to fixed-rate, loan-amount increases limited to documented increased construction costs, and changes to any other loan term requiring a two-closing transaction, Fannie Mae Selling Guide B5-3.1-02 and B5-3.1-01. One-Time Close execution of the permanent note and security instrument at the interim construction closing, and automatic conversion with no change to the note, Freddie Mac Single-Family Seller/Servicer Guide (Construction Conversion and Renovation Mortgages). FHA construction to permanent as a single closing with a licensed general contractor, and maximum loan-to-value of 96.5% at a minimum decision credit score of 580 and 90% for scores of 500 to 579, HUD Single Family Housing Policy Handbook 4000.1. VA-backed purchase loans usable to buy, build or improve a home, the no-down-payment condition that the price not exceed the appraised value, the Certificate of Eligibility requirement, and the funding fee and its exemption for veterans receiving VA compensation for a service-connected disability, U.S. Department of Veterans Affairs (va.gov). Single-close combination construction-to-permanent financing, up to 100% financing, issuance of the loan note guarantee at the interim construction closing, the two-year lender construction-lending experience requirement, and the Guaranteed program’s 115% of area median income limit (distinct from the Single Family Housing Direct program), USDA Rural Development, Single Family Housing Guaranteed Loan Program. Creditor option to treat construction-permanent financing as one transaction or more than one, 12 CFR § 1026.17(c)(6)(ii) and Regulation Z Appendix D; Loan Estimate comparison guidance, Consumer Financial Protection Bureau. Treatment of a home under construction as a qualified home for up to 24 months beginning on or after the day construction begins, IRS Publication 936. Exterior footings and foundation systems required to extend 42 inches below actual grade, Michigan Residential Code R403.1.4. Permit invalidity if work is not begun within 180 days after issuance or is suspended or abandoned for 180 days after commencement, and the building official’s authority to grant in writing one or more extensions of not more than 180 days each on written request with justifiable cause demonstrated, Michigan Residential Code R105.5, promulgated under the Stille-DeRossett-Hale Single State Construction Code Act, 1972 PA 230, MCL 125.1501 to 125.1531. Average length of time for single-family homes completed in 2024, about 12 months from permit authorization to completion for contractor-built homes and 15.1 months for owner-built homes, U.S. Census Bureau, Survey of Construction, 2024 data. Current new residential sales data, U.S. Census Bureau, New Residential Sales (linked for the live figures rather than quoted here, since they are revised on an ongoing basis). Credit score, down payment, contingency, interest reserve, retainage and lien waiver practices reflect terms observed among wholesale lenders in Align Lending’s network and are not agency requirements.
This article is for informational purposes only and is not intended to provide legal, financial, or tax advice. Construction contracts, builder agreements and lien waivers should be reviewed by a licensed real estate professional or attorney in your state. Loan program requirements, construction period limits, loan-to-value caps, funding fees and building code provisions change and vary by lender, program and jurisdiction; confirm your figures with your Loan Estimate and Closing Disclosure and consult a qualified professional about your situation. Figures shown are illustrative, are not a rate quote or an offer of credit, and are subject to change. Align Lending is an independent Michigan mortgage broker, NMLS #2041154.
Sources
Every outside source this guide links to, in the order it appears. How we choose and check sources
- Fannie Mae’s Selling GuideFannie Mae Selling Guide
- HUD’s FHA rulesU.S. Department of Housing and Urban Development
- Census Bureau Survey of Construction dataeyeonhousing.org
- Census data on new residential salesU.S. Census Bureau
- The Census Bureau’s Survey of Constructioneyeonhousing.org
- New Residential Construction releaseU.S. Census Bureau
- Va.gov for the current fee tableU.S. Department of Veterans Affairs
- USDA’s eligibility siteUSDA Rural Development
- Survey of 2024 costseyeonhousing.org
- 2025 characteristics of new housingU.S. Census Bureau
- FEMA’s Flood Map Service CenterFEMA Flood Map Service Center
- A creditor may treat construction-permanent financing as one transaction or more than oneConsumer Financial Protection Bureau
- How to compare loan costs on a Loan EstimateConsumer Financial Protection Bureau
- National Association of Home Builders resourcesNational Association of Home Builders
- Set the 2026 limit for one-unit propertiesFederal Housing Finance Agency
- The IRS lets you treat a home under construction as a qualified homeInternal Revenue Service
- 203(k) program pageU.S. Department of Housing and Urban Development
- Selling Guide B5-3.2-02Fannie Mae Selling Guide
- CHOICERenovation pageFreddie Mac
- Renovation, Repair and Painting Program pageU.S. Environmental Protection Agency
- Michigan Residential Code R403.1.4 requireslaw.cornell.edu
- MCL 570.1110Michigan Legislature
- MCL 339.2412Michigan Legislature
- MCL 211.7ccMichigan Legislature
- Exemption pageState of Michigan
- 12 CFR 1026.43(a)(3)Consumer Financial Protection Bureau
- Construction loan explainerConsumer Financial Protection Bureau
Related resources
20-minute read
What Is a Renovation Loan? How to Finance a Home and Its Remodel Together
See how renovation loans finance a home purchase and remodel in one mortgage using after-improved value, and compare 203(k), HomeStyle and HELOC options.
20-minute read
Condominium Financing: What You Need to Know Before Buying a Condo
Learn how condominium financing works, why some condos are non-warrantable and what lenders review before approving your condo loan application.
20-minute read
Alternative financing options for home buyers: 6 paths beyond a traditional mortgage
Compare alternative financing options for home buyers, including seller financing, lease-to-own, bank statement loans and flexible government programs.
