
How to renovate a kitchen on a budget
Two decisions control a kitchen renovation budget: whether you move the layout, and what you do with the cabinets. Published remodeling cost surveys put a minor kitchen remodel at roughly $15,000 to $27,000 nationally, while major and upscale projects commonly run past $100,000, and cabinetry alone typically takes 25% to 30% of whatever you spend.
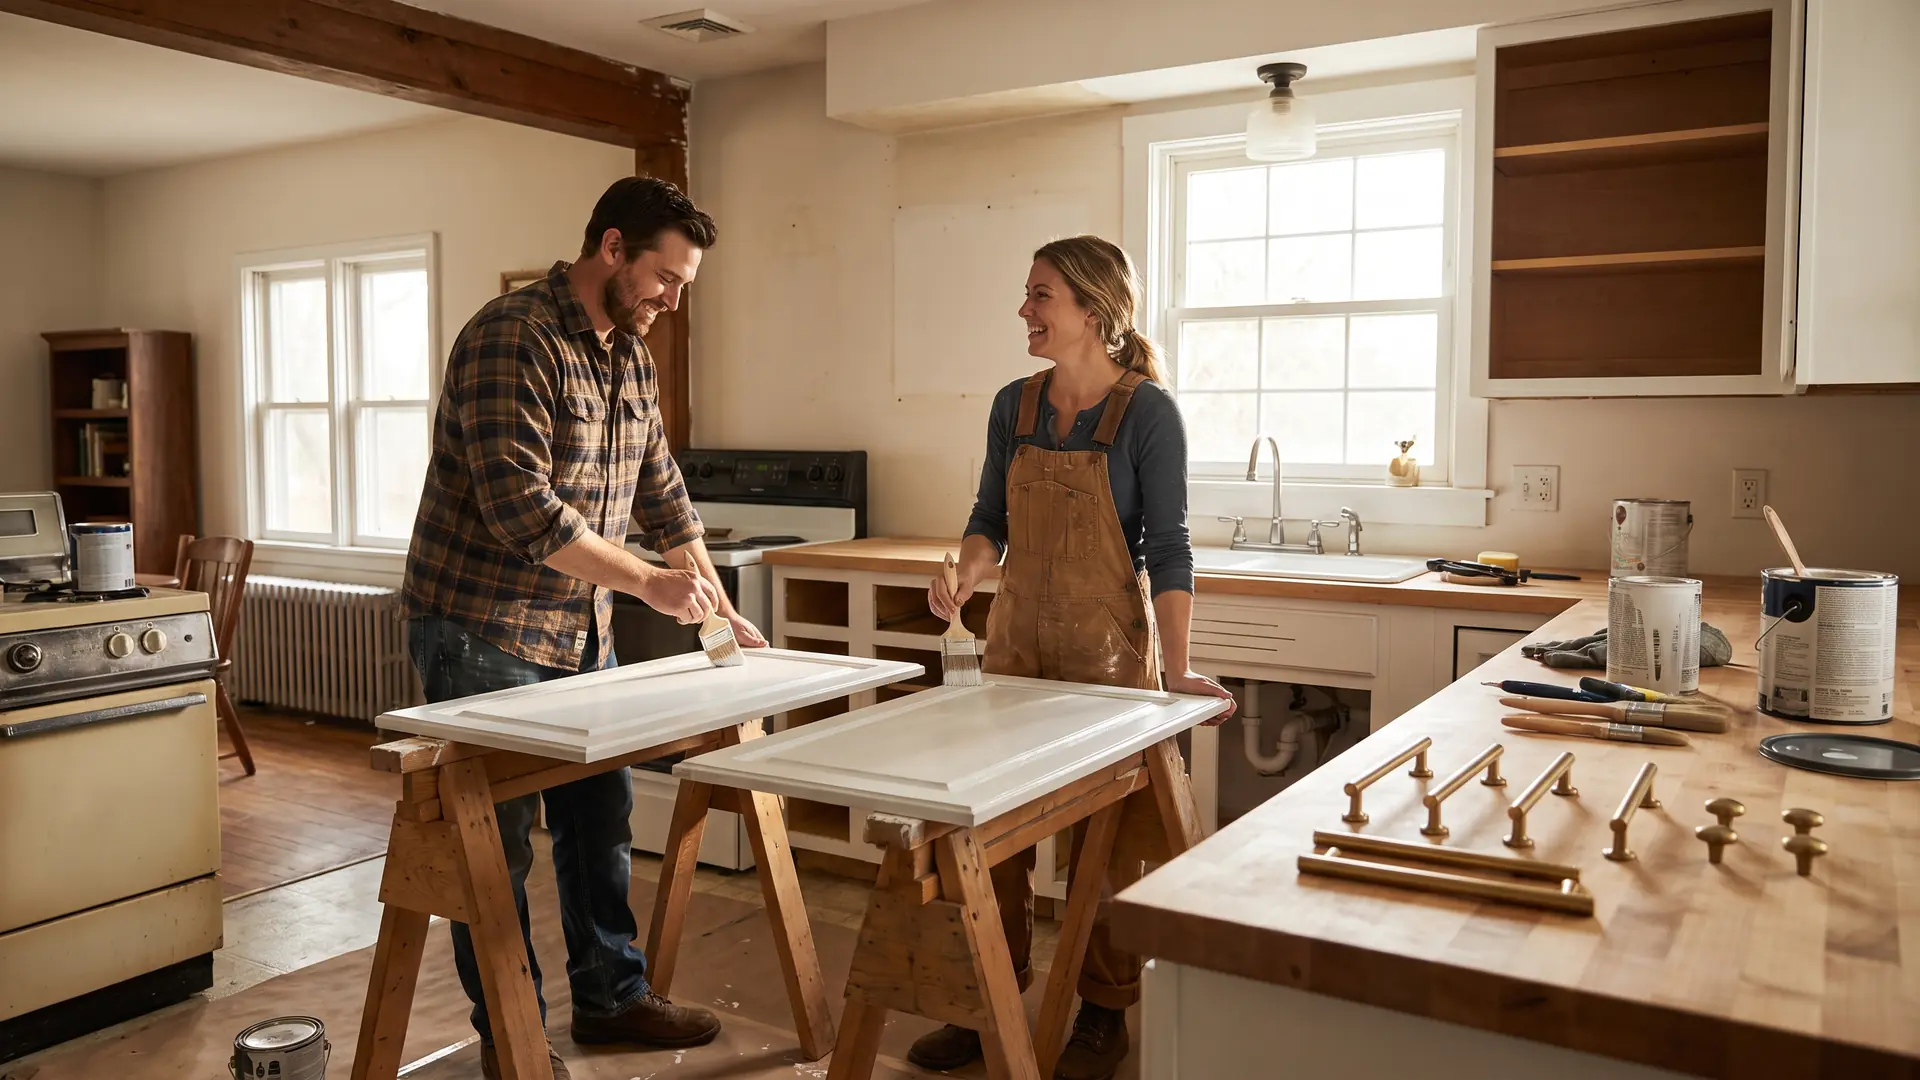
Keeping the sink, the range, and the gas line where they already are avoids plumbing and electrical relocation, the change that quietly adds cost to every trade on the job. Refinishing sound cabinet boxes instead of replacing them can save five figures. Then hold back a 20% contingency, because opened walls in older homes rarely reveal good news.
Learn how to renovate a kitchen on a budget, including what each scope tier really costs, how to choose between refinishing and replacing cabinets, which work is worth doing yourself, and how homeowners pay for the job. For wider context, see our Homeownership guide and our Home Improvement & Design hub.
Key takeaways:
- The layout decision comes first: Leaving the sink, range, and refrigerator in place avoids relocating all 3 systems, plumbing, electrical, and gas, which is the single largest lever on a kitchen budget.
- Cabinets run 25% to 30% of the total: Painting or refinishing sound boxes, or buying stock and ready-to-assemble units, is where most of the savings on a budget kitchen are found.
- Hold back a 20% contingency: Older homes routinely surface wiring, plumbing, or subfloor problems once demolition starts, and a budget with no cushion stalls at the first surprise.
What does a budget kitchen renovation actually cost?
A minor kitchen remodel, new surfaces, hardware, and fixtures with the layout and cabinet boxes left alone, typically runs about $15,000 to $27,000 nationally, while a major remodel that replaces cabinetry and moves systems commonly exceeds $100,000 and has been reported near $158,500 at the upscale end.1 This Old House places a typical remodel between roughly $14,600 and $41,485, the band most owner-occupied projects land in.
The spread is that wide because “kitchen remodel” covers three different projects.
- Cosmetic refresh: Paint, hardware, lighting, a faucet, and a backsplash. Nothing moves and no system is touched, which makes this the lowest tier by far.
- Minor remodel: Refinished or refaced cabinets, new countertops, a sink, flooring, and mass-market appliances, layout unchanged. This is where the $15,000 to $27,000 range lives.
- Major remodel: New cabinetry, relocated plumbing and electrical, sometimes a wall removed. Six figures is common, and the contingency has to be larger.
Angi publishes current kitchen remodel cost data by project scope if you want to test a contractor’s bid, a sanity check, never a quote for your kitchen.
Where the money goes in a kitchen budget
Cabinets are the largest line item on almost every kitchen, followed by labor and countertops, with appliances usually fourth. Savings come from the top of that list, not the bottom.
| Line item | Typical share of the budget | Budget-tier option | Splurge option |
|---|---|---|---|
| Cabinets | Largest, commonly 25% to 30% | Refinish, paint, or reface existing boxes; stock or RTA units | Semi-custom or custom cabinetry |
| Labor | Usually second-largest | Keep the layout; do demo, paint, and hardware yourself | Full design-build with project management |
| Countertops | Usually third | Laminate, butcher block, or resurfacing | Quartz or natural stone slab |
| Appliances | Usually fourth | Mass-market packages, floor models, scratch-and-dent | Pro-style ranges, panel-ready refrigeration |
| Flooring | Scales with scope | Luxury vinyl plank over a sound subfloor | Tile or site-finished hardwood |
| Backsplash | Small line, outsized return | Peel-and-stick, beadboard, or subway tile | Handmade tile or slab backsplash |
| Lighting | Small line, outsized return | Big-box fixtures plus under-cabinet LED | Designer fixtures, recessed can layout |
Build in a 20% contingency
Plan the work at your budget, then hold 20% of it aside. On an $18,000 kitchen that’s $3,600 you don’t spend on tile, and at 25% to 30%, cabinets are $4,500 to $5,400 of that same $18,000, which is why the cabinet decision is the budget decision.2 Older homes surface ungrounded wiring, galvanized supply lines, and soft subfloor often enough that the cushion is a planning assumption, not pessimism.
What should you keep, and what should you change?
Start by writing down what already works, because every item on that list is money you don’t spend. Sound cabinet boxes, a workable layout, appliances with years left, and a decent floor are assets a budget kitchen gets built around.
Then split the rest into two columns: what bothers you daily, and what bothers you in photos. Daily annoyances, thin counter space, bad light over the sink, drawers that stick, are worth real money because you feel the fix every morning. Style complaints usually yield to paint, hardware, and lighting. If resale matters, our guide to renovation ideas to boost home value covers which improvements hold their value, and Bob Vila’s kitchen renovation budgeting walkthrough checks a contractor’s line items.
Why keeping the existing layout saves the most money
Moving a sink, a range, or a refrigerator is the most expensive decision in a kitchen, because it doesn’t add one cost, it adds a plumber, an electrician, possibly a gas fitter, patching, and inspection time. A cosmetic kitchen has no rough-in stage. A relocated kitchen does.
Relocation also changes the paperwork. New or moved supply and drain lines, added circuits, and venting a hood outside generally require permits, while replacing a faucet or painting cabinets in place generally doesn’t. The dividing line is systems versus surfaces. Our guide to home renovation permits covers which projects trigger one, and our explainer on how new building codes affect home purchases covers what happens when a jurisdiction adopts a newer standard.
How should you handle the cabinets?
If the boxes are solid and square, refinishing or refacing is almost always the right budget call, it addresses 25% to 30% of the total without paying for new carcasses, demolition, or disposal. Replacement earns its cost when boxes are water-damaged, when particleboard has swelled, or when the configuration is genuinely unusable.
| Approach | Relative cost | Timeline | Durability | DIY feasibility |
|---|---|---|---|---|
| Paint or refinish existing boxes | Lowest, materials plus your labor | Several days to two weeks | Good on solid wood and plywood; weakest on swollen particleboard | High. Prep is the whole job |
| Reface (new doors, fronts, veneer) | Low to moderate, a fraction of replacement | About a week on site | As durable as the boxes already were | Moderate. Veneer work is unforgiving |
| Stock or ready-to-assemble (RTA) | Moderate, new boxes at the lowest price point | Order lead time, plus assembly and install | Varies widely; look for plywood boxes and solid drawer boxes | Moderate for assembly; install demands precision |
| Semi-custom or custom | Highest, the line that breaks budgets | Weeks of lead time, often months | Best, with the widest finish and hardware options | Low, professional install expected |
Two details decide whether a refinish reads as a remodel or a shortcut. Degrease, sand, and prime before any color goes on, cabinets carry years of cooking film, and paint over it peels at the handles first. And replace the hardware: new pulls cost little and change the room more than the color does.
Which low-cost upgrades change a kitchen the most?
After cabinets, the best visual return per dollar comes from surfaces that don’t touch a system. Most need no permit, and most are realistic weekend work.
- Countertops: Laminate and butcher block are the budget tier, and resurfacing renews an existing top for less than replacement. Butcher block reads warmer than its price suggests, but it needs oiling.
- Backsplash: Peel-and-stick tile, beadboard, and plain subway tile cover the same square footage for a small share of the budget. Buy about 10% more material than the measurement calls for so breakage doesn’t stop the job.
- Lighting: A new fixture plus under-cabinet LED strips changes both the look and the usability of the counter. A dimmer on the main fixture is the cheapest upgrade in the room.
- Flooring: Luxury vinyl plank over a sound subfloor is the budget standard and can often go in without pulling cabinets.
- Open shelving: Removing one upper cabinet run for shelves opens a small kitchen for almost nothing, and paint goes on last, once the counters are in.
What should you do yourself, and what should you hire out?
Labor is usually the second-largest line, so the work you take on yourself is the second-biggest saving after the cabinet decision. The dividing line is the one the permit office draws: surfaces are fair game, systems are not.
- Worth doing yourself: Non-structural demolition, cabinet painting and refinishing, hardware swaps, backsplash installation, floating shelves, and interior painting. Our list of DIY home renovation projects covers where the stop line falls on each job.
- Hire a licensed trade: Anything involving gas, new or relocated circuits, panel work, moved supply or drain lines, or structural changes. These carry permits, inspections, and liability, and they’re what an appraiser or an insurer asks about later.
- Judgment calls: Countertop templating and install, cabinet hanging, and appliance hookups. A miscut slab costs more to fix than the labor you saved.
Get three written bids on the same written scope, and read them for what’s excluded. NAHB remodeling market research tracks how busy the sector is, a proxy for your scheduling leverage.
How do you save on appliances?
Appliances typically rank fourth in the budget, which is exactly why they’re a poor place to splurge on a budget kitchen.
- Buy the package, not the pieces: Retailers routinely discount multi-appliance bundles, and matching finishes cost less bought together than assembled one at a time.
- Floor models and scratch-and-dent: A dent on a panel that ends up against a cabinet is a discount with no consequence. Confirm the warranty first.
- Compare operating cost, not just price: The estimated annual operating cost on the yellow energy label follows you for a decade. Our guide to energy-efficient home upgrades covers how those savings stack.
- Repair before you replace: A service call on a working dishwasher is a fraction of replacement, and one more cycle out of it frees that money for the cabinets.
How do you pay for a kitchen renovation?
Small refreshes are usually best paid in cash; larger remodels are usually financed against the home. Four options cover almost every kitchen.
- Cash or a short savings runway: The cheapest financing is none. On a cosmetic refresh, paying as you go avoids closing costs entirely.
- Home equity loan or HELOC: Borrows against equity you already have and leaves your first mortgage alone, which matters if that mortgage carries a rate you’d rather not disturb.
- Cash-out refinance: Replaces the existing mortgage with a larger one and returns the difference in cash. It fits best when refinancing improves your terms anyway.
- Renovation loan: Lends against the home’s after-improvement value rather than its condition today. Fannie Mae’s HomeStyle Renovation, Freddie Mac’s CHOICERenovation, and the FHA 203(k) all work this way, which makes them useful when there isn’t enough equity yet to borrow against.3
Our guide to financing home renovations compares them side by side, what a HomeStyle renovation loan is covers the conventional version, and how a renovation loan works explains the draw schedule that pays your contractor. Because Align is a broker, we can place a HomeStyle, a CHOICERenovation, or a 203(k) through partner lenders instead of the one product a single bank sells, and since fewer lenders offer renovation loans, pricing and draw handling vary widely.
What Michigan homeowners should know
Michigan runs one statewide construction code that local building departments enforce, so the code answer is the same in Waterford as in Traverse City. While the permit, the fee schedule, and the turnaround are entirely local.
- One code, local permits: The Michigan Residential Code adopts the 2015 International Residential Code by reference and is administered by the Bureau of Construction Codes at the Department of Licensing and Regulatory Affairs, while the permit itself comes from the city, village, or township where the house sits.4
- Licensed contractor, not a handshake: Michigan licenses residential builders and residential maintenance and alteration contractors under Article 24 of the Occupational Code, 1980 PA 299. Verify the license with the state before money changes hands, and treat a contractor who asks you to pull their permit as a warning about their licensing.
- The permit reaches your assessor: Michigan limits how much a property’s taxable value can rise year to year, but new construction and improvements are handled separately from that limit. Read our guide to the impact of home improvements on property taxes before you set the budget.
On price, resist budgeting from a national average. Michigan pricing tracks local labor availability and material lead times more than any published figure. The only number worth planning from is three written quotes on the same scope from licensed contractors in your county. If the work needs financing, a renovation loan or cash-out refinance placed through a broker funds it at one closing.
How Align finances a renovation
You are not just financing the house. You are financing a plan for it. Align places HomeStyle and FHA 203(k) renovation loans, standalone HELOCs and home equity loans, so the project can be paid for the way that fits it, not the way one bank prefers.
Samantha starts with why: what the work is, what it should cost, and whether your equity or a renovation loan is the better tool. Then one application goes to multiple wholesale lenders.
FAQ: Budget kitchen renovations
Here are answers to common questions about budget kitchen renovations.
What is the cheapest way to update a kitchen?
Paint or refinish the existing cabinets, swap the hardware, and update the lighting. That combination changes the entire visual character of a room for a few hundred to a few thousand dollars, versus five figures for new cabinetry. Adding a peel-and-stick or simple subway backsplash and a new faucet completes the refresh without touching plumbing or electrical.
Can I renovate a kitchen for under $10,000?
Yes, if you keep the layout and the cabinet boxes. A realistic under-$10,000 scope includes refinished cabinets, new hardware, a laminate or butcher-block countertop, a new sink and faucet, updated lighting, a backsplash, and paint. Replacing appliances or cabinetry, or moving any plumbing, will push the number well past that ceiling.
What is the biggest expense in a kitchen remodel?
Cabinets, typically 25% to 30% of the total, followed by labor and countertops. Appliances usually rank fourth. This ranking is why budget strategies focus almost entirely on cabinetry decisions: refinishing versus replacing, and stock or ready-to-assemble versus semi-custom or custom units. The same allocation discipline shows up in our guide to building a home on a budget.
Should I finance a kitchen renovation or pay cash?
It depends on the size of the project and your equity position. Small refreshes are usually best paid in cash. Larger remodels are often financed through a cash-out refinance, home equity loan, or a renovation loan that lends against the home’s after-improvement value. Comparing offers across lenders matters, because rates and fees vary widely on these products, our guide to the advantages of buying a fixer-upper covers the same math on a purchase.
The bottom line on renovating a kitchen on a budget
Renovating a kitchen on a budget comes down to two decisions and one habit. Leave the layout alone, because relocating the sink, range, or refrigerator adds a plumber, an electrician, permits, and patching to a job that needed none of them. Then attack the cabinets, which typically take 25% to 30% of the total: refinish or reface sound boxes, or buy stock and ready-to-assemble units before you price semi-custom. A minor remodel that follows both rules generally lands in the $15,000 to $27,000 national range instead of the six figures a major remodel commands. The habit is the 20% contingency.
If you’re ready to fund a kitchen project without guessing at the financing, talk to Align Lending. We’ll shop renovation loans, cash-out refinances, and home equity options across our lender network and show you the numbers side by side. Call 248-506-5727 or start online.
Footnotes:
1. Cost figures here are national ranges published by third-party remodeling cost surveys and guides. They describe what other projects have cost, not what yours will cost, and they are not an estimate, a bid, or an offer of credit. Pricing varies by region, scope, materials, and contractor availability. Where pricing is entirely quote-driven, this article states relative cost tiers rather than dollar figures on purpose. Return to text.
2. Example figures are hypothetical and for educational purposes only; they do not constitute an advertisement of credit terms or a rate quote under federal or state lending laws. The $18,000 budget, $3,600 contingency, and $4,500 to $5,400 cabinet allocation are arithmetic applied to the published percentage ranges cited above, not a projection for any specific kitchen. Return to text.
3. Align Lending is not acting on behalf of or at the direction of FHA or HUD. Program terms for FHA 203(k), Fannie Mae HomeStyle Renovation, and Freddie Mac CHOICERenovation loans are set by those agencies, are subject to change, and individual lenders may apply additional requirements. Eligibility is determined by a full application. Return to text.
4. This is a general description of Michigan construction code administration, contractor licensing, and property assessment, and it is not legal or tax advice. Permit thresholds, fee schedules, inspection requirements, and zoning overlays are set and enforced by the municipality with jurisdiction over your address, and the treatment of any specific improvement is determined by your local assessor under Michigan law. Return to text.
Sources: minor kitchen remodel range of roughly $15,000 to $27,000, major and upscale figures exceeding $100,000 and reported near $158,500, cabinetry at 25% to 30% of total spend, and the ranking of cabinets, labor, countertops, and appliances by share of budget, 2025 remodeling cost surveys and remodeling industry cost breakdowns. Typical kitchen remodel range of $14,600 to $41,485 and the 20% contingency guideline, This Old House kitchen remodeling guide. Permit triggers for new or relocated plumbing, electrical, and mechanical work and exemptions for in-place finish replacement, general residential permitting guidance; specific thresholds are set locally and are deliberately not stated here as numbers. Michigan Residential Code adoption of the 2015 International Residential Code, Mich. Admin. Code R 408.30500 et seq., administered by the Bureau of Construction Codes, Michigan Department of Licensing and Regulatory Affairs. Residential builder and residential maintenance and alteration contractor licensing, Michigan Occupational Code, 1980 PA 299, Article 24. Michigan treatment of additions and new construction separately from the annual cap on taxable value increases, MCL 211.27a and MCL 211.34d. Renovation lending against as-completed value, Fannie Mae HomeStyle Renovation, Freddie Mac CHOICERenovation, and FHA 203(k) program guidelines.
This article is for informational purposes only and is not intended to provide legal, financial, or tax advice. Construction costs, permitting requirements, contractor licensing rules, and property assessment practice vary by jurisdiction and change over time; verify them with your local building department, licensed contractors, and a qualified professional before relying on them. Program terms and figures shown are illustrative, are not a rate quote or an offer of credit, and are subject to change. Align Lending is an independent Michigan mortgage broker, NMLS #2041154.
Related resources
12-minute read
Energy-efficient home upgrades: What to do first, and what it saves
See which energy-efficient home upgrades pay off first, from air sealing and insulation to heat pumps and solar, with real costs and yearly savings.
12-minute read
DIY home renovation projects: 12 upgrades you can actually finish
Discover DIY home renovation projects that upgrade your space on a budget, from peel-and-stick backsplashes to floating shelves and smart lighting.
12-minute read
The benefits of a home energy audit and what it includes
Learn what a home energy audit finds, how blower door and infrared tests work, and why the Department of Energy ties audits to 5% to 30% savings.
